EURUSD
- EUR/USD Price: The EUR/USD pair finds temporary support on Friday after suffering four consecutive sessions of losses. The decline pushed the pair to a fresh yearly low at 1.1215, although the Euro is showing some signs of stabilization ahead of key economic data.
- French Budget: The French government presented its 2027 budget bill, targeting a reduction in the budget deficit to 5% of GDP. Markets remained sceptical about the prospects for meaningful fiscal tightening, with the French 10-year yield briefly reaching 4.96% and the spread over German 10-year bonds widening to a new post-euro-crisis high.
- Eurozone unemployment: The euro-area unemployment rate remained unchanged at 6.4% in August, in line with market expectations. This marked the seventh consecutive month at 6.4%, highlighting continued stability in the region’s aggregate labour market.
- Eurozone Inflation: Investors are awaiting the preliminary September HICP figures, with headline inflation expected to accelerate to 3.6% year-on-year from 3.2% in August.
- US NFP: The US Dollar is expected to trade cautiously ahead of the September Nonfarm Payrolls report due later on Friday. The employment data could provide fresh clues about the strength of the US labour market and influence expectations for Federal Reserve policy.
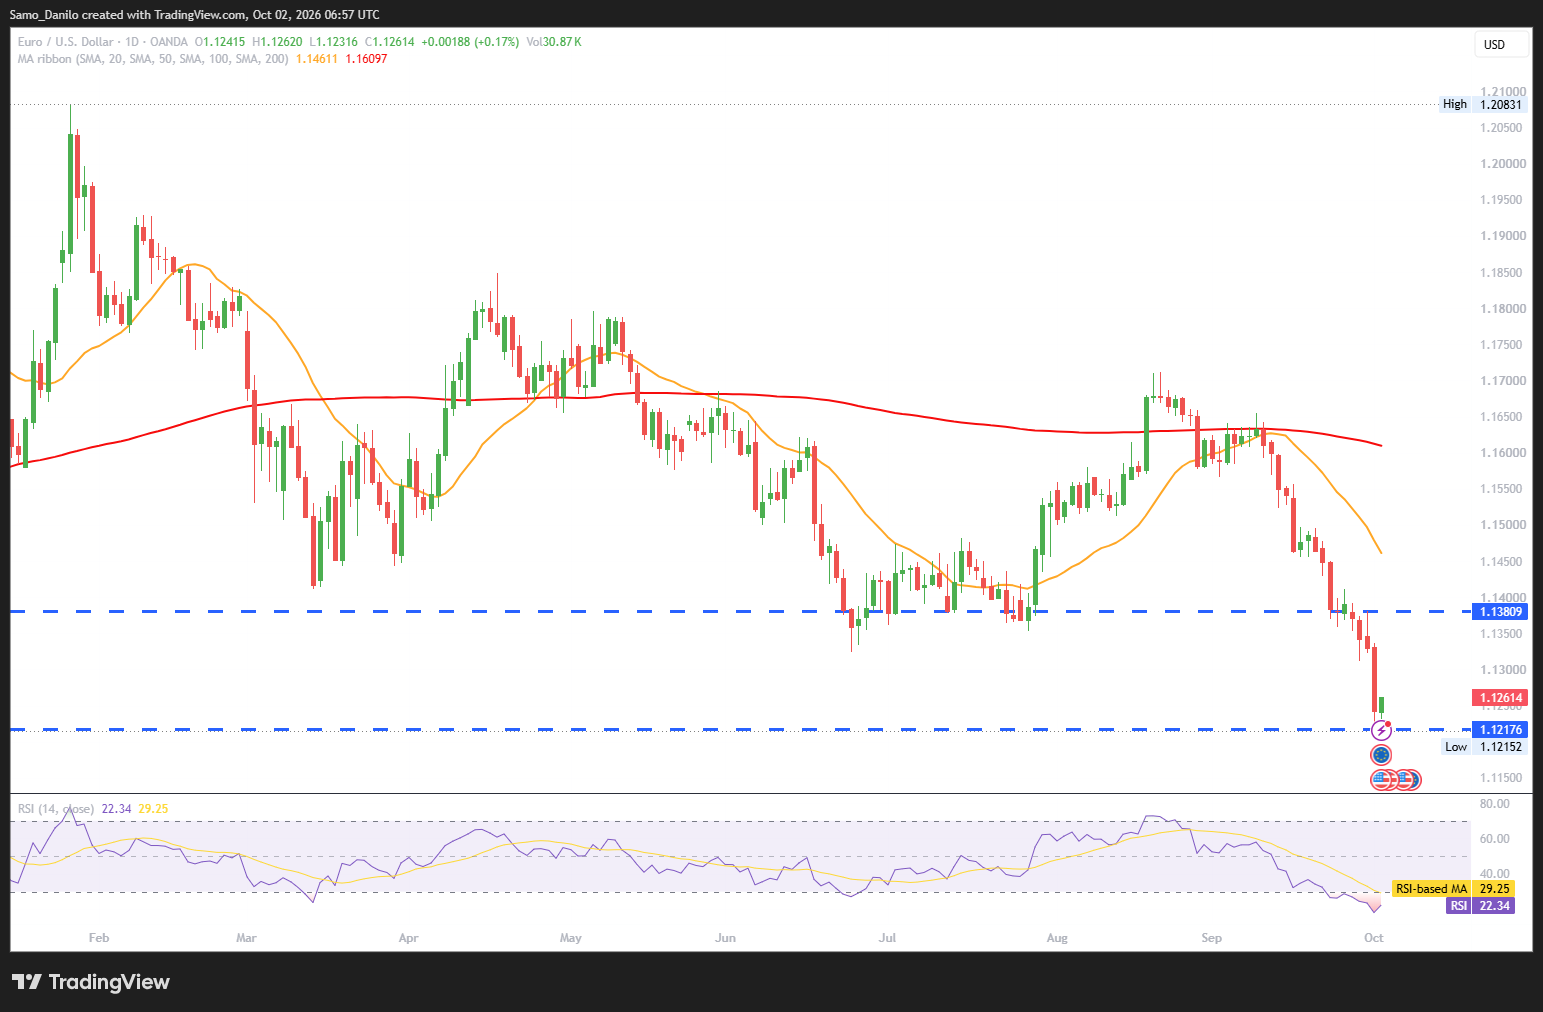
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near its yearly low of 1.1215, although the Euro has found temporary support after four consecutive sessions of declines. Eurozone inflation and the US Nonfarm Payrolls report will be the key catalysts, while developments in French public finances could continue to weigh on the Euro.
GBPUSD
- GBP/USD Price: The GBP/USD pair remains close to its lowest level since June 26, reached during the previous session, and trades just above the 1.3200 mark on Friday.
- Gilt yields: UK 30-year gilt yields climbed above 6% for the first time since early 1998, increasing concerns over the country’s fiscal outlook. The rise in long-term borrowing costs comes ahead of the Autumn Budget on October 28 and could add pressure on the Pound.
- BoE’s Mann: Bank of England policymaker Catherine Mann said the current monetary-policy stance is not sufficiently tight and that the central bank cannot rely on higher risk premia to do the work of monetary policy.
- Labour market: US continuing jobless claims fell to 1.701 million, below the 1.725 million consensus, while initial claims came in at 197,000 versus expectations of 200,000.
- US ISM: The US ISM survey for September fell slightly below expectations to 54.5 versus the 55.0 consensus, but remained firmly in expansionary territory. At the same time, the ISM price index jumped to 77.9, well above the expected 72.3, highlighting stronger price pressures that could influence expectations for Federal Reserve policy.
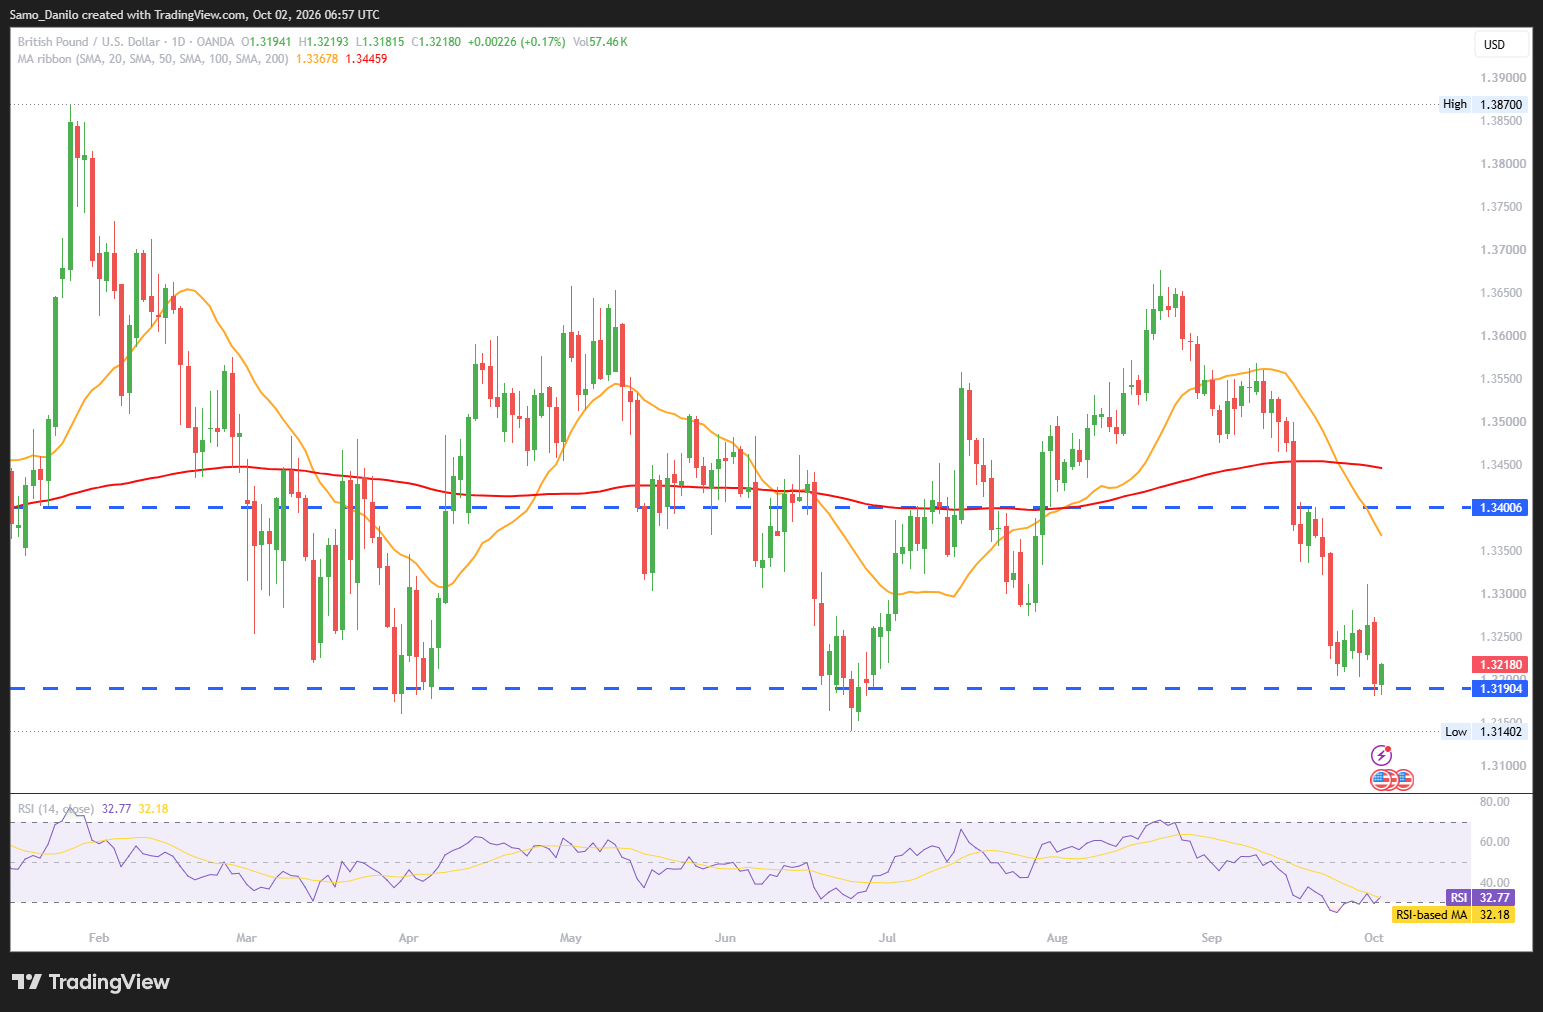
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains under pressure near 1.3200 as elevated UK gilt yields increase fiscal concerns and strong US labour-market data supports the Dollar. Although hawkish comments from BoE’s Mann could provide some support to the Pound, solid US activity and significantly higher price pressures keep the outlook sensitive to further US economic data and Fed policy expectations.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) reverses a modest decline seen during the Asian session on Friday and climbs back toward the $4,200 level.
- Fed's Logan: Dallas Fed President Lorie Logan said the Federal Reserve may need to raise short-term borrowing costs by at least another 50 basis points to make monetary policy “modestly restrictive” and bring inflation back toward target.
- Fed's Jefferson: Fed Governor Philip Jefferson delivered a message similar to Fed Chair Williams earlier in the week, suggesting that the central bank could take more time before deciding on its next interest-rate move.
- US-Iran: US President Donald Trump said on Wednesday that he would decide very soon whether to escalate military action against Iran, adding that the war would end very soon “one way or the other.”
- Jobs report: The September US employment report is due later on Friday, with expectations for nonfarm payrolls to increase by 100,000, unemployment to fall to 4.0% from 4.1%, and average hourly earnings to rise 0.3% month-on-month.
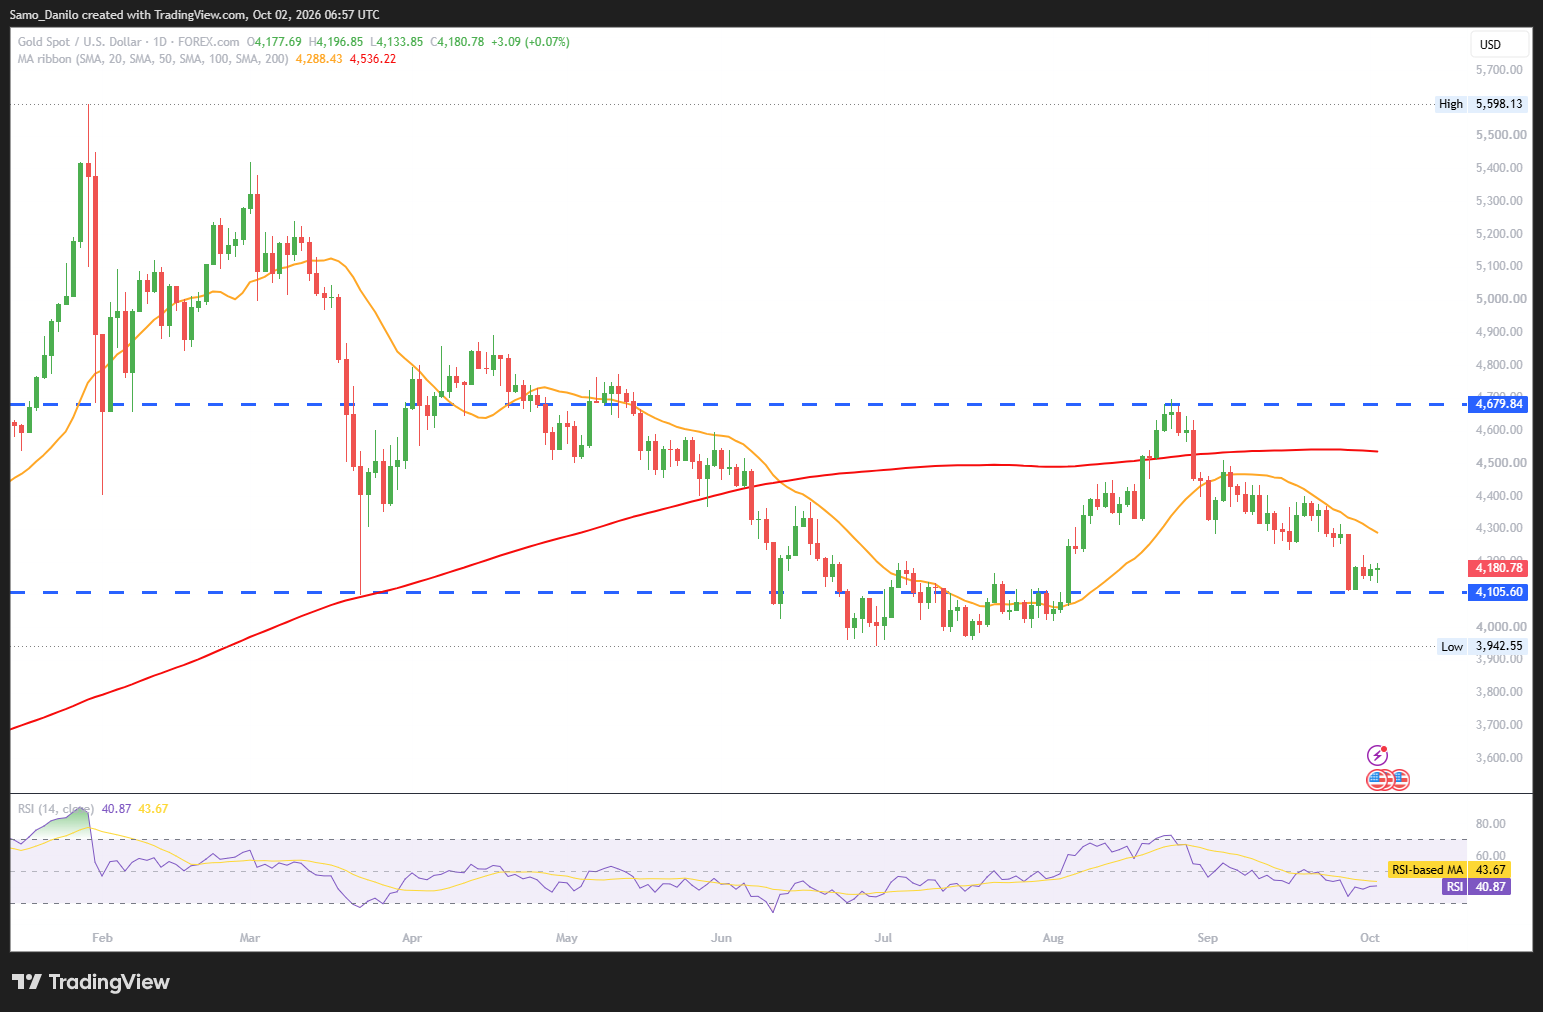
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD has recovered toward $4,200 as markets balance hawkish signals from some Fed officials against growing expectations that the central bank may take more time before its next move. The US jobs report will be the key near-term catalyst, while developments surrounding the US-Iran conflict could continue to influence safe-haven demand.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI) attracts fresh selling pressure during Friday’s European session, snapping a two-day winning streak. The move also stalls the previous day’s recovery from the vicinity of a nearly four-week low, with oil currently trading around $94.20.
- Middle East: The Wall Street Journal reported that the Pentagon is preparing to send a third aircraft-carrier strike group and additional troops to the Middle East.
- Diesel reserves: According to Reuters, US President Donald Trump is pressing Germany and France to draw down their emergency diesel reserves, while threatening a potential US diesel-export ban.
- Strait of Hormuz: Iran’s Persian Gulf Strait Authority said that several tankers had been attacked in the Strait of Hormuz in recent days.
- Putin's warning: Russian President Vladimir Putin said that the world is at a turning point and that countries need to consider how to avoid catastrophic scenarios, while stating that Russia is not threatening anyone.
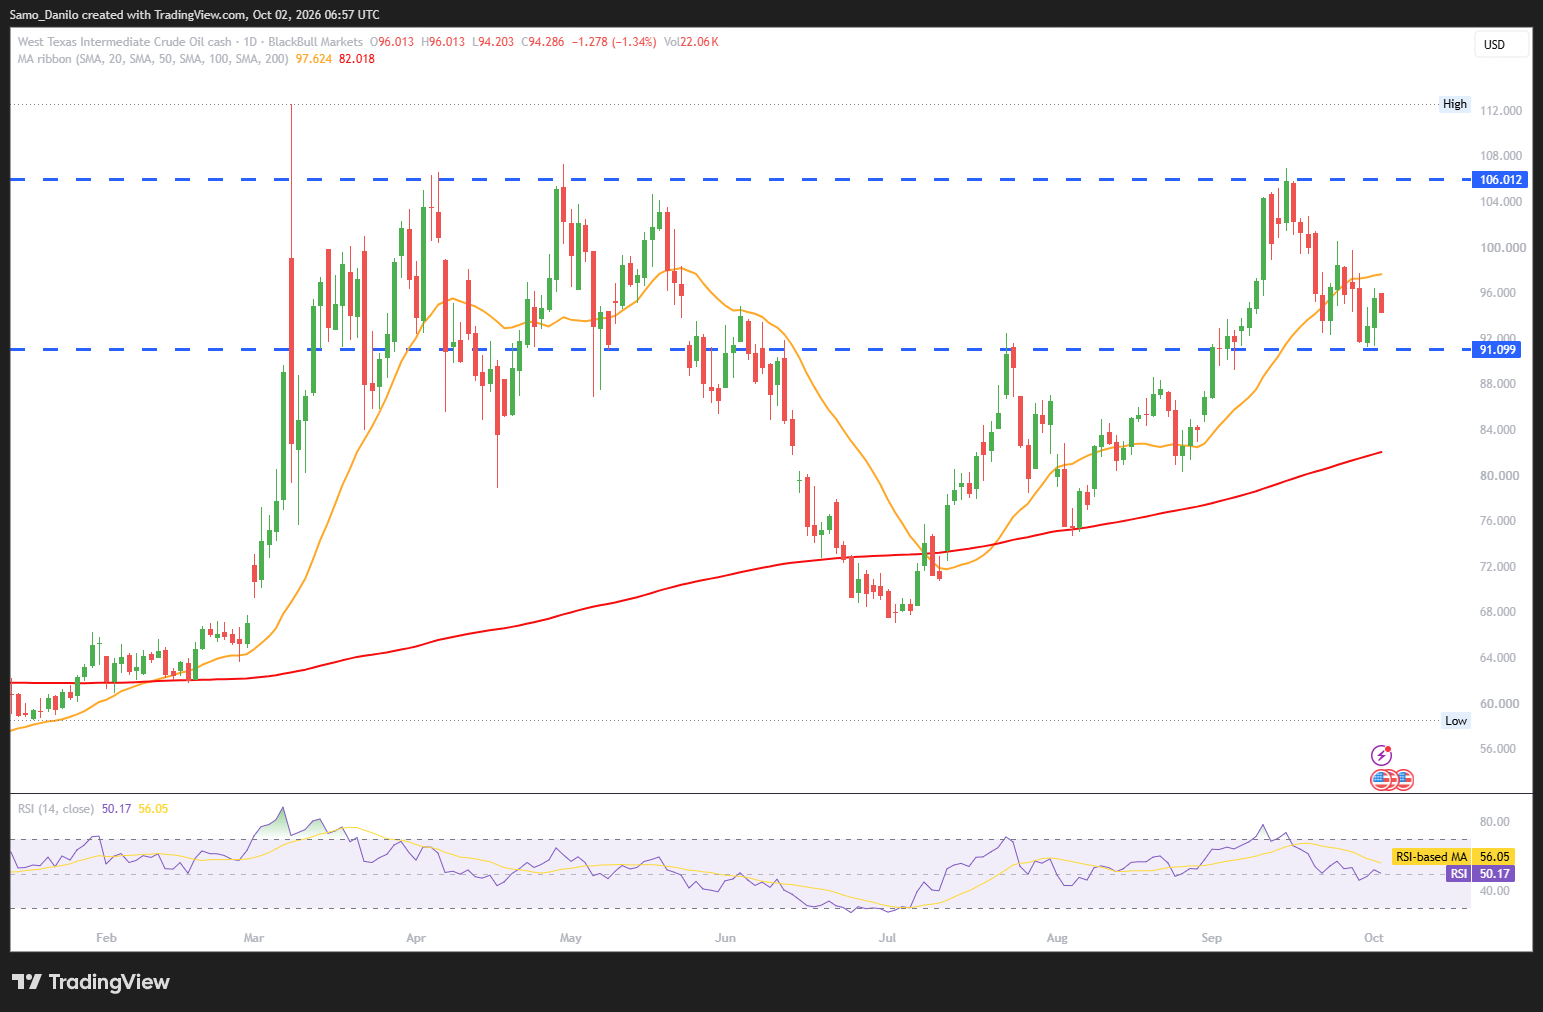
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Rising | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI trades near $94.20 after ending a two-day advance, but geopolitical risks remain elevated due to developments in the Middle East and reported tanker attacks in the Strait of Hormuz. Additional US military deployments and uncertainty over global diesel supplies could support oil prices, while developments in European fuel reserves and broader geopolitical tensions remain key factors for the market.
DAX
- DAX 40 Price: The DAX 40 trades higher around the 25,035-point level during Tuesday’s European morning session.
- German unemployment: German unemployment remains on a marginally upward trend, highlighting some softening in domestic labour-market conditions. In contrast, French unemployment has started to decline again after the upward trend recorded last year, pointing to diverging labour-market dynamics across the region.
- Diesel prices: EU Trade Commissioner Maroš Šefčovič said he discussed high diesel prices with US Trade Representative Jamieson Greer and expressed the EU’s desire for a coordinated approach.
- ECB's Nagel: ECB policymaker Joachim Nagel said that the central bank’s instruments are focused on delivering price stability rather than targeting specific bond-yield levels.
- German diesel: Germany’s Economy Ministry said there are currently no new requirements from the International Energy Agency regarding diesel reserves.
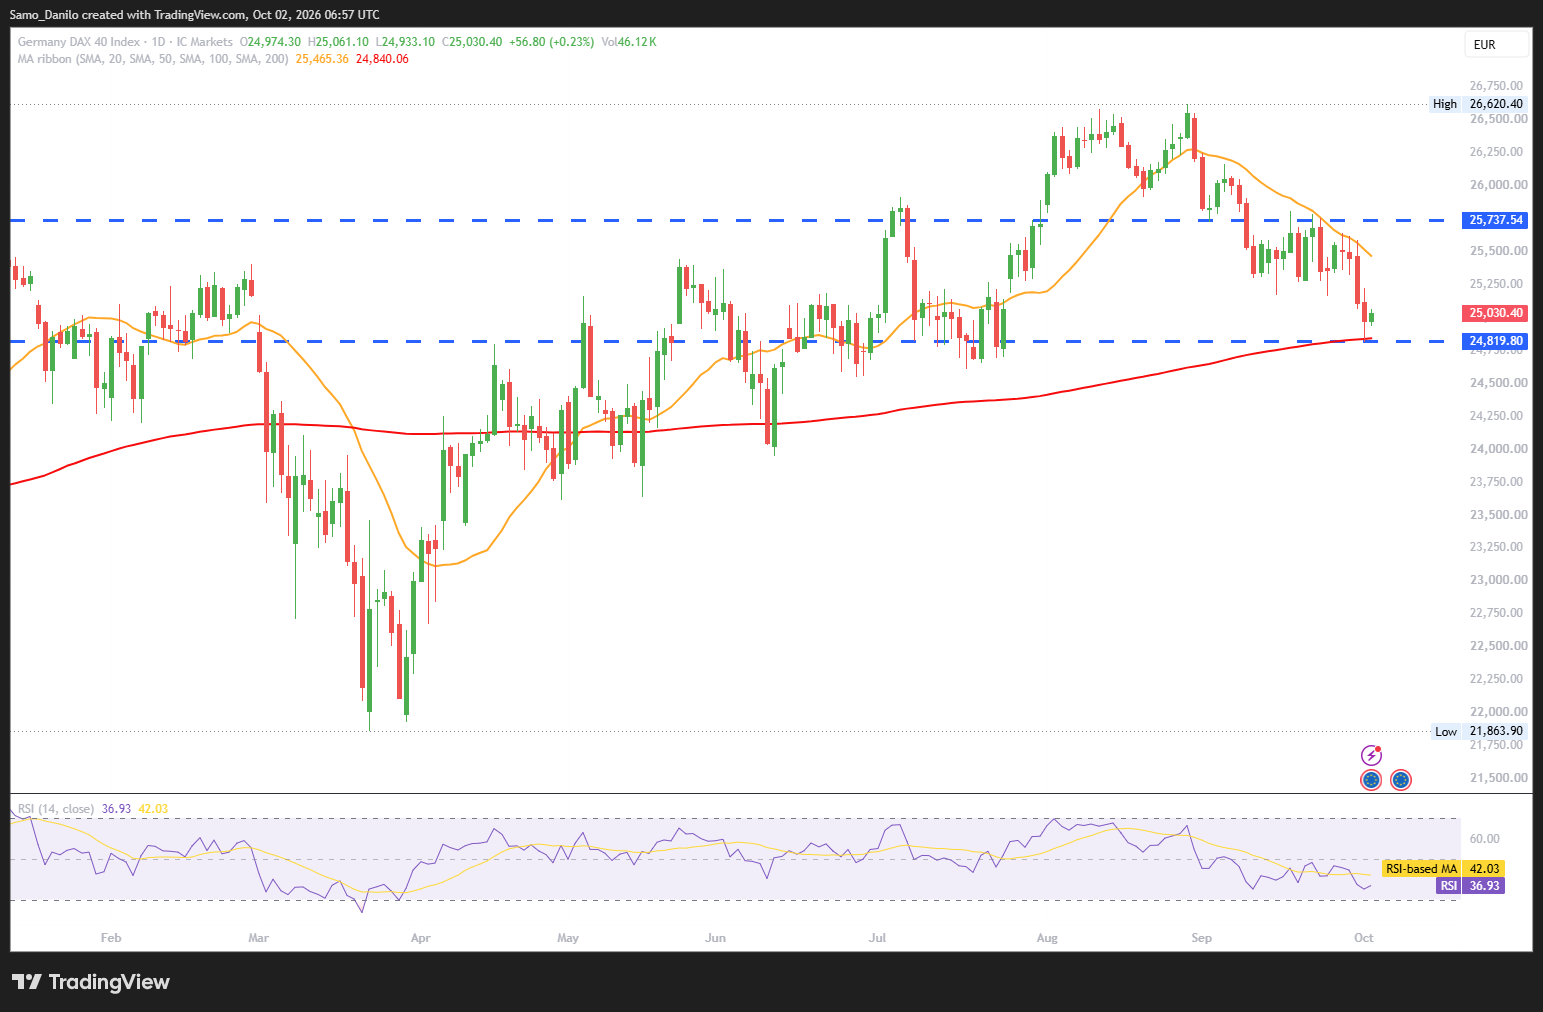
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 trades around 25,035 with investors balancing modest weakness in the German labour market against broader developments in European energy policy. ECB comments on bond yields and uncertainty surrounding diesel prices and reserves remain important factors for market sentiment, while developments in the European economy could influence the index’s next direction.