EURUSD
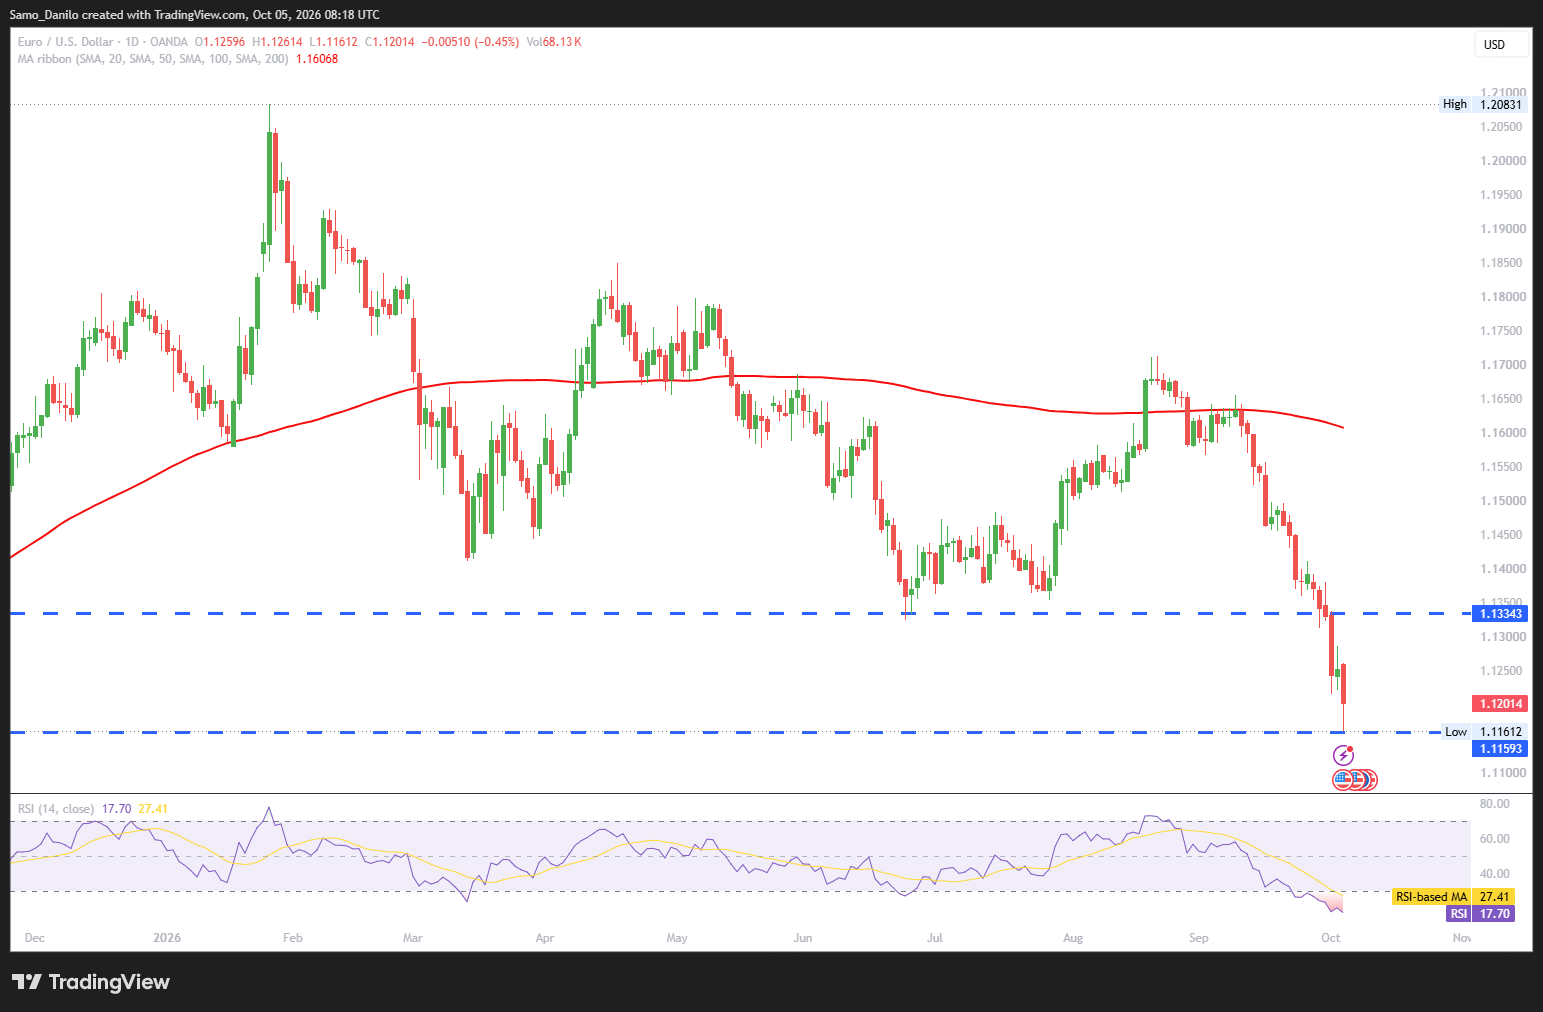
- EUR/USD Price: The EUR/USD pair loses momentum and trades around the 1.1200 level during Monday’s European session.
- Inflation numbers: Eurozone headline inflation increased to 3.8% year-on-year in September, slightly above the 3.7% consensus and significantly higher than August’s 3.2% reading. The acceleration, which was broadly anticipated by earlier national releases, could reinforce concerns about renewed inflationary pressure across the region.
- Analysts outlook: Standard Chartered analysts noted that underlying price pressures remain contained, with core inflation rising only modestly from 2.2% in January to 2.5% year-on-year in September.
- French budget: French Prime Minister Sébastien Lecornu’s minority government presented a €54 billion belt-tightening draft budget for 2027, aimed at preventing a potentially severe deterioration in France’s fiscal position.
- ECB’s Schnabel: ECB Executive Board member Isabel Schnabel is scheduled to speak, with markets likely to pay close attention to her assessment of inflation and the monetary-policy outlook.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1200 despite stronger-than-expected eurozone headline inflation, as relatively contained core inflation limits the case for a significant shift in ECB policy expectations. Meanwhile, uncertainty surrounding France’s fiscal position and Schnabel’s upcoming comments could influence the Euro’s near-term direction.
GBPUSD
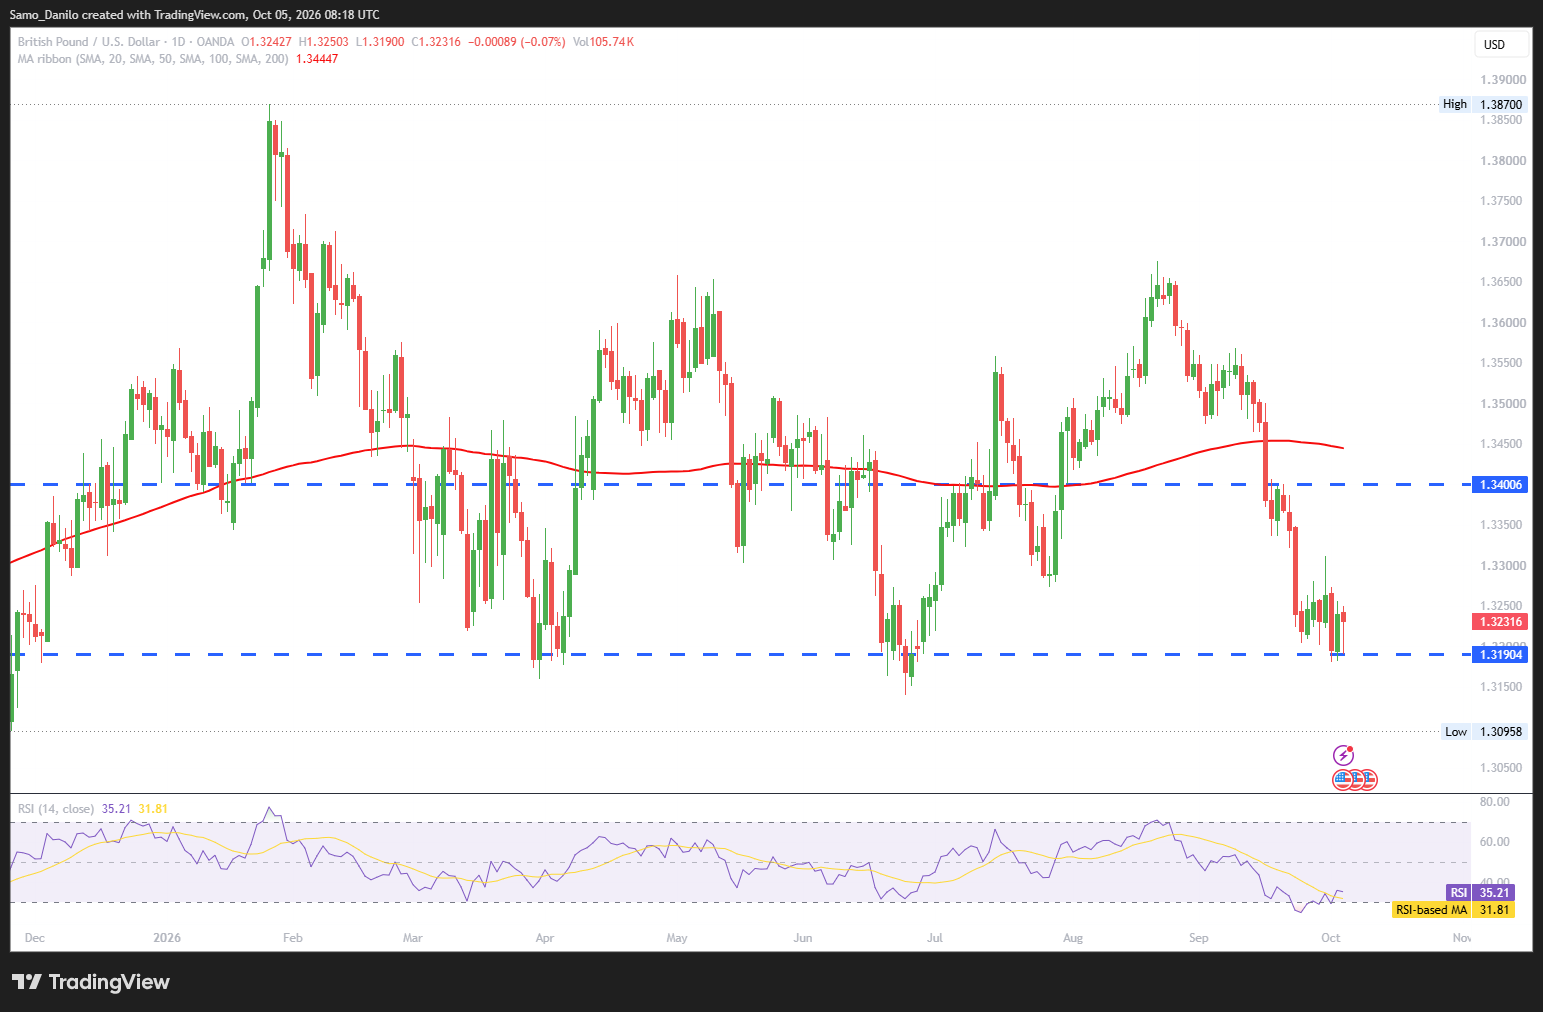
- GBP/USD Price: The GBP/USD pair declines toward the 1.3200 level during the early European trading session on Monday.
- Energy supply: Strikes by North Sea oil workers could “severely” disrupt UK fuel supplies following a breakdown in labour negotiations between Apache and its UK labour union.
- Jobs report: The September US employment report was weaker than expected, with nonfarm payrolls increasing by just 29,000 versus the 90,000 consensus, while August payrolls were revised down to 133,000 from 162,000. The unemployment rate also increased to 4.2% from 4.1%, slightly above expectations and pointing to some weakening in the US labour market.
- Security concerns: The US has withdrawn B-1 bombers stationed at RAF Fairford following a suspected terrorist plot targeting the airbase. The facility had been used by US forces for strikes against Iran after the UK government granted permission, keeping the security situation around the base and broader geopolitical risks in focus.
- Data ahead: Markets are awaiting the US ISM Services Purchasing Managers’ Index later on Monday.
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains near 1.3200 as UK energy-supply risks and fiscal concerns weigh on the Pound, although the weaker US jobs report could limit support for the Dollar. The upcoming US ISM Services PMI will provide an important test of the US economic outlook and could determine the pair’s next direction.
XAUUSD
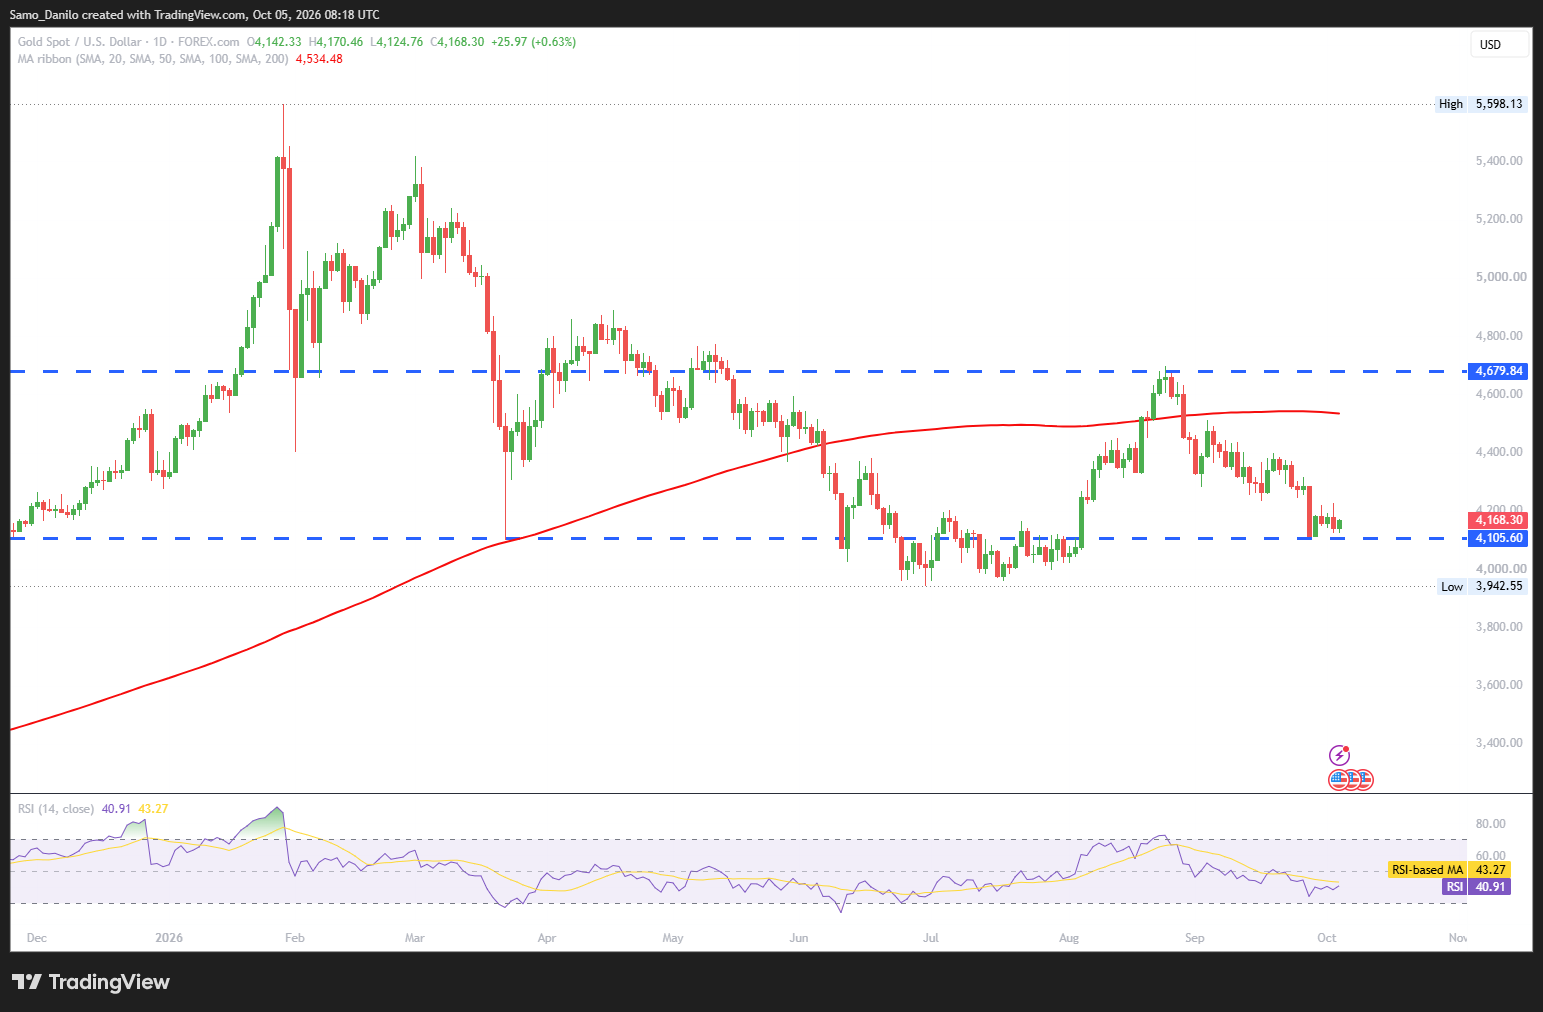
- XAU/USD Price: Gold (XAU/USD) edges higher toward $4,170 during the early European session on Monday.
- Geopolitical news: French bond yields and fiscal concerns remained important market drivers during the previous week, while higher diesel prices continued to raise concerns about the eurozone economy. Ukraine’s pledge to “double down” on attacks against Russian oil refineries adds further uncertainty to the energy-market outlook and could influence inflation expectations.
- AI Czar: US President Donald Trump confirmed the selection of an AI Czar, with Jay Clayton’s previous experience at the Securities and Exchange Commission potentially pointing toward a relatively relaxed regulatory approach.
- Fed's Hammack: Federal Reserve policymaker Beth Hammack, a voting member known for her hawkish stance, said there is still time to assess the next monetary-policy move.
- Market odds: Traders are now pricing in a 77.9% probability that the Federal Reserve will leave interest rates unchanged at its October meeting, up from 74% before the latest data.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains near $4,170 within its recent trading range as markets balance European fiscal and energy risks against uncertainty surrounding the Federal Reserve’s next move. Rising expectations for an October rate hold and a patient tone from Fed officials could support gold, although the absence of a clear breakout keeps the near-term outlook broadly range-bound.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI) attracts fresh selling pressure during Monday’s European session. The oil benchmark currently trades around $92.70.
- G7 decision: G7 leaders agreed to release 100 million barrels of crude oil and diesel over the next four months following pressure from US President Donald Trump.
- IEA release: The International Energy Agency said its member countries have so far released around 325 million barrels of oil out of the 400 million barrels pledged in March.
- OPEC+ decision: OPEC+ members agreed over the weekend to leave their oil production targets unchanged for November.
- Shipping route: Yemen’s Saudi-backed government has launched a counter-offensive to retake areas controlled by the Houthis after the group seized the Bab el-Mandeb Strait last month.
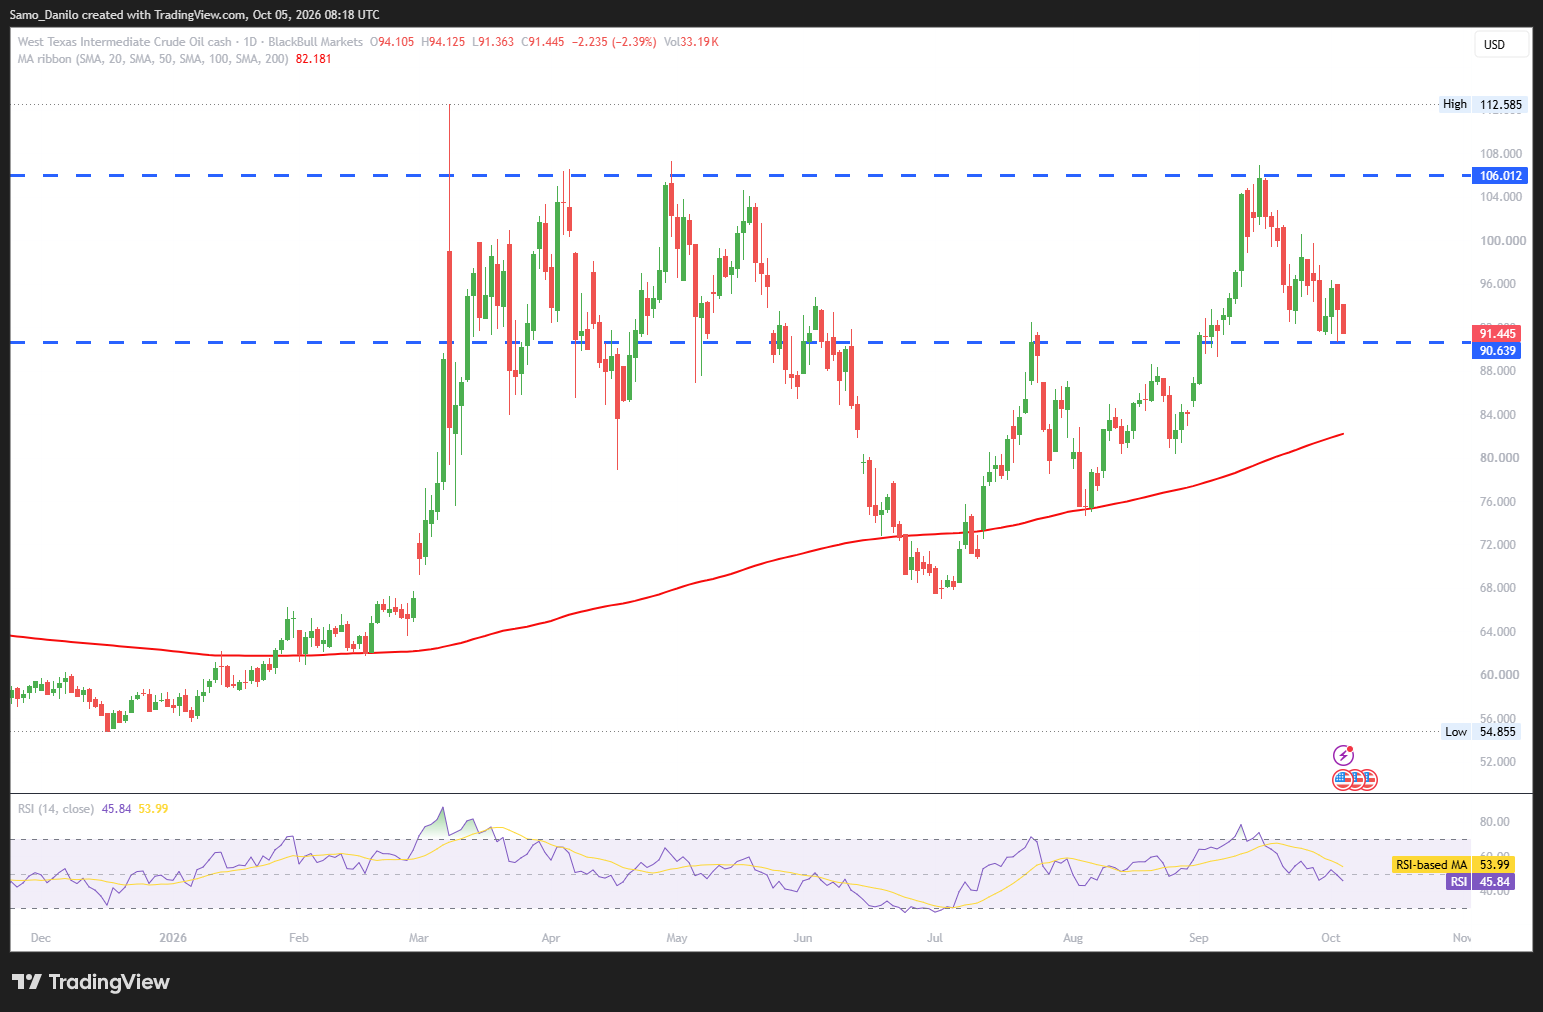
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: WTI remains around $92.70 as large strategic-reserve releases by the G7 and continued IEA releases point to increased near-term oil supply. However, unchanged OPEC+ production targets and rising tensions around the Bab el-Mandeb Strait could provide support and limit the downside, keeping geopolitical developments central to the outlook.
DAX
- DAX 40 Price: The DAX 40 trades lower around the 25,190-point level during Monday’s European morning session.
- Eurozone growth: The EuroCOIN indicator points to continued solid euro-area GDP growth momentum, with the measure suggesting expansion of around 0.4% quarter-on-quarter in Q3.
- French debt: According to a report from the Associated Press, French public debt has reached 119% of GDP. French government bonds have faced selling pressure in recent weeks amid expectations of higher policy rates and increasing political and fiscal risks, adding to concerns across European markets.
- US-Russia talks: The New York Times reported that discussions between the Trump administration and Russia over ending the Ukraine war now include a potential multibillion-dollar oil deal.
- Data ahead: The euro area’s Sentix investor confidence indicator will provide the first assessment of investor sentiment for October. Final services and composite PMI figures are also due, with expectations that they will remain close to the preliminary readings and provide further insight into the region’s economic momentum.
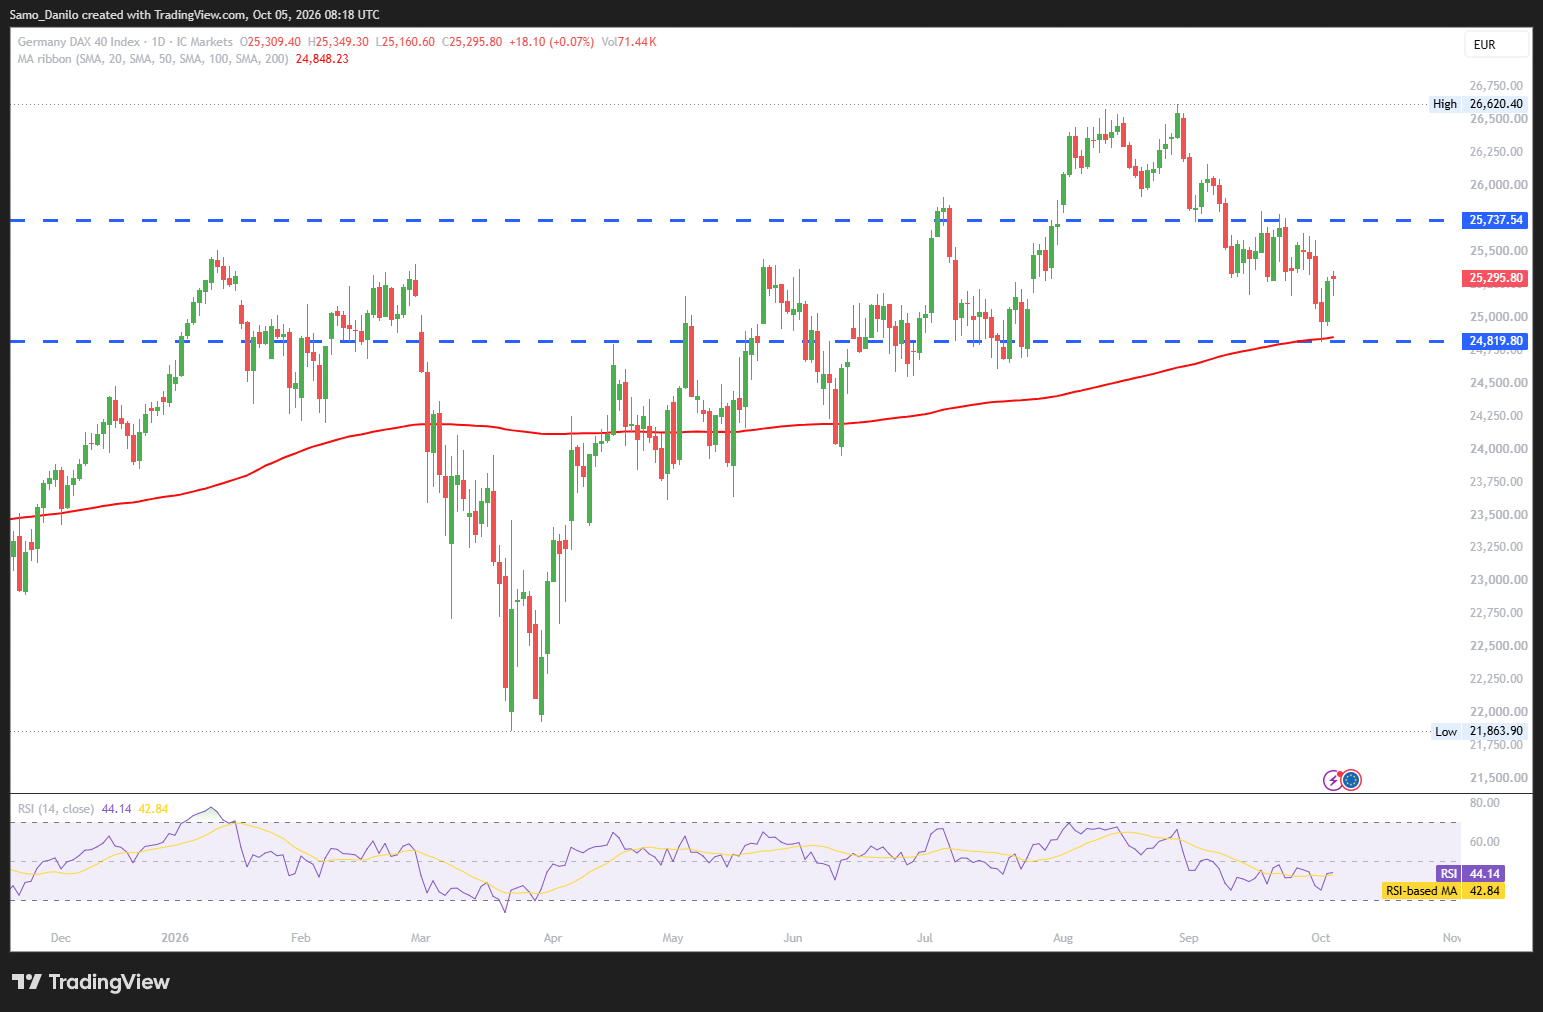
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 remains under pressure near 25,190 despite signs of solid euro-area growth momentum. Rising French debt and political risks continue to weigh on sentiment, while the upcoming Sentix and PMI data, alongside geopolitical developments involving Russia and Ukraine, could determine the index’s next direction.