EURUSD
- EUR/USD Price: The EUR/USD pair continues to move lower against a firmer US Dollar on Tuesday, trading around the 1.1200 level.
- French bond: The spread between French OAT yields and German Bund yields has widened to levels not seen since the 2009 financial crisis.
- Political uncertainty: France remains affected by political gridlock, reducing the prospects for a significant fiscal savings plan before the 2027 presidential elections. Meanwhile, Spanish Prime Minister Pedro Sánchez has announced a snap election in November, adding another source of political uncertainty within the euro area.
- ECB policy: The European Central Bank faces a challenging policy environment as it attempts to balance inflation risks against growing pressure in government bond markets.
- Investor confidence: The Sentix investor confidence indicator fell to 2.7 in October from 5.1 in September, significantly below the market expectation of 4.3.
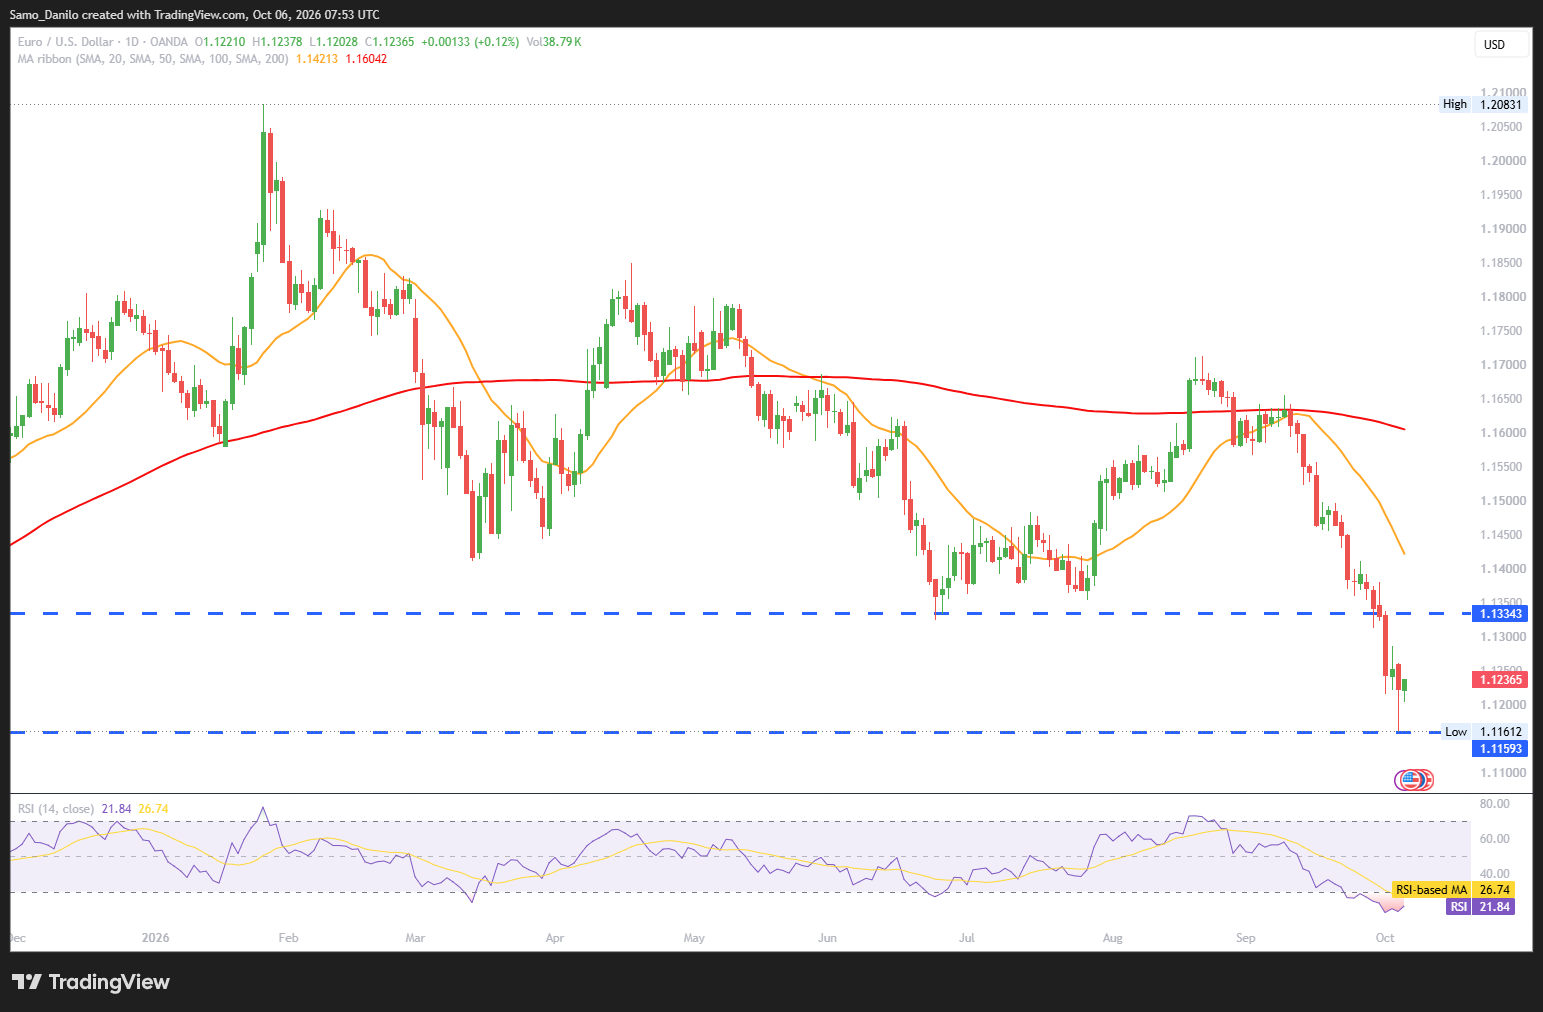
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1200 as rising French bond-market stress, political uncertainty and weaker euro-area investor confidence weigh on the Euro. The ECB’s difficult policy balancing act could remain a key factor, while developments in European government bond markets and fiscal policy are likely to influence the pair’s near-term direction.
GBPUSD
- GBP/USD Price: The GBP/USD pair continues its consolidative move during Tuesday’s European session, trading above the 1.3200 mark.
- BoE rate: Markets are increasingly pricing in tighter monetary policy from the Bank of England amid persistent inflationary pressures linked to elevated energy prices.
- US services: The US ISM Services PMI released on Monday showed that business activity slowed more than expected in September. At the same time, prices paid by businesses increased while demand remained relatively strong, highlighting persistent price pressures despite the moderation in activity.
- UK diesel: UK Government Spokesperson Wells said the country has diverse and resilient supplies of diesel, helping to ease concerns over potential fuel shortages. BP CEO Murray Auchincloss also said the company has adjusted its refineries to increase diesel production and has no intention of reducing its presence in the Middle East.
- Red Sea tensions: Yemen’s armed forces claim to have taken control of the Red Sea port of Mocha, located near the strategically important Bab el-Mandeb Strait.
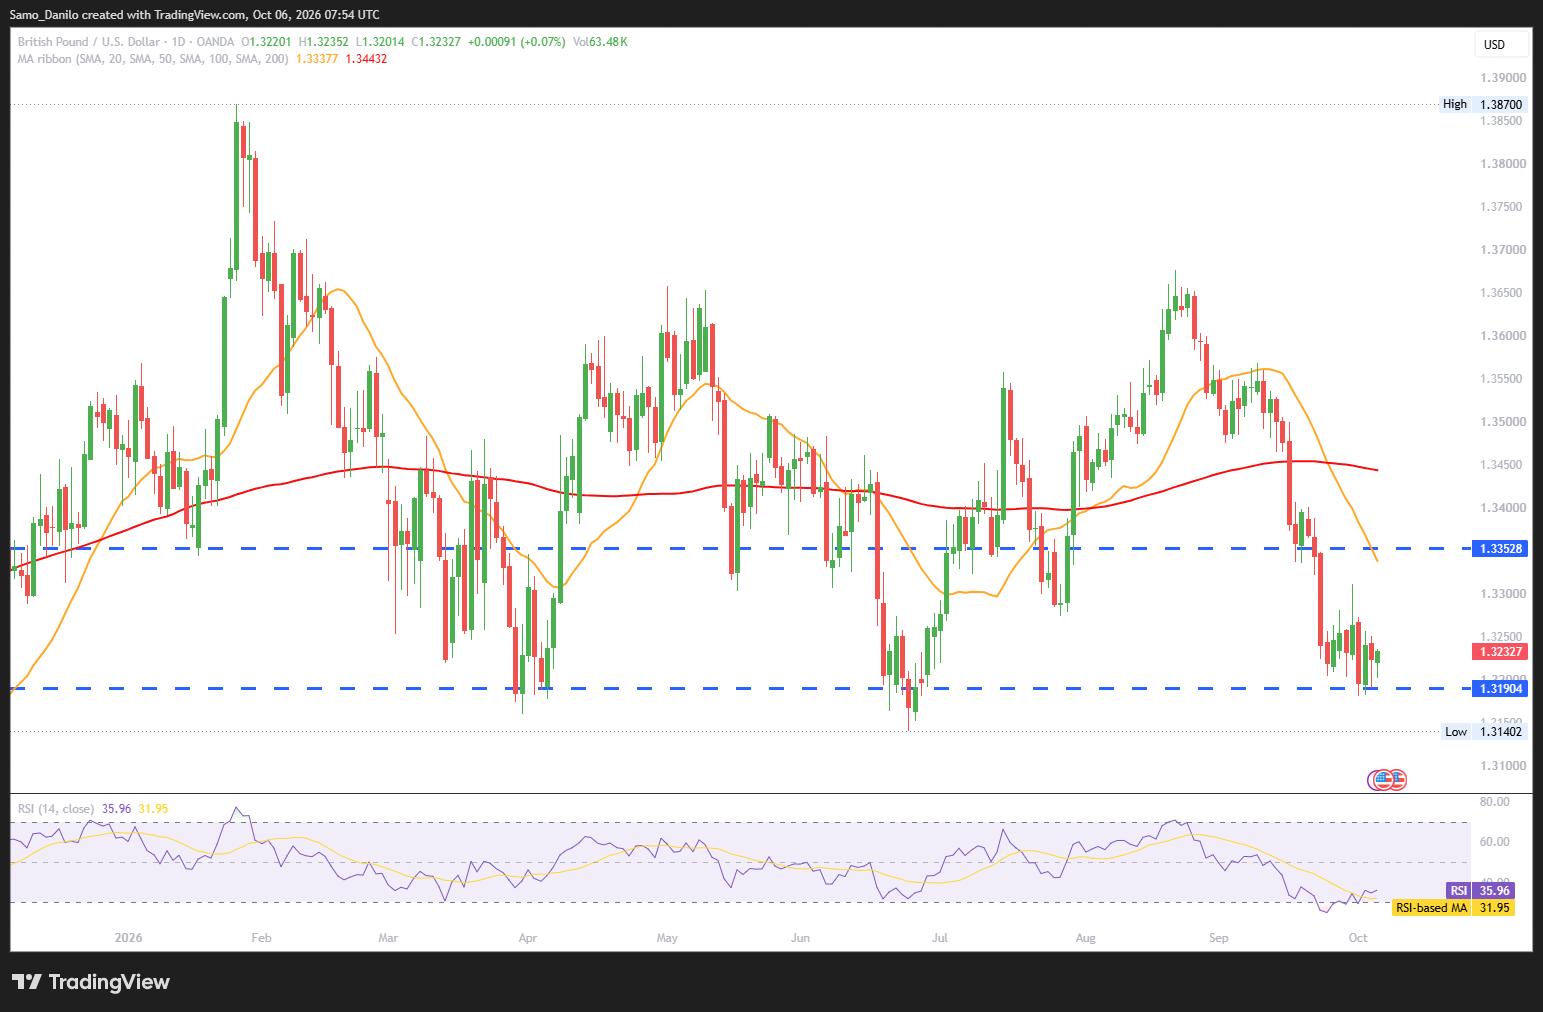
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains range-bound above 1.3200 as expectations for tighter BoE policy provide support to the Pound, while weaker-than-expected US services activity could limit Dollar strength. However, persistent energy-price pressures and developments around the Bab el-Mandeb Strait remain important risks for the pair’s near-term direction.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) extends modest intraday losses heading into the European session on Tuesday, but remains above the $4,100 level.
- Fed NY: The Federal Reserve Bank of New York is reportedly visiting major banks to conduct private reviews of credit conditions, with Morgan Stanley, Wells Fargo and Barclays among the institutions named.
- US investments: US President Donald Trump announced that Becton Dickinson & Company will invest $3 billion to expand domestic manufacturing of essential medical products. More than $1 billion is expected to be invested in Nebraska, including expanded production of products such as needles made with American steel, highlighting continued investment in US manufacturing.
- US services: The US ISM Services PMI came in slightly below expectations at 54.9 in September, compared with the 55.0 consensus and 55.4 previous reading. Despite the modest slowdown, the index remains comfortably above the 50 threshold, indicating continued expansion in the services sector and limiting concerns about a sharp deterioration in US activity.
- FOMC minutes: Traders remain hesitant to establish fresh directional positions as they await clearer signals on the Federal Reserve’s policy path. The FOMC Minutes, due on Wednesday, will therefore be closely watched for clues about policymakers’ views on inflation, economic conditions and the timing of future rate decisions.
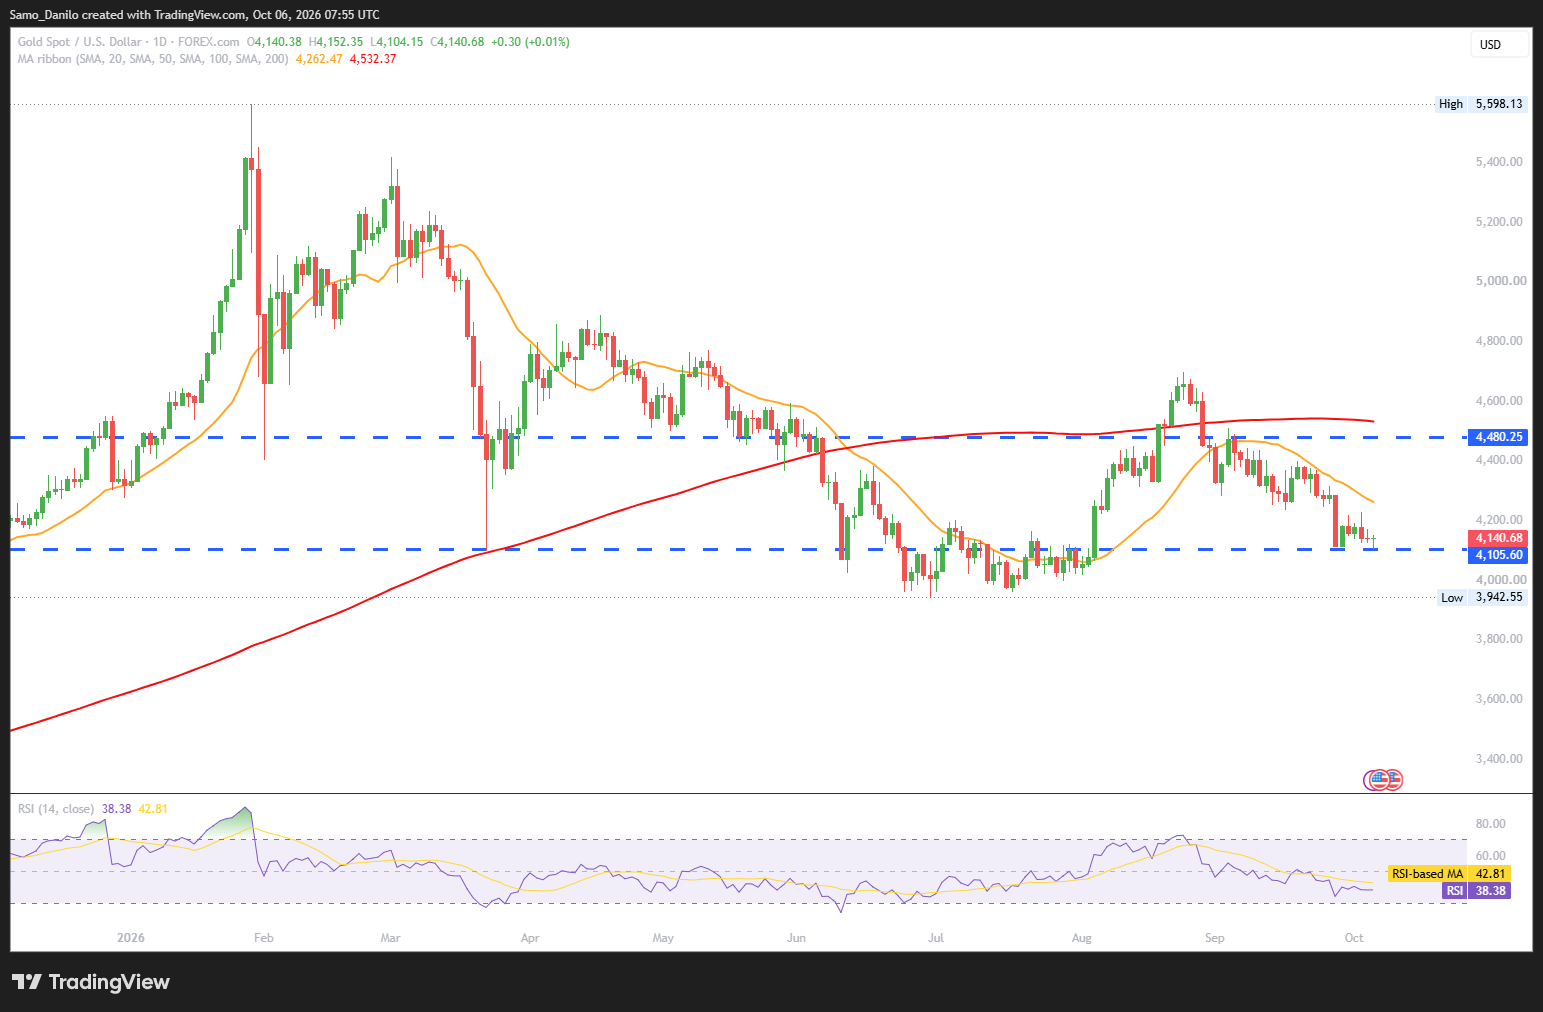
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains under pressure above $4,100 after touching a two-month low, while solid US services activity continues to limit support for the non-yielding asset. However, the cautious positioning ahead of the FOMC Minutes suggests that the next significant move could depend on fresh signals regarding the Federal Reserve’s monetary-policy outlook.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI) edges lower during Tuesday’s European session, snapping a two-day winning streak.
- Diesel restrictions: US President Donald Trump signed an executive order temporarily easing restrictions on the use of tax-exempt red diesel on public roads.
- Houthi attacks: Yemen’s Houthi group said it carried out three military operations using ballistic and cruise missiles and drones against airports, an oil facility and military sites across Saudi Arabia.
- Middle East: Media reports suggest that Israel is preparing for a potential attack against Iran, either in coordination with the United States or independently.
- Russia-Ukraine: Moscow Mayor Sergei Sobyanin said Ukraine launched 650 drones toward Russia’s Moscow region overnight, according to reports.
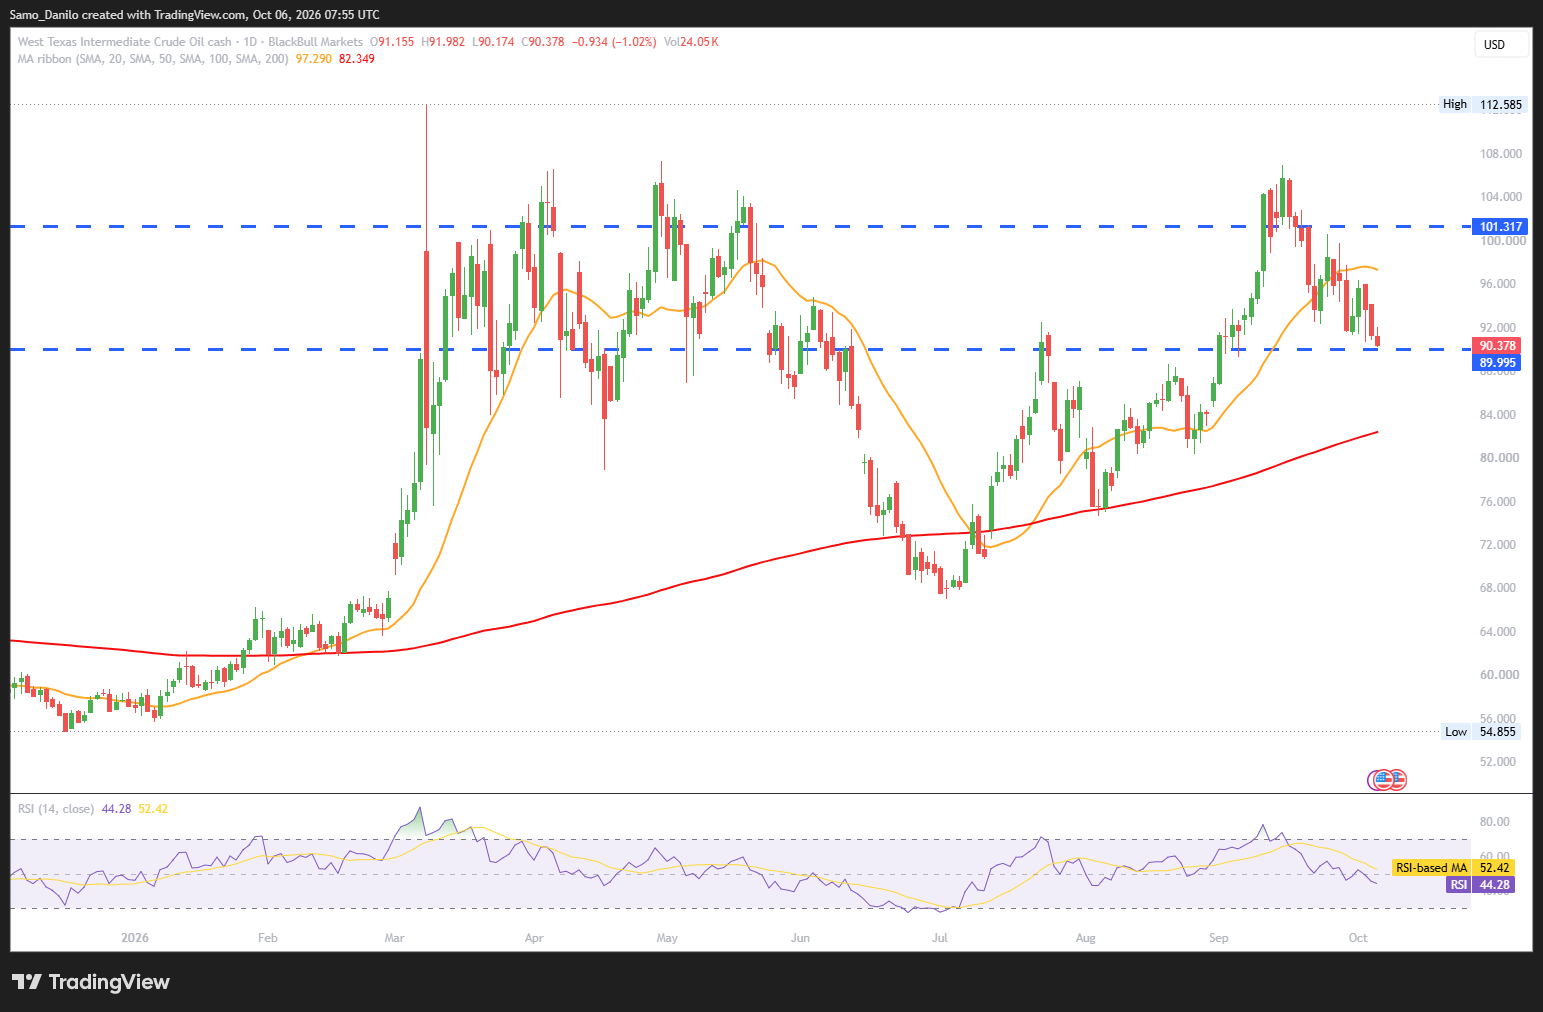
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains around $90.00 after snapping a two-day advance, with US measures aimed at easing fuel-price pressures potentially limiting upside. However, escalating tensions involving the Houthis, Israel and Iran, together with renewed Russia-Ukraine hostilities, could provide significant support to oil prices if concerns over supply disruptions intensify.
DAX
- DAX 40 Price: The DAX 40 trades higher around the 25,430-point level during Tuesday morning’s European session.
- EU trade: Germany and France are urging the European Union to adopt stronger trade powers that could restrict access to the single market for China and other countries if they are deemed to destabilise trade relations. In a letter to European Commission President Ursula von der Leyen, the two governments called for “powerful measures”, highlighting growing concerns over external trade dependencies.
- Hybrid attacks: EU Foreign Affairs Policy Chief Kaja Kallas said the Kremlin is putting lives at risk across Europe through hybrid attacks.
- French CB: French central bank governor Emmanuel Moulin warned that France risks being “strangled by interest rates” if it fails to take measures to repair its public finances.
- Factory orders: Data from Destatis showed that new orders for German manufactured products fell 10.6% in August after increasing 3.2% in July. The decline was significantly larger than the 1% fall expected by markets, pointing to renewed weakness in Germany’s industrial sector and potentially weighing on the DAX.
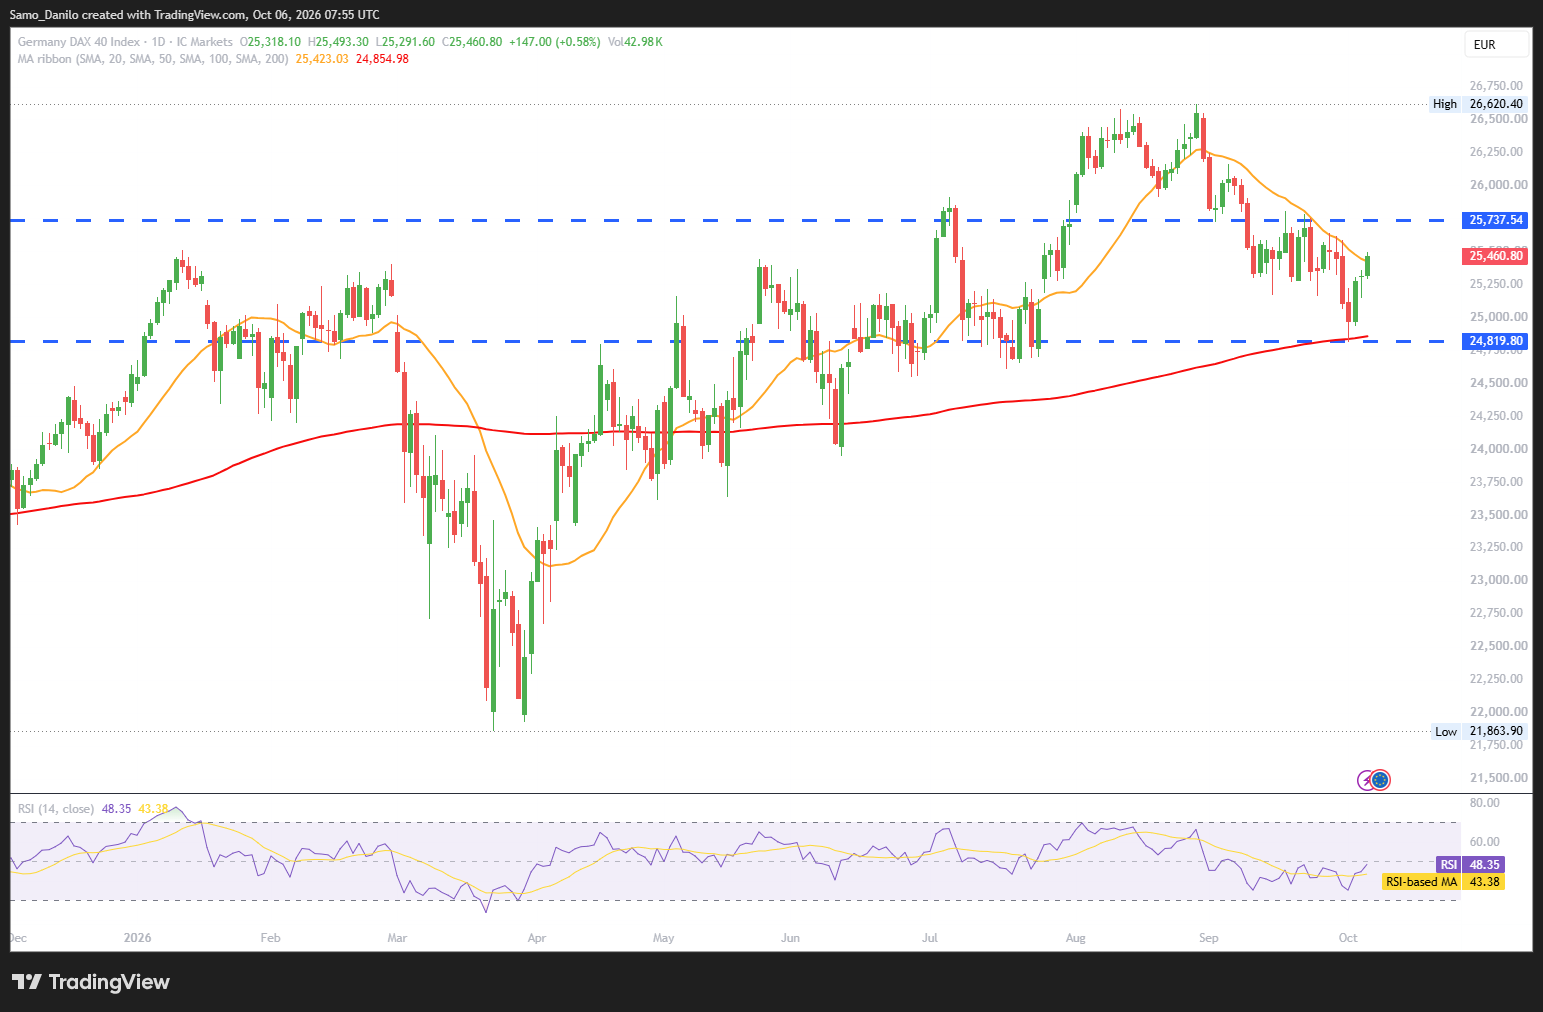
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 trades near 25,430 despite a sharp decline in German factory orders and growing fiscal and geopolitical concerns across Europe. Stronger EU trade powers could provide some protection for European industry, but weak German manufacturing data and rising risks surrounding France’s public finances remain important challenges for the index.