EURUSD
- EUR/USD Price: The EUR/USD pair trades at session lows around 1.1225 during Wednesday’s European session, down from Tuesday’s high near 1.1275.
- French budget: The Euro found some support on Tuesday after Marine Le Pen announced a plan to reduce government spending by €140 billion over the next five years. The proposal aims to bring France’s fiscal deficit below 3% of GDP by 2030 from the current 5.1%, providing some relief to concerns over the country’s public finances.
- Norway’s budget: The Norwegian government is set to publish its 2027 fiscal budget, with expectations pointing to a slightly expansionary fiscal stance of around 0.1% of GDP.
- Polish CB: The National Bank of Poland is expected to leave its policy rate unchanged at 3.75%. The decision will be monitored for any signals regarding the central bank’s future policy direction and the broader monetary-policy environment in Central Europe.
- Labor market: ADP’s average weekly private employment measure increased by 23,750 over the four weeks ending September 19, marking the strongest increase since early June.
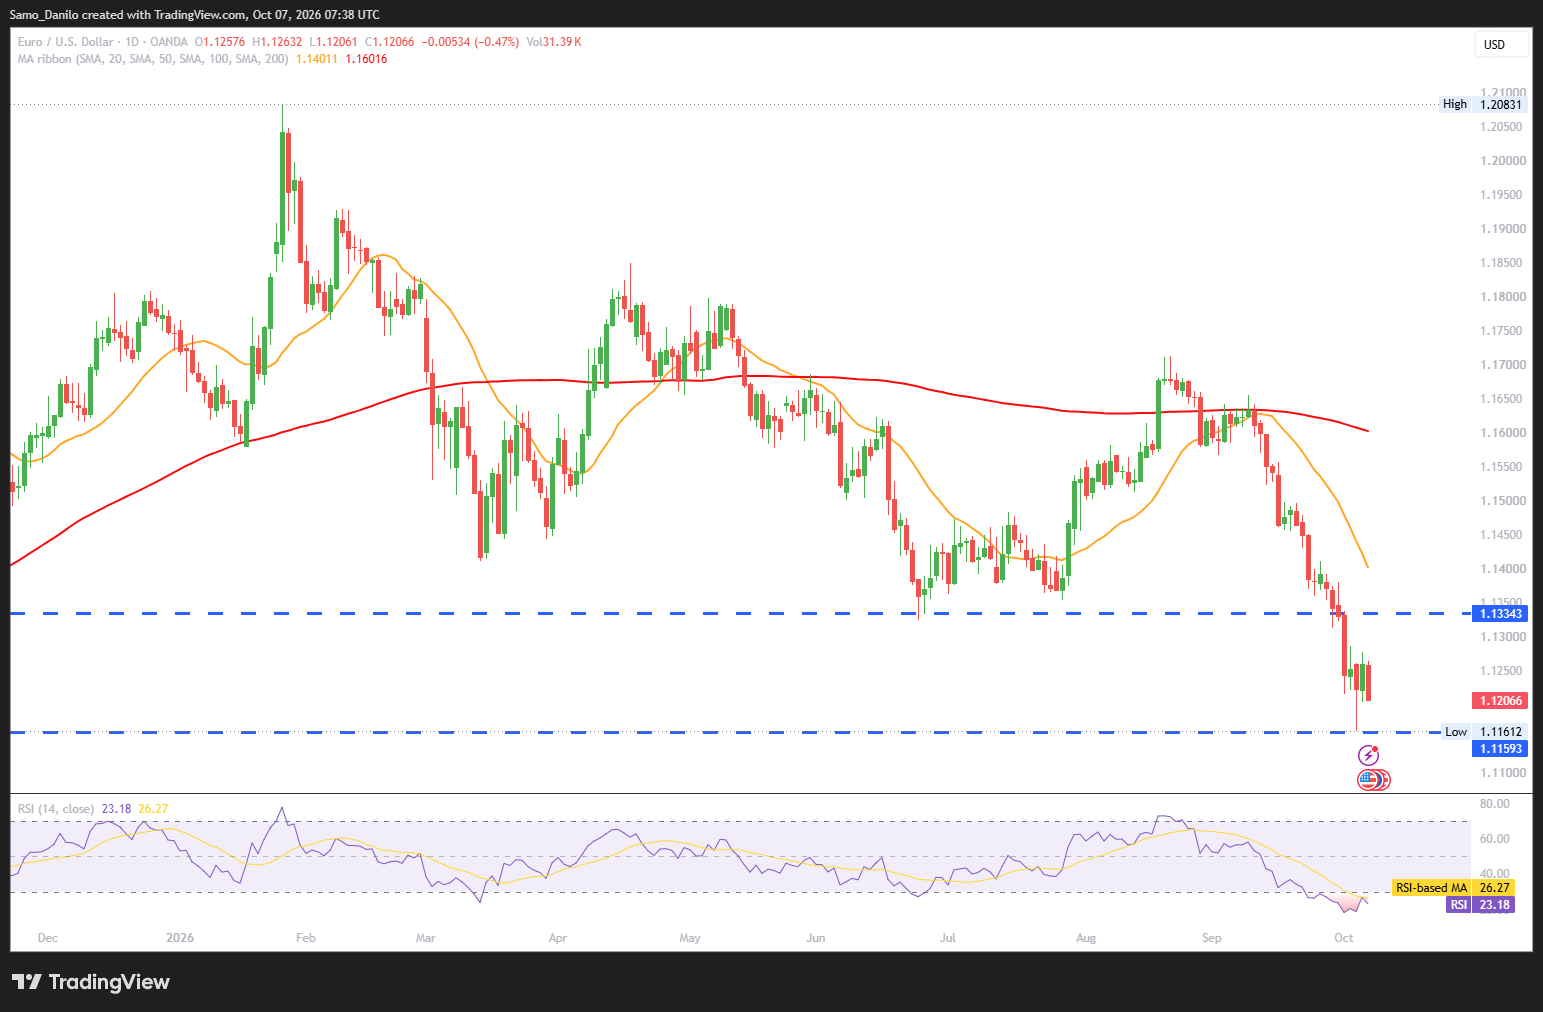
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1225 after retreating from Tuesday’s high of 1.1275. While France’s proposed spending cuts provide some relief for the Euro, improving US private employment and relatively firm Dollar sentiment could limit the pair’s upside, keeping the 1.1200 area in focus.
GBPUSD
- GBP/USD Price: The GBP/USD pair loses ground after recording modest gains during the previous session, trading around 1.3250 in Wednesday’s European session.
- BoE rate: Elevated energy prices and persistent inflation concerns could support the British Pound by reinforcing expectations that the Bank of England will keep interest rates higher for longer.
- BoE's Mann: BoE policymaker Catherine Mann warned that inflation above the central bank’s 2% target appears increasingly embedded in the UK economy. She also suggested that inflation could reach around 4% around the turn of the year as wage negotiations typically accelerate, reinforcing the case for a cautious approach to monetary easing.
- Labor Market: The ADP preliminary employment measure for the four weeks ending September 19 increased by 23.8K, up from 20.0K previously. Hiring has now accelerated for a fifth consecutive week, suggesting improving momentum in the US private labour market and potentially providing support to the Dollar.
- FOMC Minutes: The US Dollar is regaining ground against most major currencies on Wednesday as investors await the minutes of the September Federal Open Market Committee meeting.
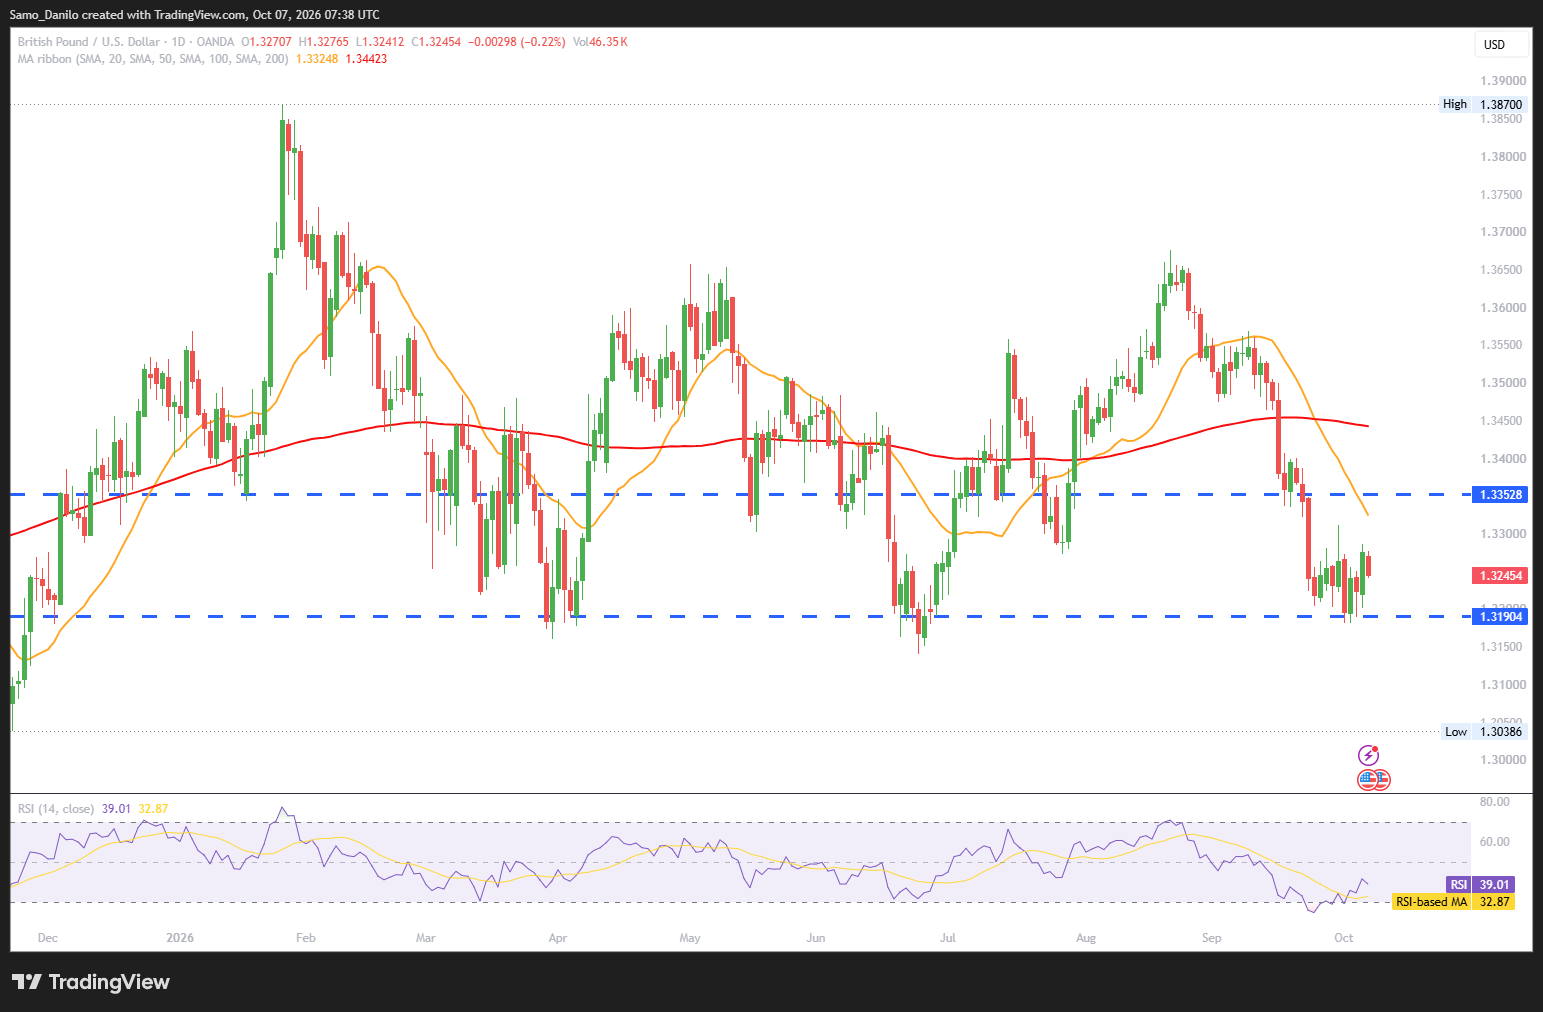
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains around 1.3250 as expectations for persistently high UK inflation and a higher-for-longer BoE stance provide some support to the Pound. However, improving US private employment and renewed Dollar strength ahead of the FOMC Minutes could limit the pair’s upside and increase volatility during the session.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) maintains a bearish bias during Wednesday’s early European session, remaining close to the two-month low around $4,100 touched on Tuesday.
- US inflation: US inflation remains well above the Federal Reserve’s 2% target, keeping expectations for further monetary tightening elevated. According to the CME FedWatch Tool, futures markets are pricing in the possibility of another rate hike in December and at least one additional increase during the first quarter of 2027, creating a headwind for non-yielding gold.
- Trump-Putin talks: US President Donald Trump said he would speak with Russian President Vladimir Putin “very soon” following the reported death of a laboratory worker from a suspected case of pneumonic plague in Siberia.
- PBOC gold: The People’s Bank of China continued its gold-buying streak, with official reserves increasing to 77.5 million troy ounces from 76.73 million. However, the value of those holdings fell to $323.5 billion from $350.1 billion due to the recent decline in gold prices, highlighting the impact of the market pullback despite continued central-bank demand.
- Fed's Daly: San Francisco Fed President Mary Daly said demand for artificial intelligence does not appear to be declining and may instead be increasing.
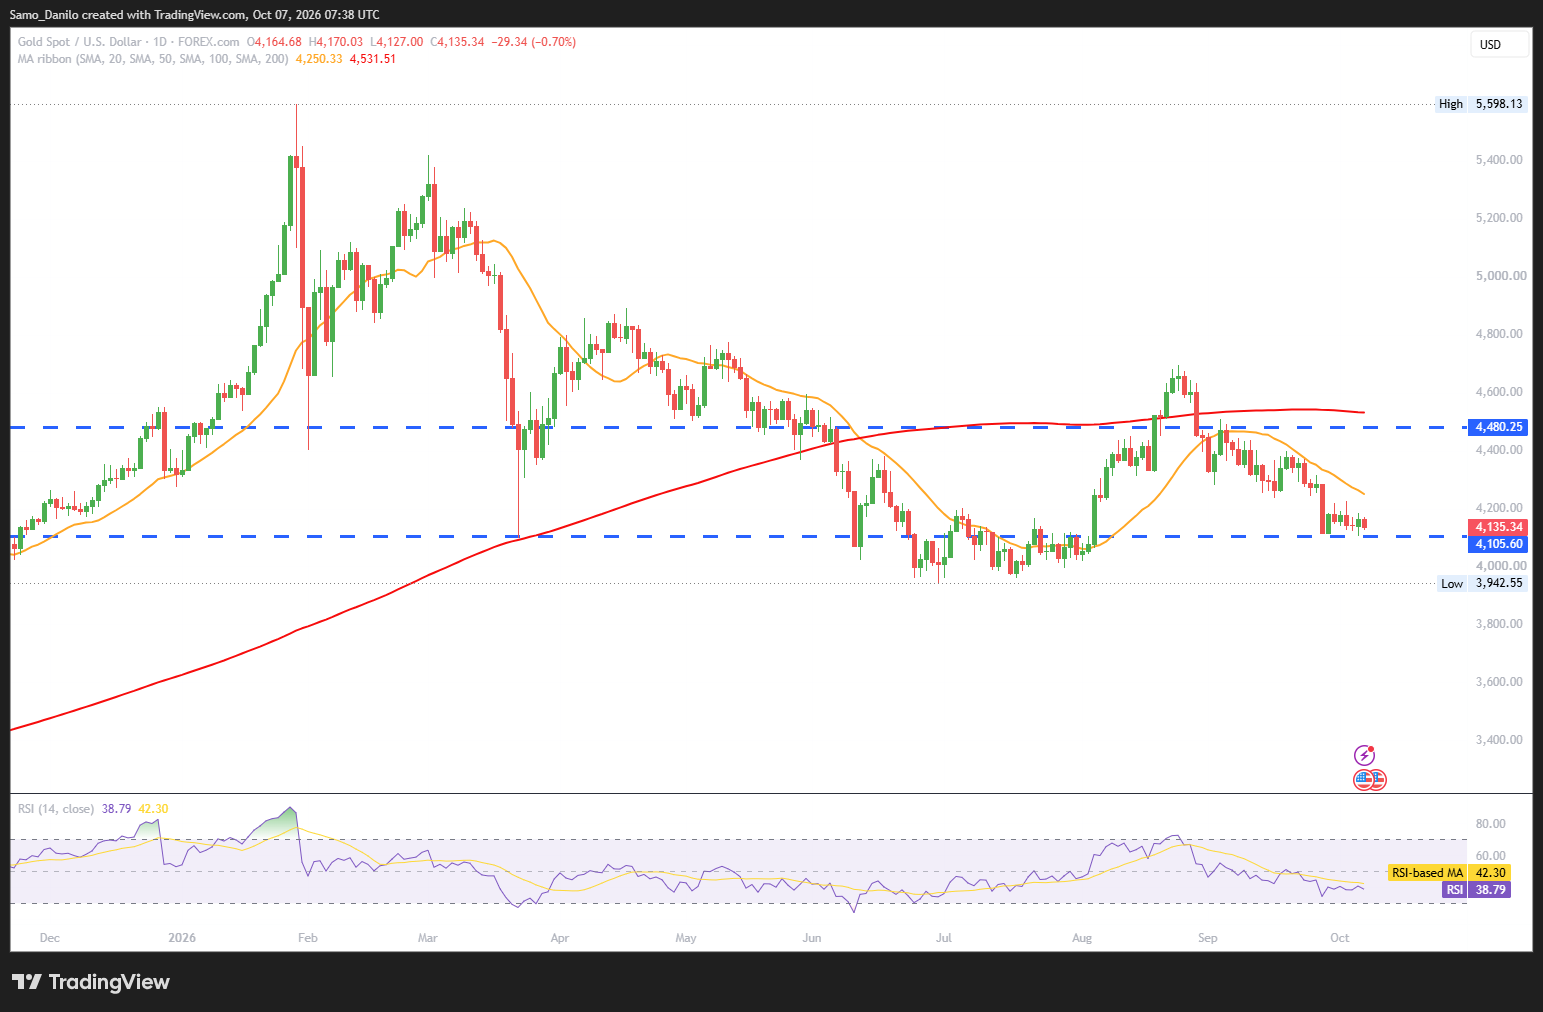
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains under pressure near the $4,100 area as elevated US inflation reinforces expectations for further Fed rate hikes, increasing the opportunity cost of holding gold. Continued PBOC purchases and geopolitical developments could provide some support, but the Fed’s expected policy path remains the key headwind for the precious metal.
CRUDE OIL
- Crude Oil Price: Crude oil lacks strong bullish conviction and trades around the $91.50 region during Wednesday’s Asian session, up approximately 0.30% on the day.
- Middle East: According to Reuters, Middle Eastern oil exports increased to around 19 million barrels per day in September, up approximately 4 million barrels per day from August.
- Gulf storm: A tropical depression has formed over the western Gulf of America and is expected to strengthen into a tropical storm on Wednesday and potentially a hurricane on Thursday.
- G7 oil: The IEA is expected to decide on the details of the G7’s planned diesel and oil stock release during its October 14–15 meeting, according to media reports citing sources.
- Crude inventories: The latest API data showed US crude oil inventories declined by 2.1 million barrels, compared with a 1.0 million-barrel increase in the previous reading. The unexpected drawdown could provide some short-term support to oil prices by pointing to tighter US crude balances.
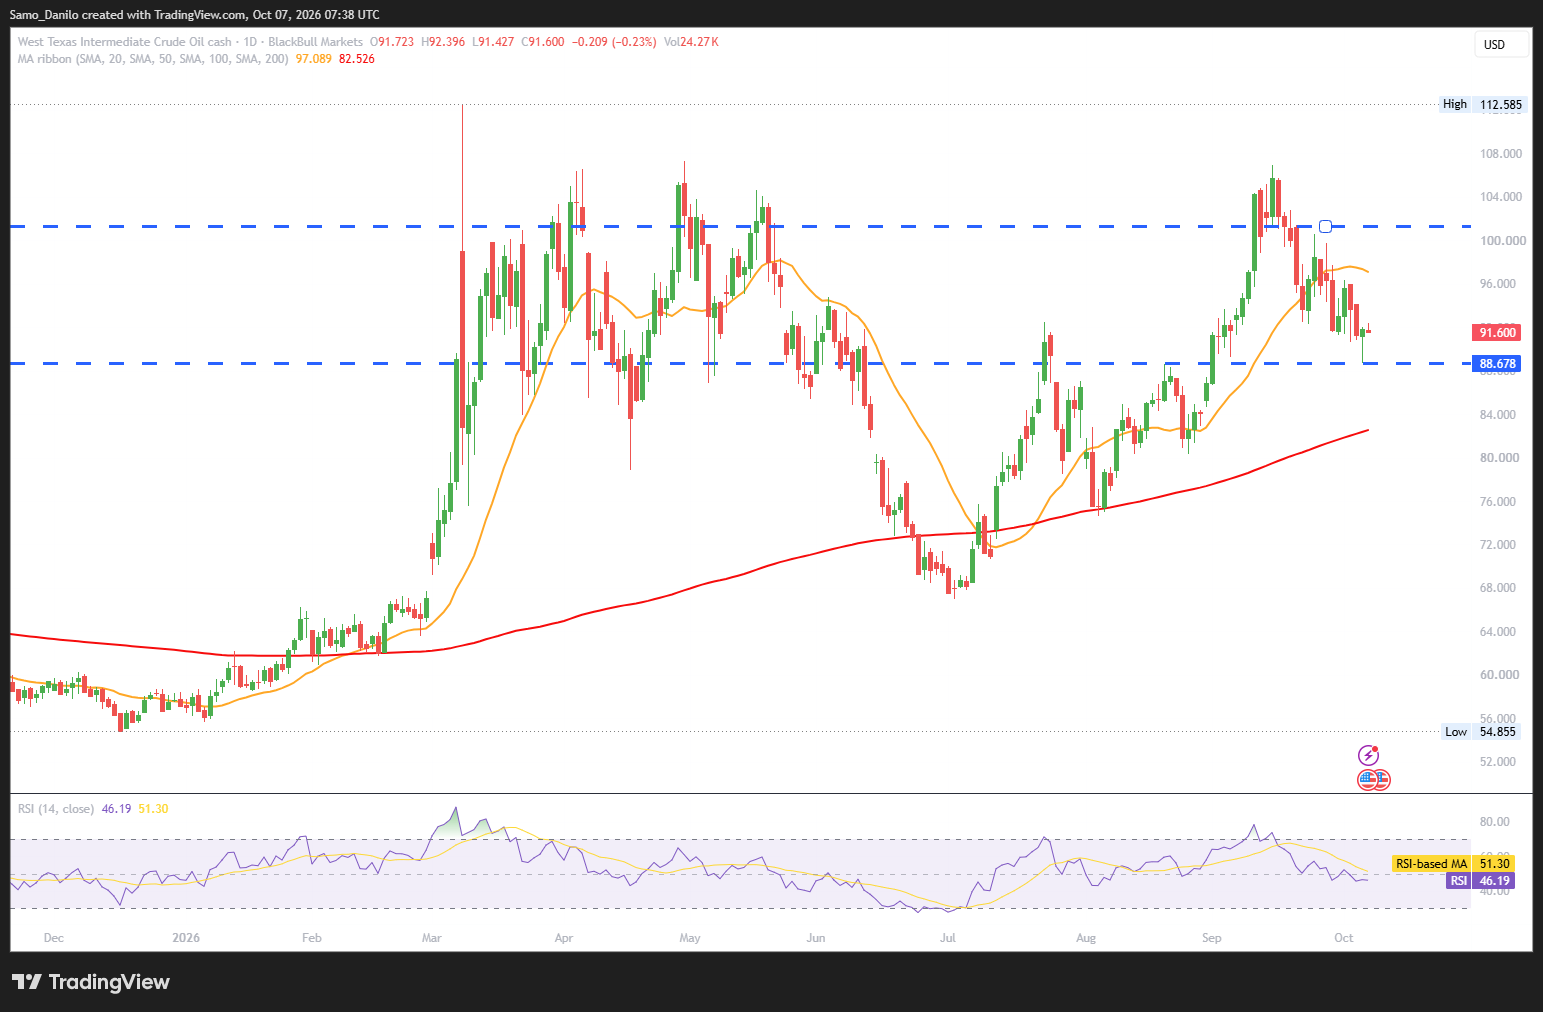
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Crude oil remains near $91.50 as recovering Middle Eastern exports and expectations for additional strategic stock releases limit bullish momentum. However, the decline in US inventories and the developing storm in the Gulf of America could provide near-term support, keeping supply disruptions and inventory data key drivers for the next move.
DAX
- DAX 40 Price: The DAX 40 trades lower around the 25,210-point level during Tuesday morning’s European session.
- Industrial production: German factory output increased 2.0% in September, largely reversing August’s 1.2% decline and significantly exceeding expectations for a 0.5% rise. On a year-on-year basis, industrial production increased 2.3% after contracting 1.6% in August, pointing to a notable improvement in Germany’s industrial sector.
- China trade: China’s Ministry of Commerce urged France and Germany not to support EU trade-protectionist measures, warning that economic decoupling would hurt both sides.
- EU Tax: Brussels is reportedly examining the possibility of introducing a tax targeting large technology companies, according to the Financial Times.
- Retail sales: Eurozone retail sales increased only 0.1% month-on-month in August, below the 0.2% forecast, while annual growth came in at 0.8% versus expectations of 1.0%. The weaker-than-expected figures suggest that consumer spending momentum remains relatively subdued across the euro area.
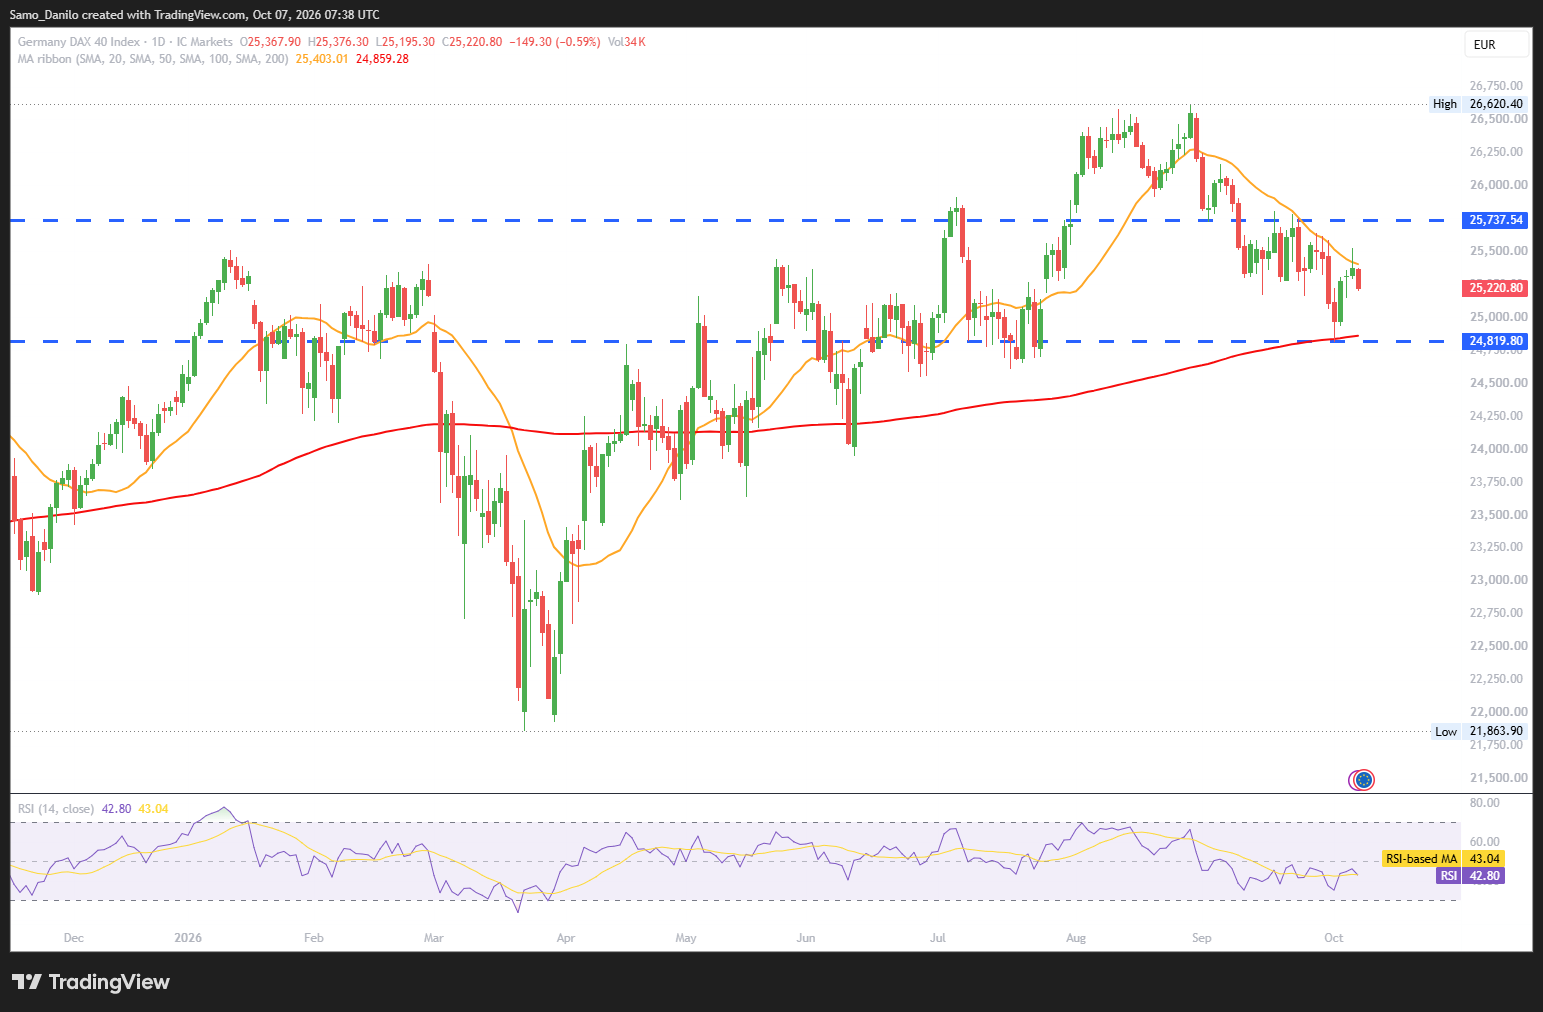
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 remains under pressure near 25,210 despite a strong rebound in German industrial production, which points to improved manufacturing momentum. However, weaker eurozone retail sales, ongoing EU-China trade tensions and potential new corporate taxes could weigh on sentiment and limit the index’s upside.