EURUSD
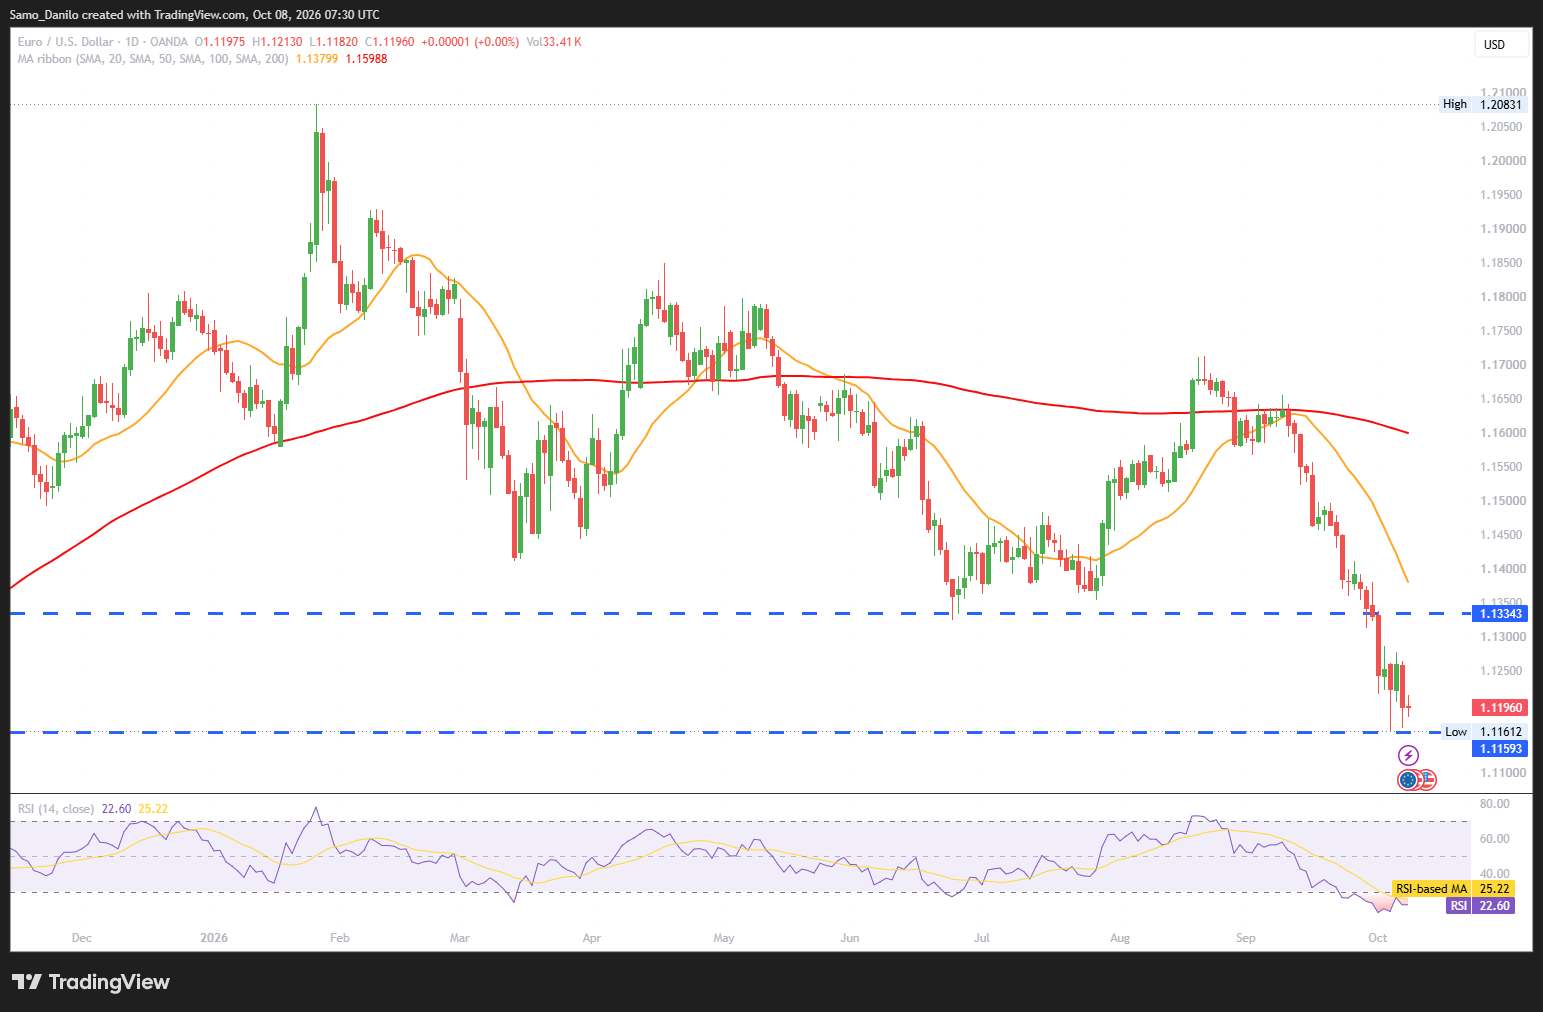
- EUR/USD Price: The EUR/USD pair loses ground toward the 1.1195 level during the early European trading session on Thursday.
- French debt: France’s borrowing costs have climbed amid the current global bond selloff, increasing concerns about the country’s fragile public finances.
- NBP rates: The National Bank of Poland kept its key interest rate unchanged at 3.75%, allowing policymakers to adopt a wait-and-see approach.
- ECB's Pereiera: ECB policymaker Pereira said current headline and core inflation levels are well below those seen during the 2022 energy shock.
- ECB minutes: The ECB will release the minutes of its September monetary-policy meeting, offering further insight into the Governing Council’s discussions. While President Lagarde’s emphasis on energy prices initially triggered a hawkish market reaction, subsequent comments from ECB policymakers have softened that tone.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains under pressure near 1.1195 as rising French borrowing costs and concerns over European fiscal stability weigh on the Euro. At the same time, more moderate ECB commentary and the upcoming September meeting minutes could reinforce expectations for a less hawkish policy stance, leaving the pair vulnerable to further downside.
GBPUSD
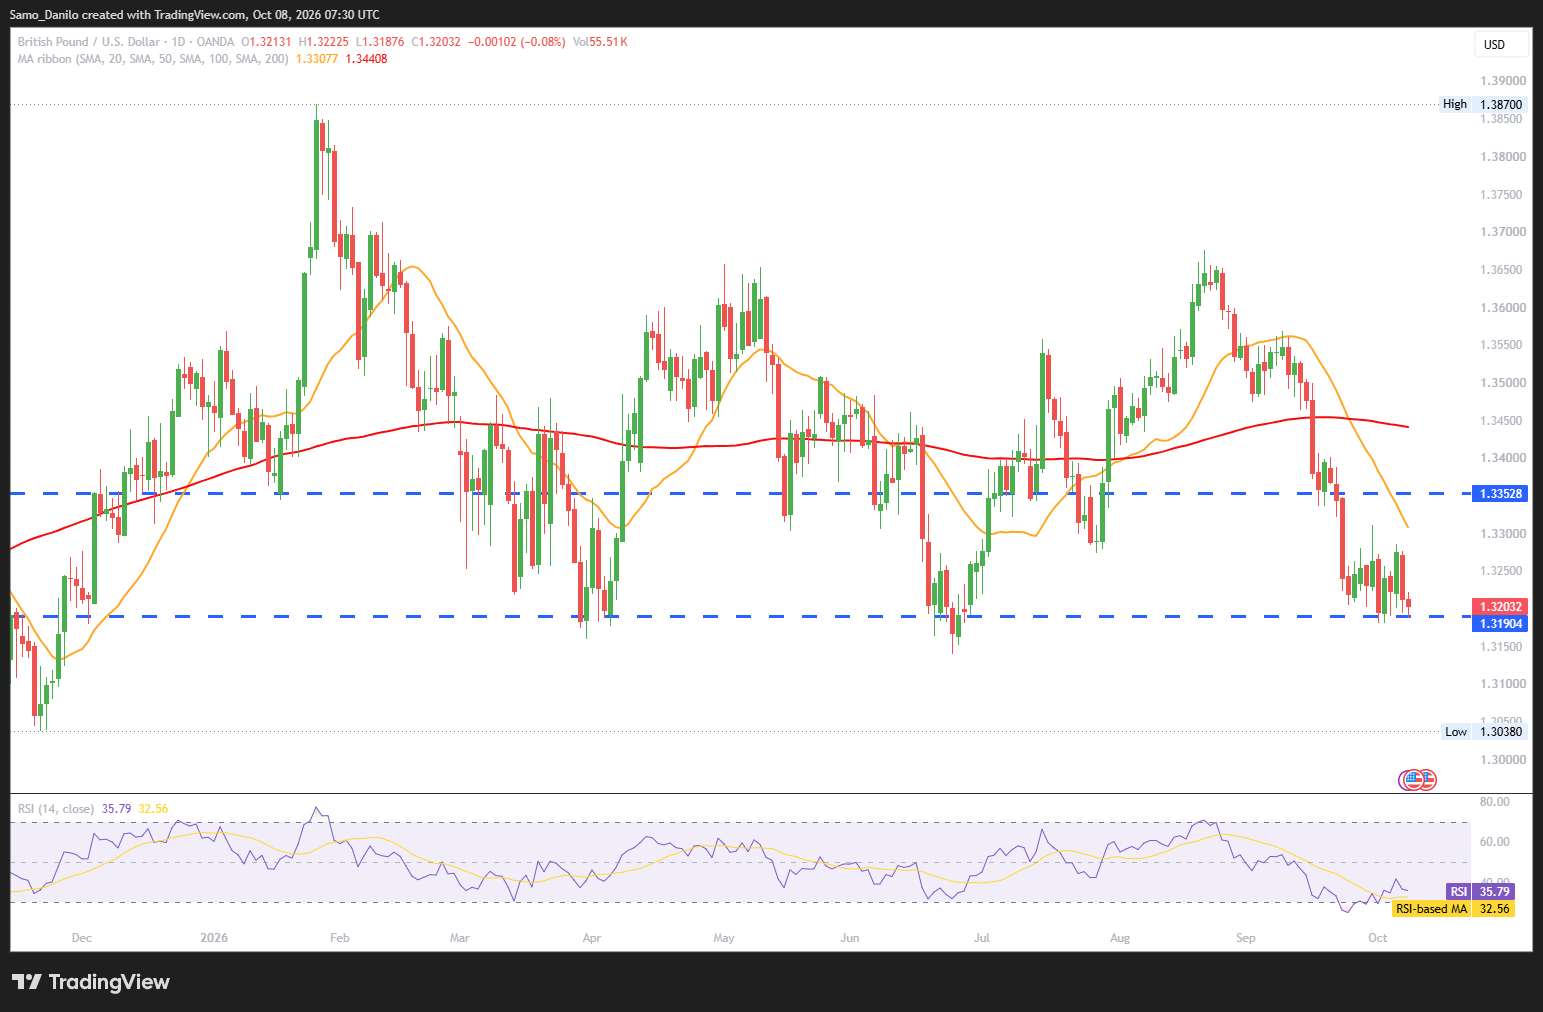
- GBP/USD Price: The GBP/USD pair struggles to gain meaningful traction around the 1.3200 level during Thursday’s European session.
- Fed minutes: Minutes from the Federal Reserve’s September meeting showed that policymakers were united in supporting the rate hike delivered at the meeting, while most officials considered another increase appropriate by year-end.
- UK Conservatives: Conservative Party leader Kemi Badenoch said the party has identified £70 billion in potential budget savings, with the plan potentially allowing for a £35 billion reduction in the deficit. She also ruled out cooperation with Reform and warned that Western economies are facing increasing fiscal constraints.
- House prices: The UK RICS House Price Balance fell to -32% in September, compared with expectations of -30%, indicating that price declines remained more widespread than increases.
- UK hiring: UK firms sought additional staff for the first time in two years, according to the latest REC/KPMG recruitment data.
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD remains under pressure near 1.3200, with the latest Fed minutes reinforcing expectations for another US rate hike and providing support to the Dollar. Weak UK house-price data contrasts with tentative signs of improvement in hiring, leaving the Pound vulnerable while markets continue to assess the relative monetary-policy outlook on both sides of the Atlantic.
XAUUSD
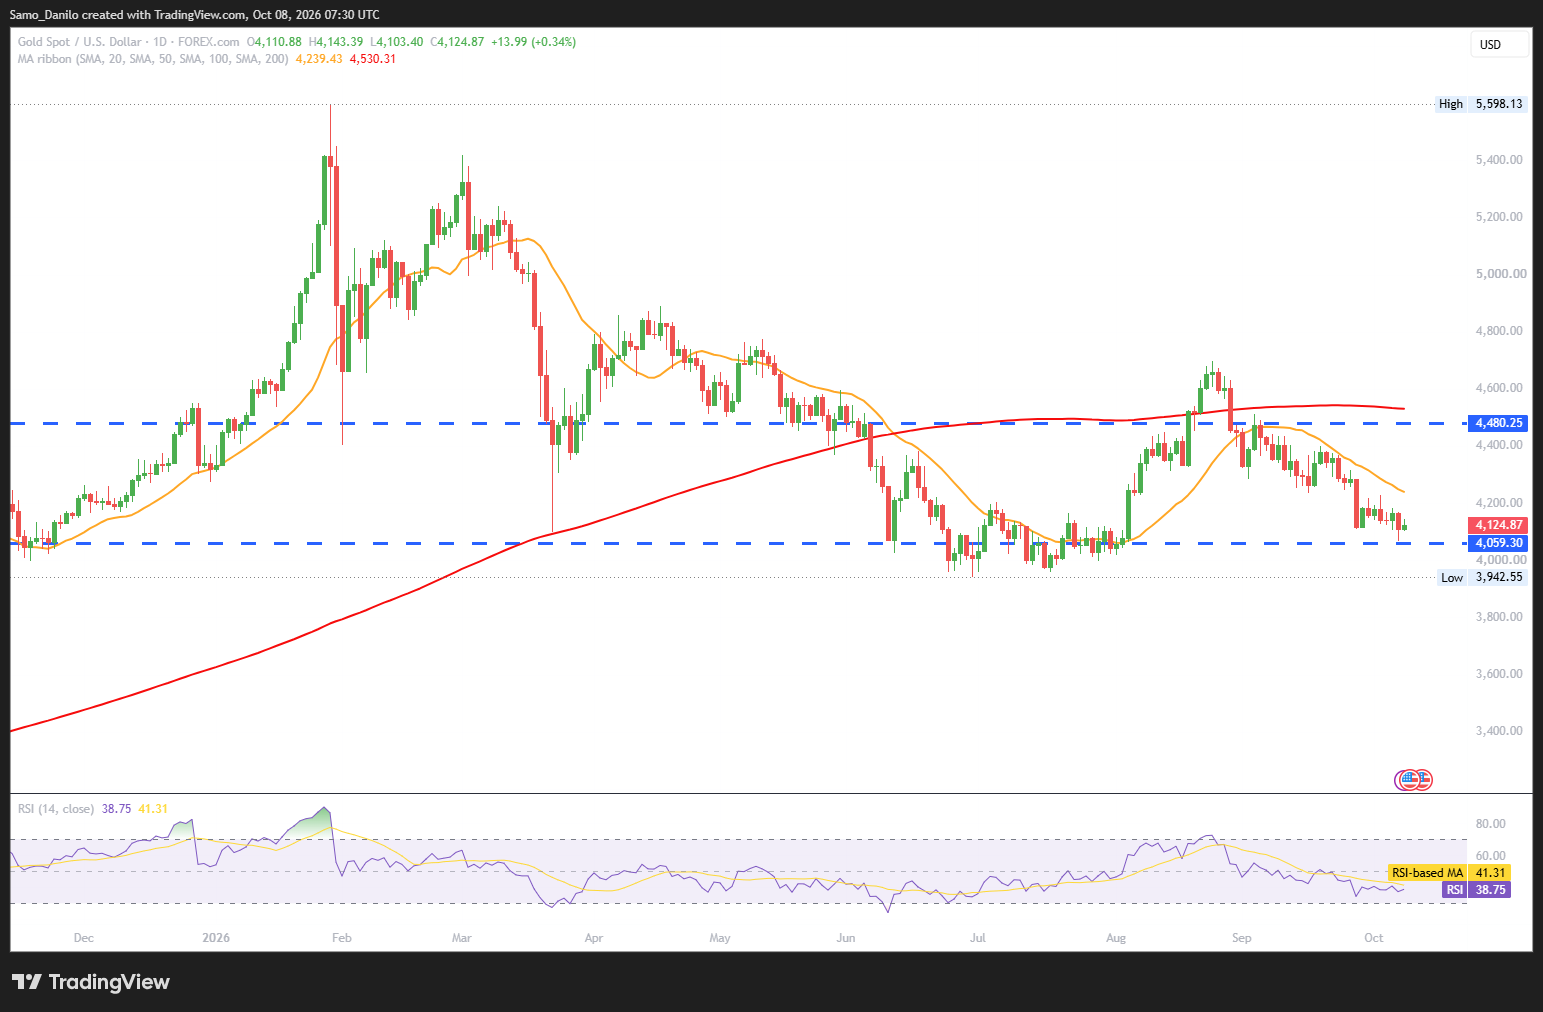
- XAU/USD Price: Gold (XAU/USD) struggles to capitalize on a modest intraday recovery and remains below the $4,150 level during Thursday’s European session.
- Fed rate: Markets are currently pricing an 81.7% probability that the Federal Reserve will leave rates unchanged at 3.75%-4.00% at its October 28 meeting, compared with an 18.3% probability of a 25-basis-point hike.
- Mortgage rates: Higher long-term mortgage rates, which have risen well above 7%, are beginning to weigh on US housing demand. Mortgage applications have fallen to their lowest level since February 2025, with both purchase and refinancing activity under pressure.
- Iran signals: Iranian President Masoud Pezeshkian said the country is in an “all-out war” and will continue to resist its opponents, while indicating that the range of Iranian weapons could be increased depending on battlefield conditions.
- Fed officials: Federal Reserve Governor Christopher Waller and Minneapolis Fed President Neel Kashkari are scheduled to speak and could provide fresh clues about the outlook for interest rates.
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Falling | | |
Closing statement: XAU/USD remains under pressure below $4,150 as elevated Treasury yields and expectations for further Fed tightening weigh on the non-yielding asset. However, the high probability of an October rate hold and continued geopolitical tensions could provide support, while comments from Waller and Kashkari may determine whether gold can stabilize or remains vulnerable to further downside.
CRUDE OIL
- Crude Oil Price: Crude oil maintains a bullish tone and trades around the $93.10 region during the European session.
- Diesel prices: European diesel prices jumped sharply after IEA members agreed to accelerate the release of oil stocks announced in March. However, the IEA clarified that the accelerated release will remain within the 400 million barrels already committed, limiting expectations for additional strategic supply.
- Strait of Hormuz: Traffic through the Strait of Hormuz fell to its lowest level in more than two months, with Kpler reporting only seven commodity vessels transiting on Tuesday.
- Hurricane threat: The Isaias tropical depression, located near 22.9°N and 91.9°W, continued strengthening while moving northeast at around 9 mph and subsequently became a hurricane as expected.
- Gulf production: Ahead of the hurricane’s confirmation, Shell announced the evacuation of all personnel and the shutdown of production at its Mars, Olympus, Ursa, Vito and Appomattox assets. Chevron also initiated shut-in procedures at four of its nine company-operated Gulf of America facilities, highlighting the immediate impact of the storm threat on US crude production.
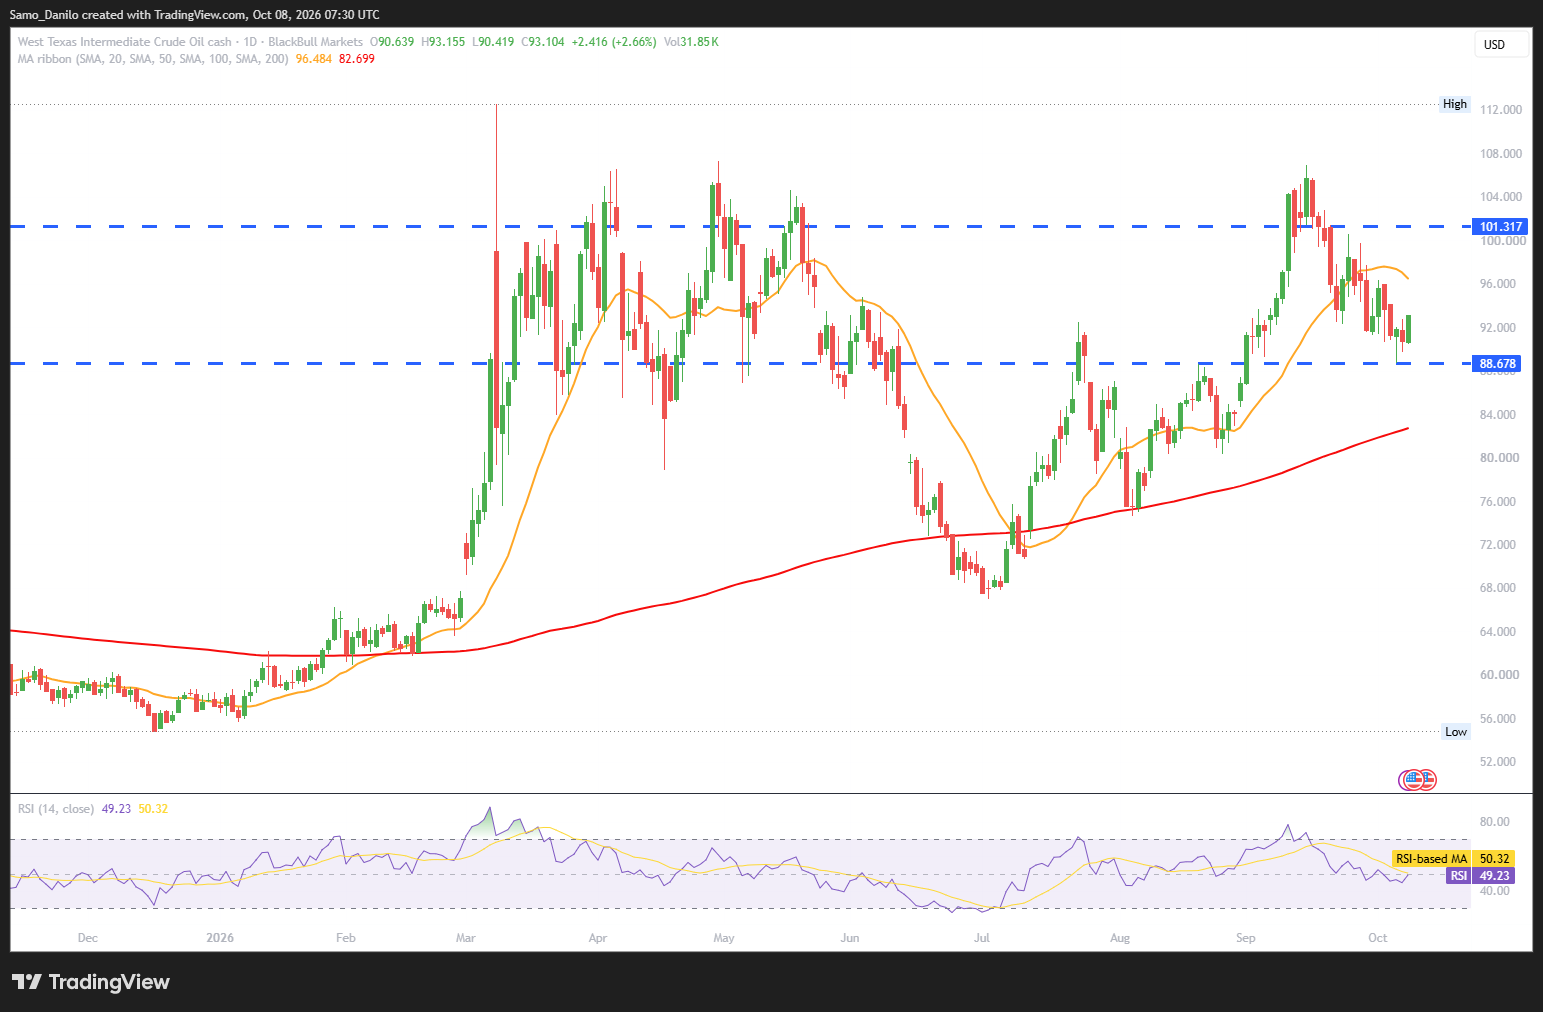
| SMA (20) | Rising |  | |
| RSI (14) | Slightly Rising | |
|
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Crude oil remains firmly supported near $93.10 as disruptions around the Strait of Hormuz and the shutdown of US Gulf production increase concerns over available supply. Accelerated IEA stock releases could limit the upside, but ongoing tanker attacks and hurricane-related disruptions keep the near-term risk tilted toward higher prices.
DAX
- DAX 40 Price: The DAX 40 trades lower around the 24,875-point level during Friday morning’s European session. The index has reached its 200-day moving average and bounced slightly, making this technical level an important area for near-term support.
- Security talks: UK Prime Minister Burnham and German Chancellor Friedrich Merz are scheduled to hold security talks in Berlin.
- Bayer news: US health authorities have accepted Bayer’s supplemental application for finerenone, marketed as Kerendia. The application seeks a new indication for treating chronic kidney disease in adults without diabetes, potentially expanding the medicine’s addressable patient population.
- Daimler sales: Daimler Truck reported a 26% increase in third-quarter vehicle sales to 91,260 units, supported by a 51% surge in North American sales. However, battery-electric truck and bus sales declined by 28%, highlighting continued differences between conventional and electric commercial-vehicle demand.
- Data ahead: Traders are turning their attention to the latest US Weekly Initial Jobless Claims report.
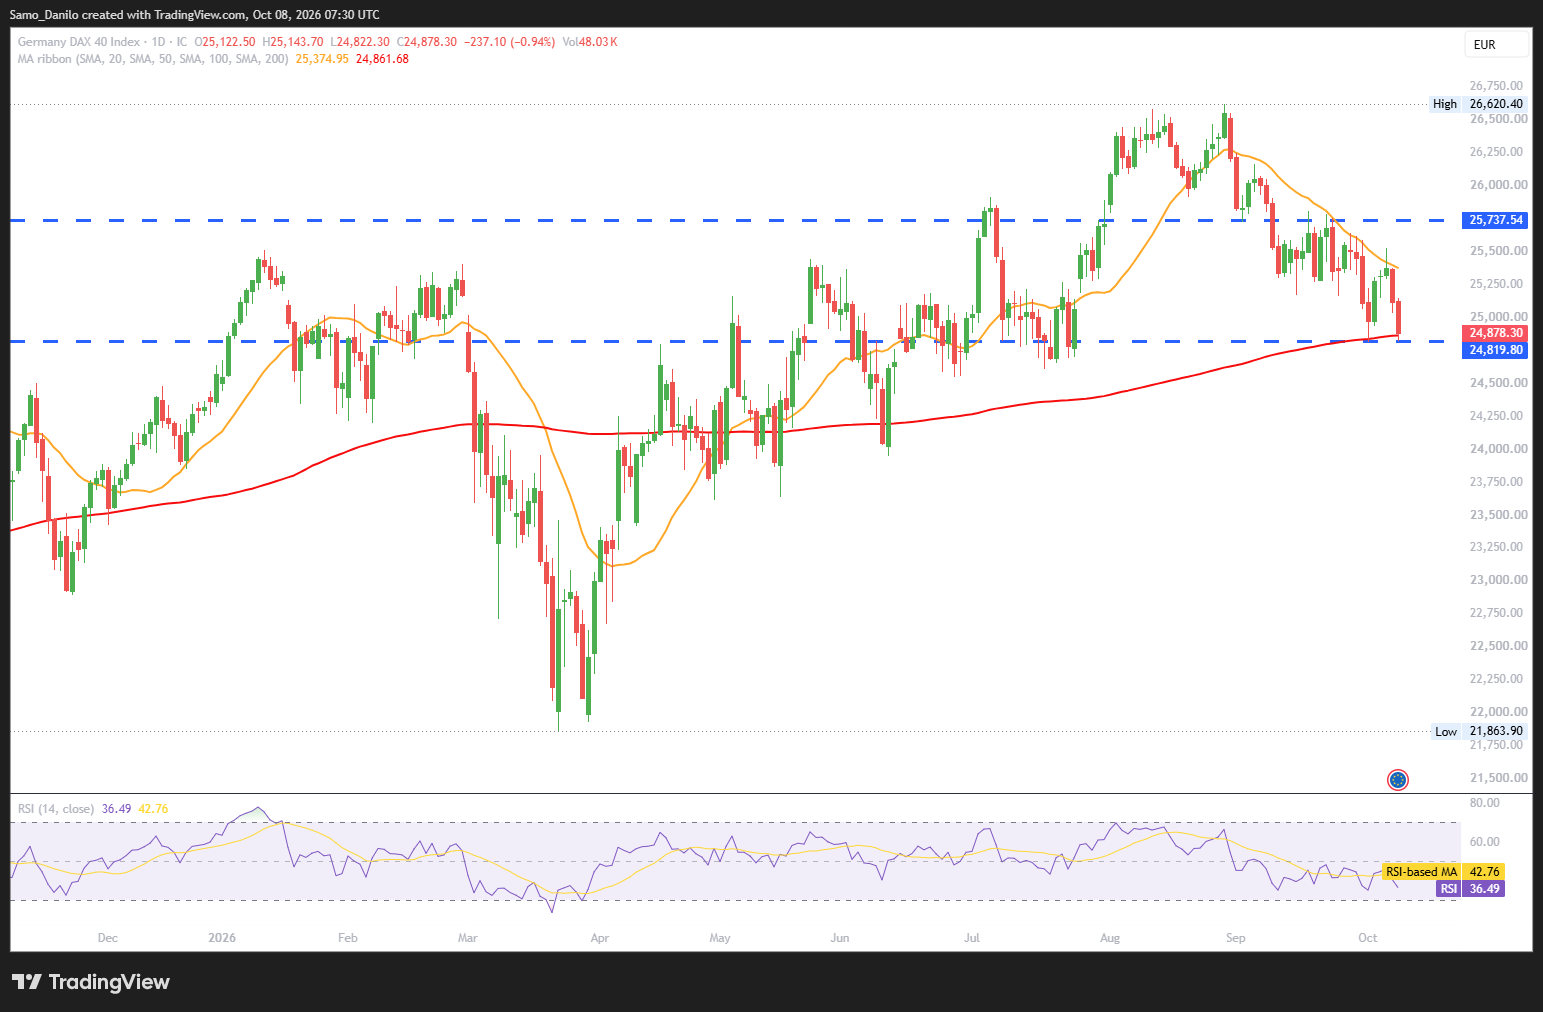
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 remains under pressure near 24,875 after testing its 200-day moving average, although the initial bounce suggests some buying interest at this level. Corporate developments at Bayer and Daimler Truck provide mixed signals, while US jobless claims and broader geopolitical developments could determine whether the index stabilizes or extends its decline.