EURUSD
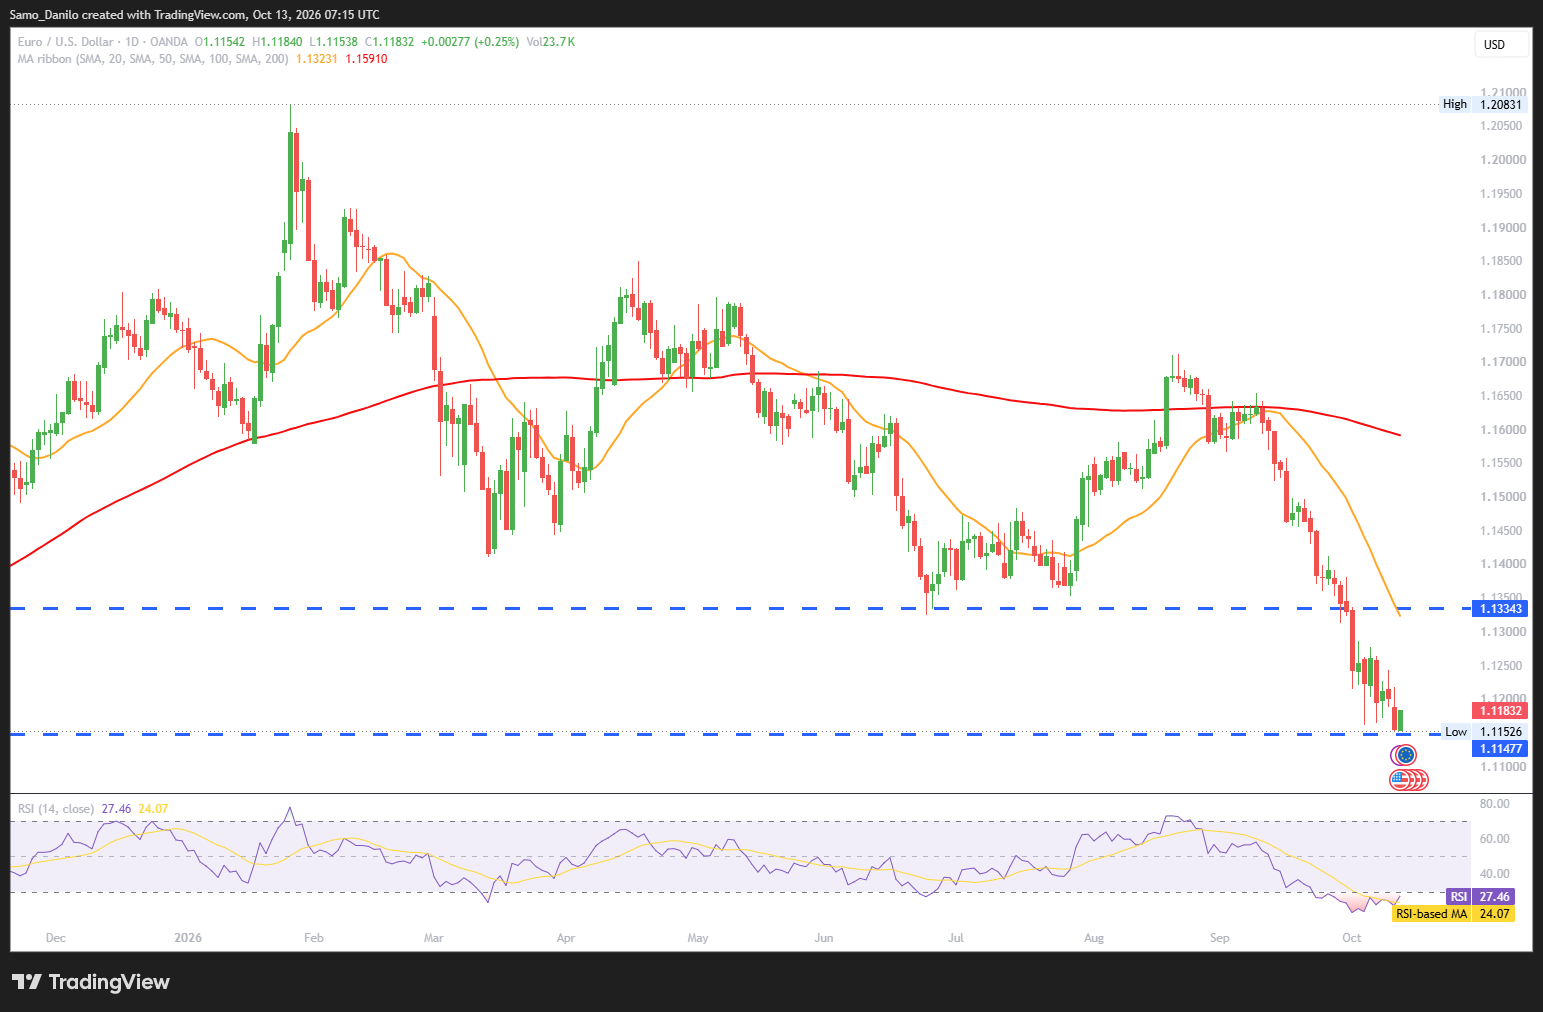
- EUR/USD Price: The EUR/USD pair trades in positive territory near 1.1175 during the early European session on Tuesday.
- French budget: Analysts at ING note that the French government’s latest budget proposal, which includes €43 billion in new savings, is due to be debated in parliament this week.
- Fed’s Hammack: Cleveland Fed President Beth Hammack said on Monday that tighter monetary policy may be necessary to contain inflation and prevent an inflationary mindset from becoming entrenched in the economy.
- Danish inflation: Denmark’s annual inflation rate increased to 2.2% in September, up from 2.0% in August and above expectations. Higher prices for energy, including electricity, natural gas and fuel, contributed to the increase.
- Data ahead: Traders will monitor the US National Federation of Independent Business (NFIB) survey for fresh insights into small-business sentiment.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD is holding near 1.1175, but its upside may be constrained by concerns over France’s fiscal outlook and the possibility of further Fed tightening. The French budget debate and US NFIB survey are the key near-term catalysts, with signs of persistent inflation or tighter monetary policy potentially supporting the Dollar, while easing US policy expectations could help the euro extend its gains.
GBPUSD
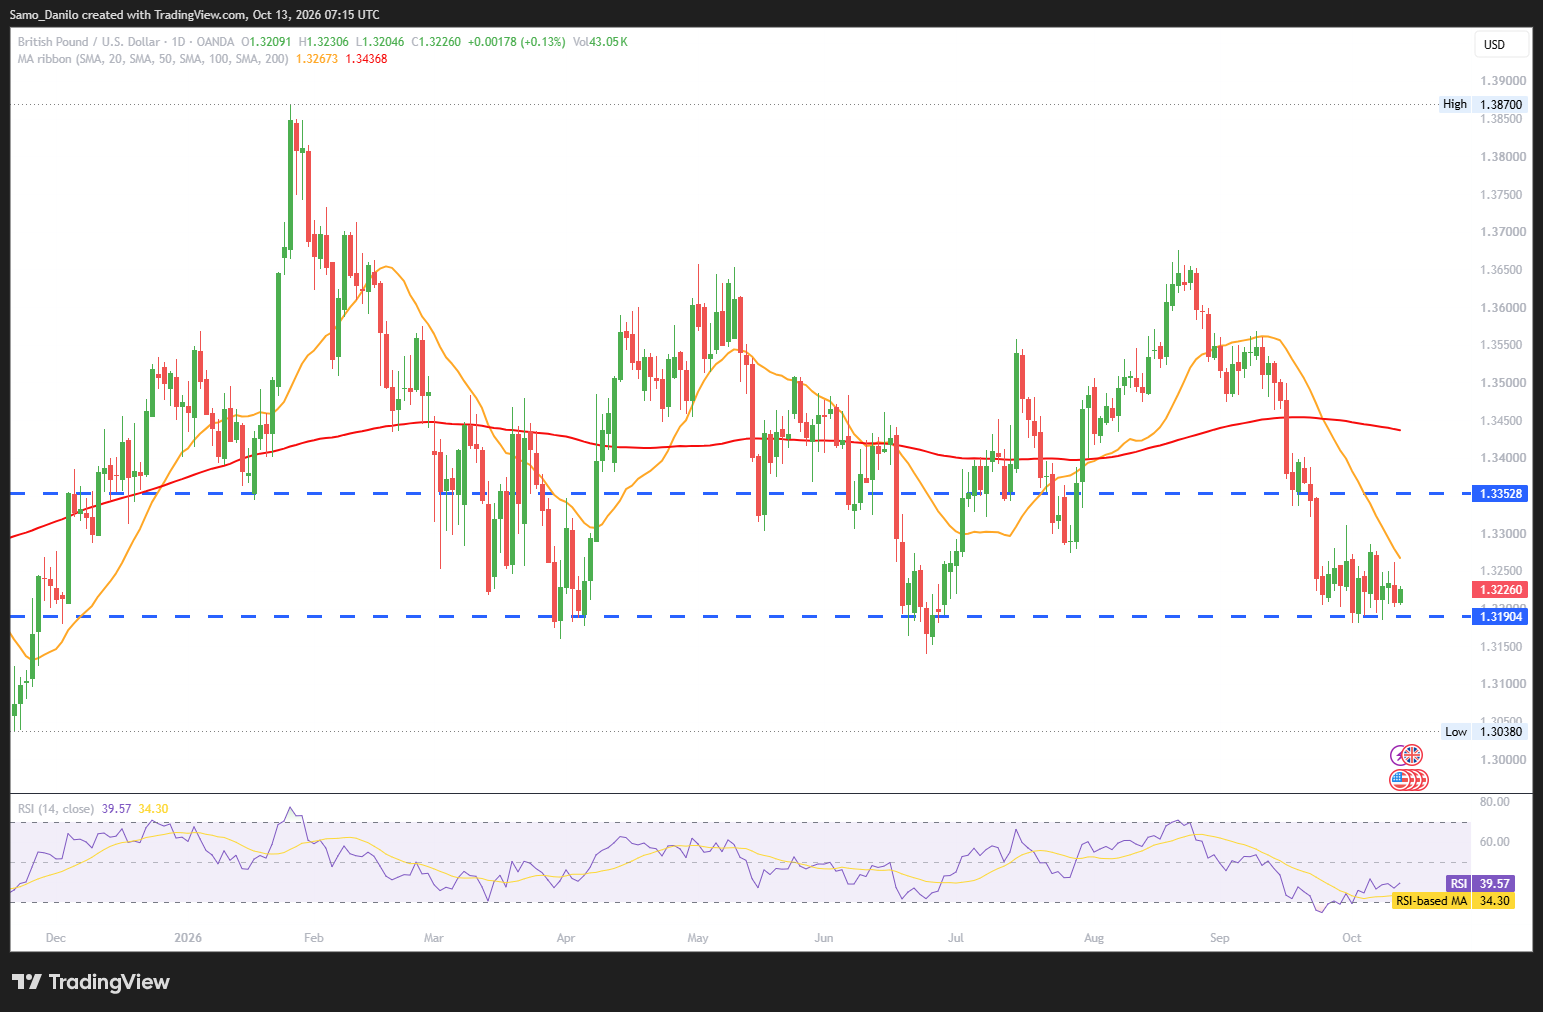
- GBP/USD Price: The GBP/USD pair attracts dip-buyers around the 1.3200 level during Tuesday’s Asian session, halting the previous day’s decline following rejection at the 100-period Simple Moving Average (SMA) on the four-hour chart.
- Retail sales: The British Pound gains ground following the better-than-expected release of the British Retail Consortium (BRC) Like-for-Like Retail Sales data.
- BoE's Greene: Bank of England policymaker Megan Greene said she is concerned that second-round inflation effects could become entrenched if the central bank fails to act promptly.
- BoE’s Mann: Hawkish Bank of England policymaker Catherine Mann warned that conditions are in place for a potential wage-price spiral, in which rising wages and prices reinforce one another.
- Rishi Sunak: Former UK Prime Minister Rishi Sunak highlighted India’s significant opportunities in pharmaceutical supply chains at the NE Economy Forum. While the comments underline potential opportunities for international business cooperation, their direct impact on GBP/USD is likely to be limited unless they lead to developments with broader implications for UK trade or investment.
| SMA (20) | Falling | | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD has found support near 1.3200, with stronger-than-expected UK retail sales and hawkish comments from BoE policymakers providing a positive backdrop for sterling. However, a sustained recovery will depend on whether buyers can maintain momentum around this technical level, while broader US Dollar movements may influence the pair’s next direction.
XAUUSD
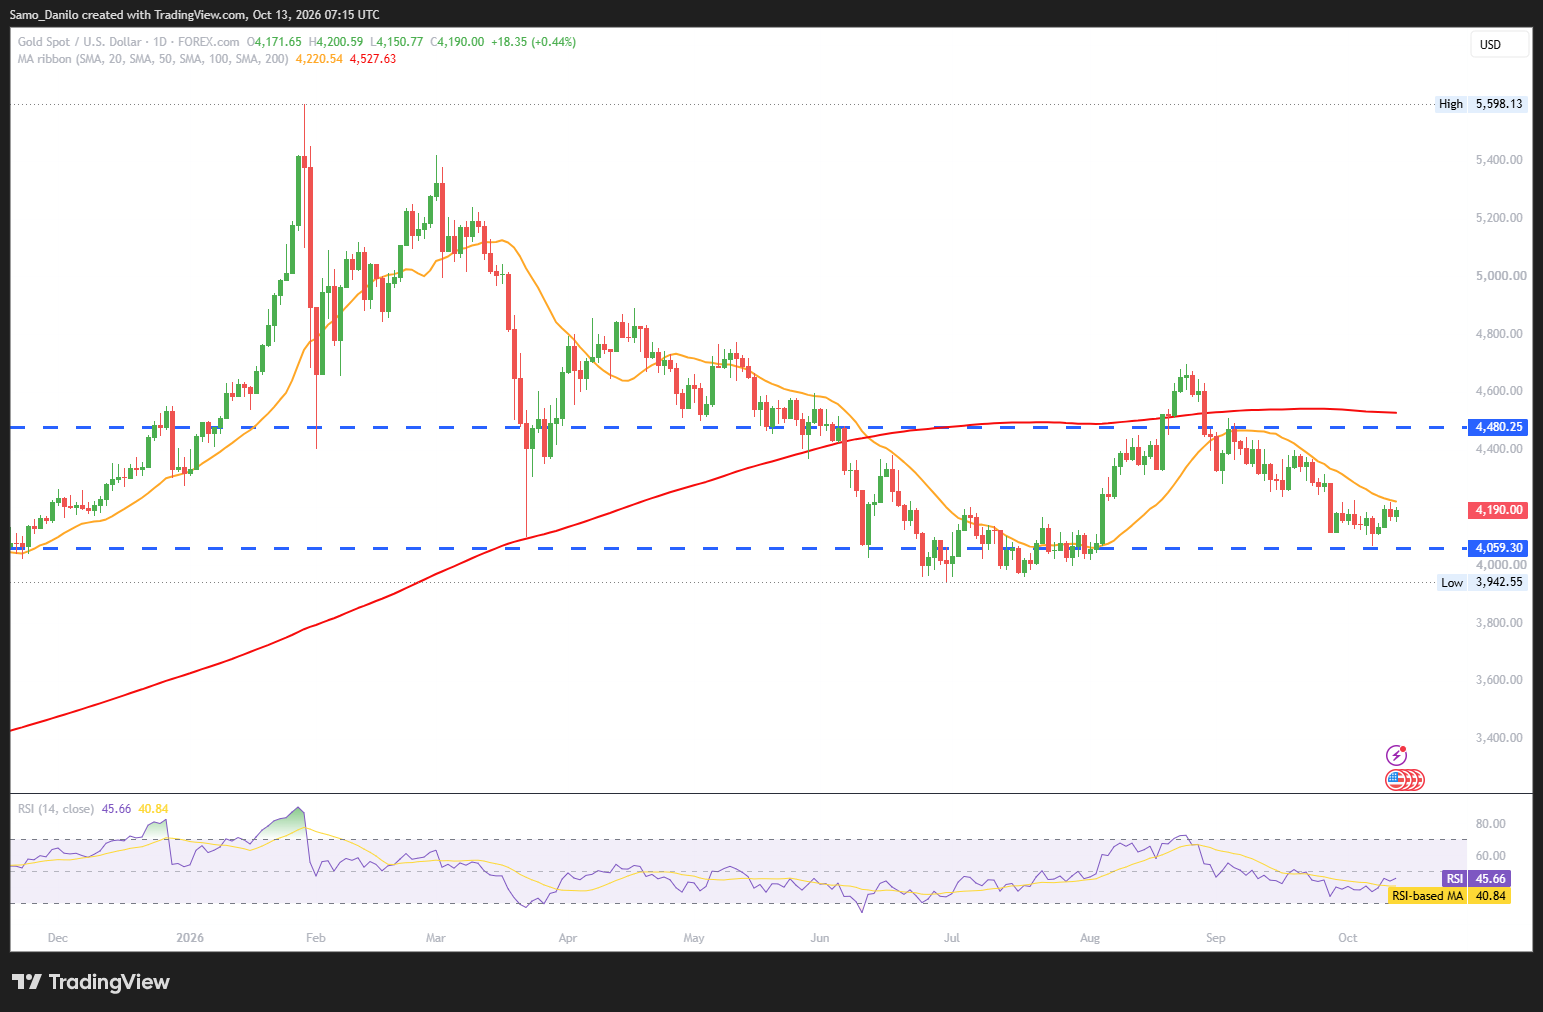
- XAU/USD Price: Gold (XAU/USD) struggles to extend its recent advance and remains capped below the key $4,200 psychological level heading into Tuesday’s European session.
- Fed rate: According to the CME FedWatch Tool, traders assign an 80.6% probability to interest rates remaining unchanged at the Fed’s next meeting, while the probability of a rate increase in December stands at nearly 84.7%.
- Plague risk: Reports indicate that Chinese authorities have warned of a potential plague risk near the Russian border, with a border city reportedly alerting travellers arriving from Russia.
- Chinese data: China is scheduled to release trade and inflation data overnight, with exports expected to remain relatively strong. External shipments have been a significant driver of growth, with export values rising by around 25% year-on-year in recent months, supported by chips, electronics and automobiles; stronger figures could improve sentiment toward the global economic outlook, while weaker data could increase demand for safe-haven assets.
- Data ahead: Markets will focus on Wednesday’s US Consumer Price Index (CPI) report, followed by Thursday’s Producer Price Index (PPI) and Retail Sales data.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: XAU/USD remains under pressure below $4,200 as expectations of a possible December Fed rate hike create a headwind for the precious metal. Chinese economic data and geopolitical or public-health concerns could influence safe-haven demand, but the key near-term catalysts are the US CPI, PPI and Retail Sales releases, which may determine whether gold breaks above $4,200 or resumes its decline.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, attracts fresh sellers during Tuesday’s Asian session, ending a three-day winning streak after reaching a two-week high the previous day.
- Ukraine signals: Ukrainian President Volodymyr Zelenskyy said Kyiv would continue striking Russian targets as Moscow maintains attacks on Ukraine’s energy infrastructure.
- Houthi attacks: Riyadh airport is reportedly expected to remain closed until Saturday following further Houthi attacks, with several airlines cancelling services to the Saudi capital.
- IMF outlook: The International Monetary Fund has raised its forecast for global GDP growth in 2026 from 3.0% to 3.1%, signalling a slightly more positive outlook for global economic activity. However, the IMF has lowered its growth forecasts for China in both 2026 and 2027, creating mixed implications for oil demand given China’s importance as a major energy consumer.
- Kuwait prices: Kuwait has reportedly reduced its official crude oil selling prices for Asian buyers for November, according to a pricing document.
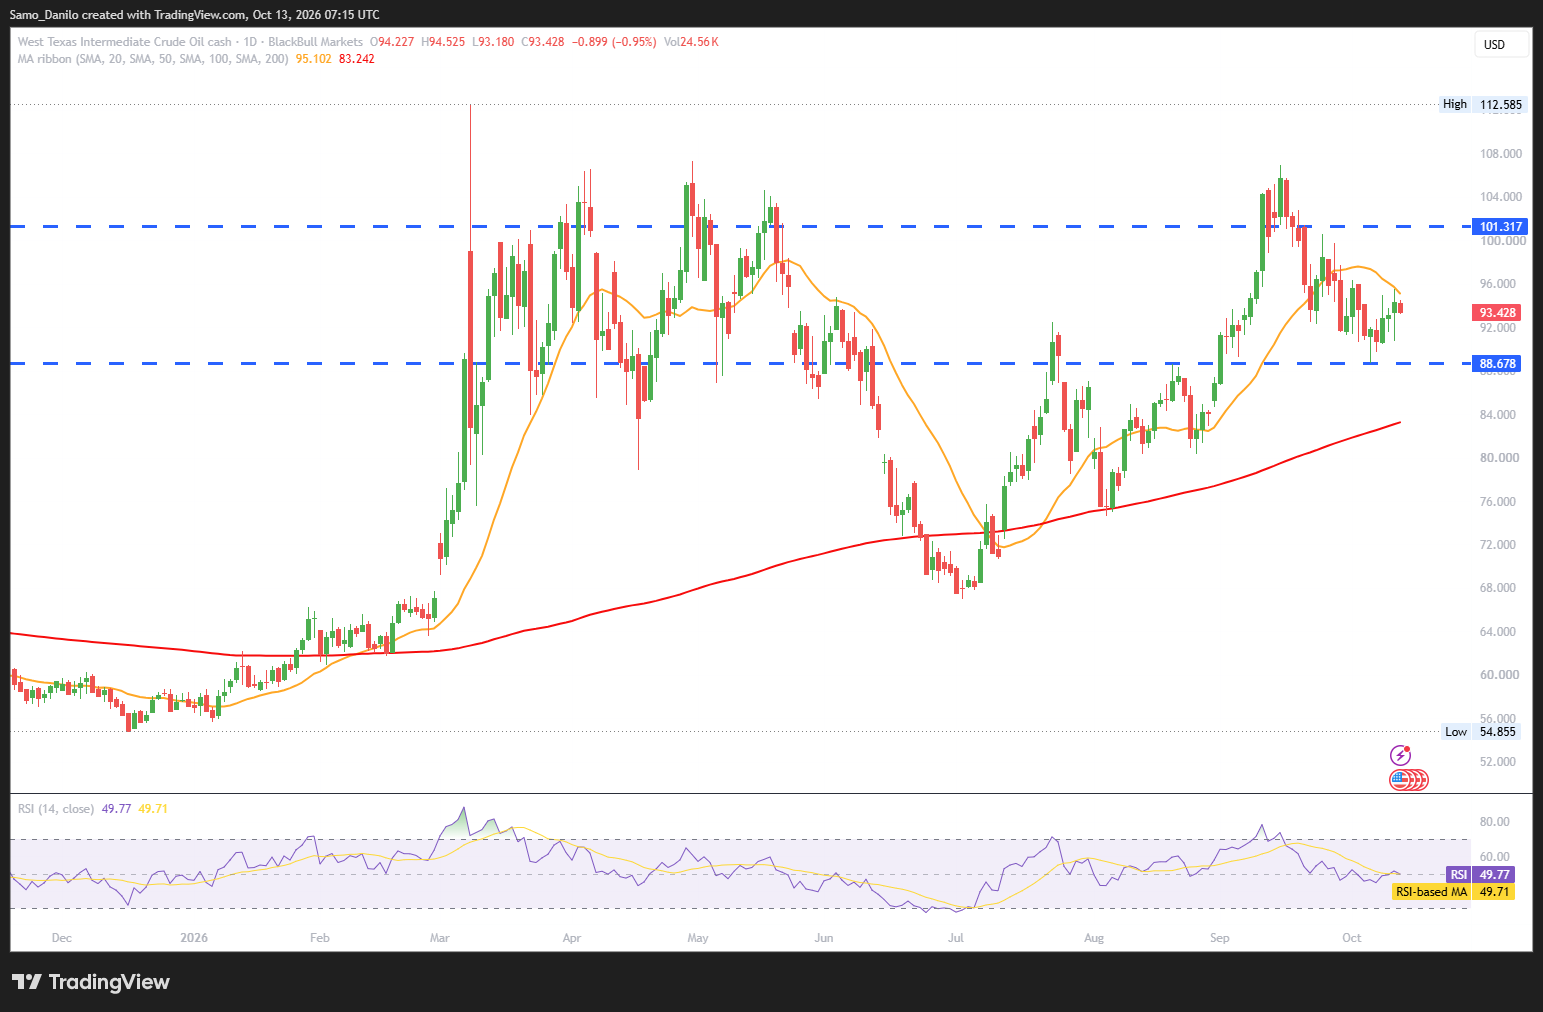
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: WTI has retreated toward $93.30 after reaching a two-week high, suggesting some profit-taking following its recent rally. Continued Ukrainian strikes and Middle East tensions could support prices through supply-risk concerns, while Kuwait’s price cuts and a weaker Chinese growth outlook may weigh on demand expectations. Traders will assess whether geopolitical risks are sufficient to offset these bearish pressures.
DAX
- DAX 40 Price: The DAX 40 trades higher around 25,330 points on Tuesday morning after finding resistance at its 100-day moving average on the daily chart.
- Merz's statement: German Chancellor Friedrich Merz stated that a diesel supply deal with Russia is out of the question for Germany and called for sanctions to be tightened.
- EU limitations: An EU Commission official said the European Union has agreed to limit Chinese hybrid-car imports to 350,000 vehicles annually, with the limit increasing by 6% per year. Compared with approximately 302,000 vehicles imported in 2025, the measure could affect competition in the European automotive market, with implications for German manufacturers seeking to protect their market share against Chinese rivals.
- ECB’s Stournaras: Bank of Greece Governor Yannis Stournaras indicated that the European Central Bank may continue raising interest rates gradually.
- Zelenskyy signals: Ukrainian President Volodymyr Zelenskyy said Ukraine was ready to take meaningful decisions and de-escalatory steps to bring the war closer to an end. However, he added that there was no indication Russia was complying with the conditions outlined by the US President, leaving the outlook for a diplomatic breakthrough uncertain and geopolitical risks elevated.
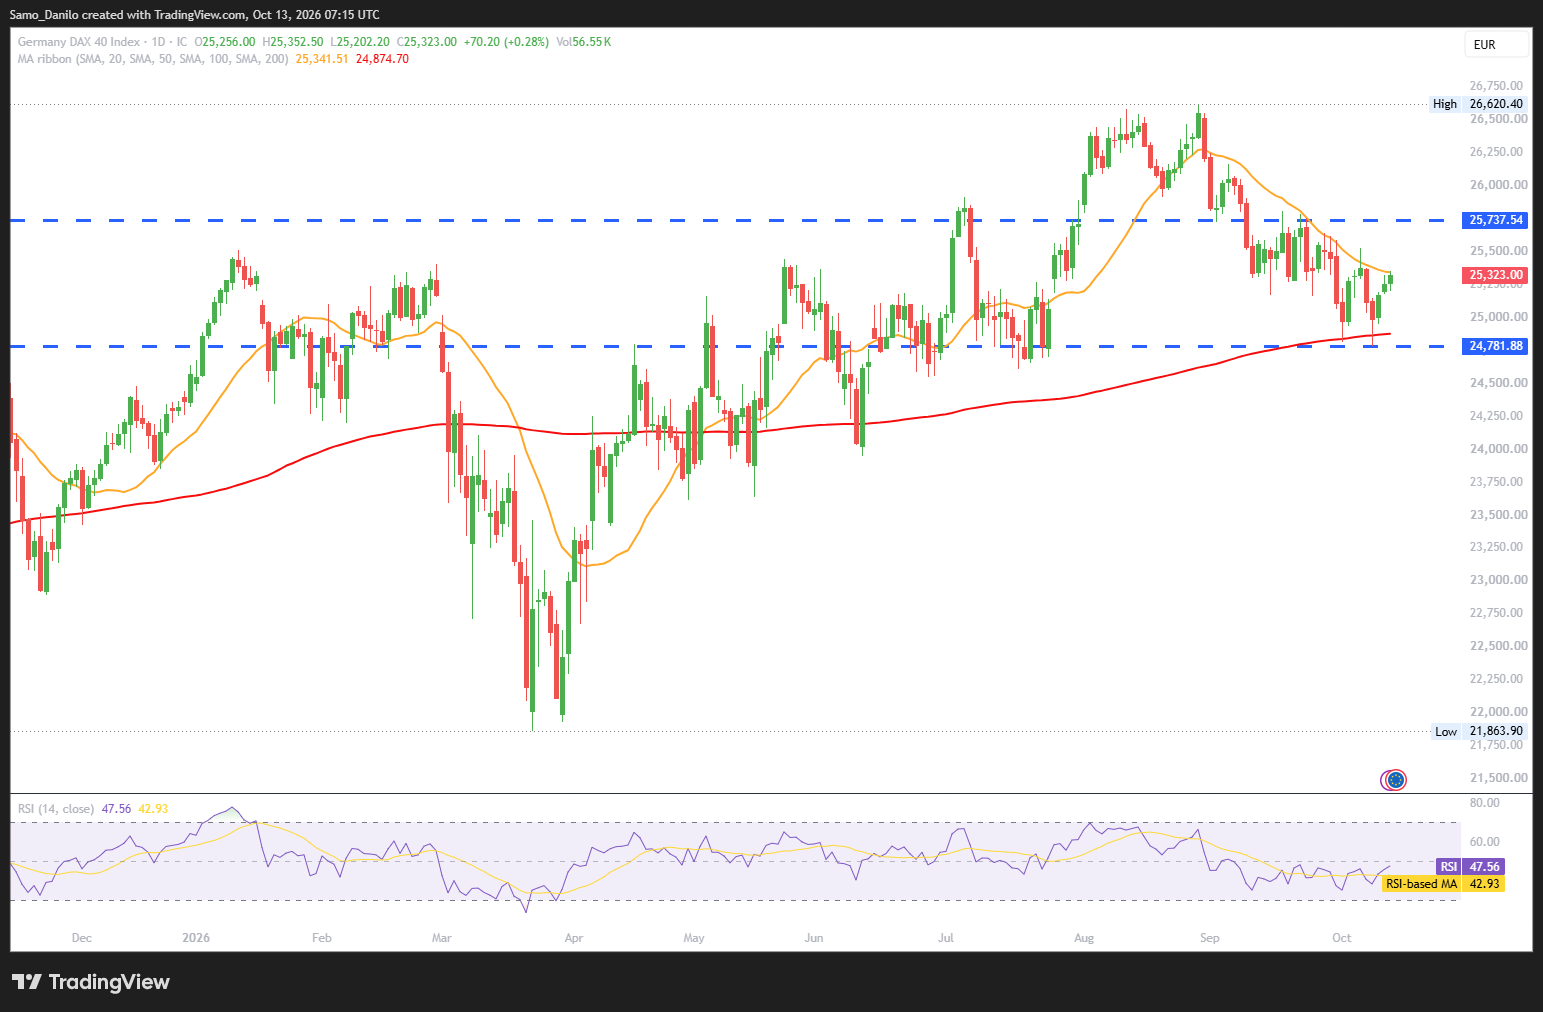
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Falling | | |
Closing statement: The DAX 40 is recovering around 25,330 after finding support at its 100-day moving average, providing a positive technical signal. However, uncertainty over EU-China automotive trade, the prospect of gradual ECB rate increases and persistent geopolitical tensions could limit further gains, while progress toward de-escalation in Ukraine may improve investor sentiment.