EURUSD
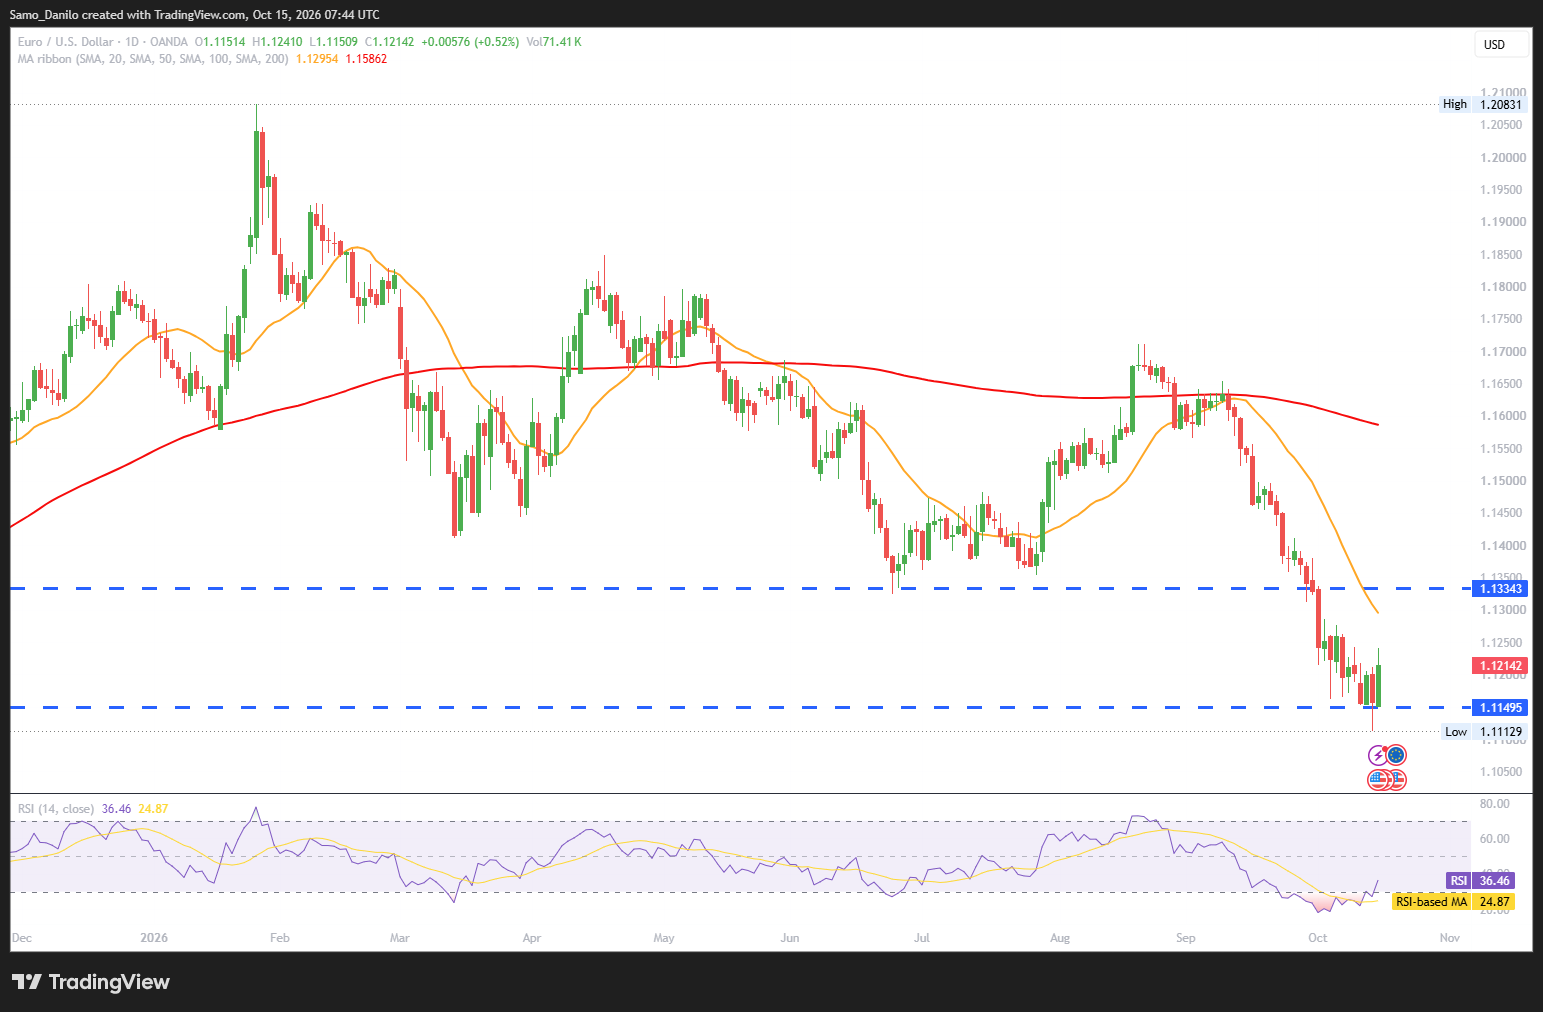
- EUR/USD Price: The euro is up 0.5% against the US dollar, trading around 1.1220 during Thursday’s early European session after extending Wednesday’s recovery.
- French budget: France’s rising public debt remains a source of concern for the euro, with 10-year French government bond yields holding around 4.86%, close to the decades-high level of 5% recorded earlier this month.
- US CPI: The US CPI data showed on Wednesday that the headline inflation accelerated at a faster-than-expected pace to 3.7% Year-on-Year (YoY) from 3.4% in August.
- Beige Book: The Federal Reserve’s Beige Book reported that two of its 12 districts experienced moderate economic growth, while expectations across districts generally pointed to slight growth ahead.
- ECB’s Simkus: ECB policymaker Gediminas Simkus of Lithuania said he does not currently see a role for ECB intervention in France.
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD has gained ground toward 1.1220, supported by its ongoing recovery and signs of modest US economic growth. However, rising French borrowing costs create a challenging backdrop for the euro, while the ECB’s reluctance to intervene in France may leave fiscal concerns unresolved. Further upside will depend on whether the euro can sustain its recovery despite these risks and how incoming economic developments influence expectations for ECB and Fed policy.
GBPUSD
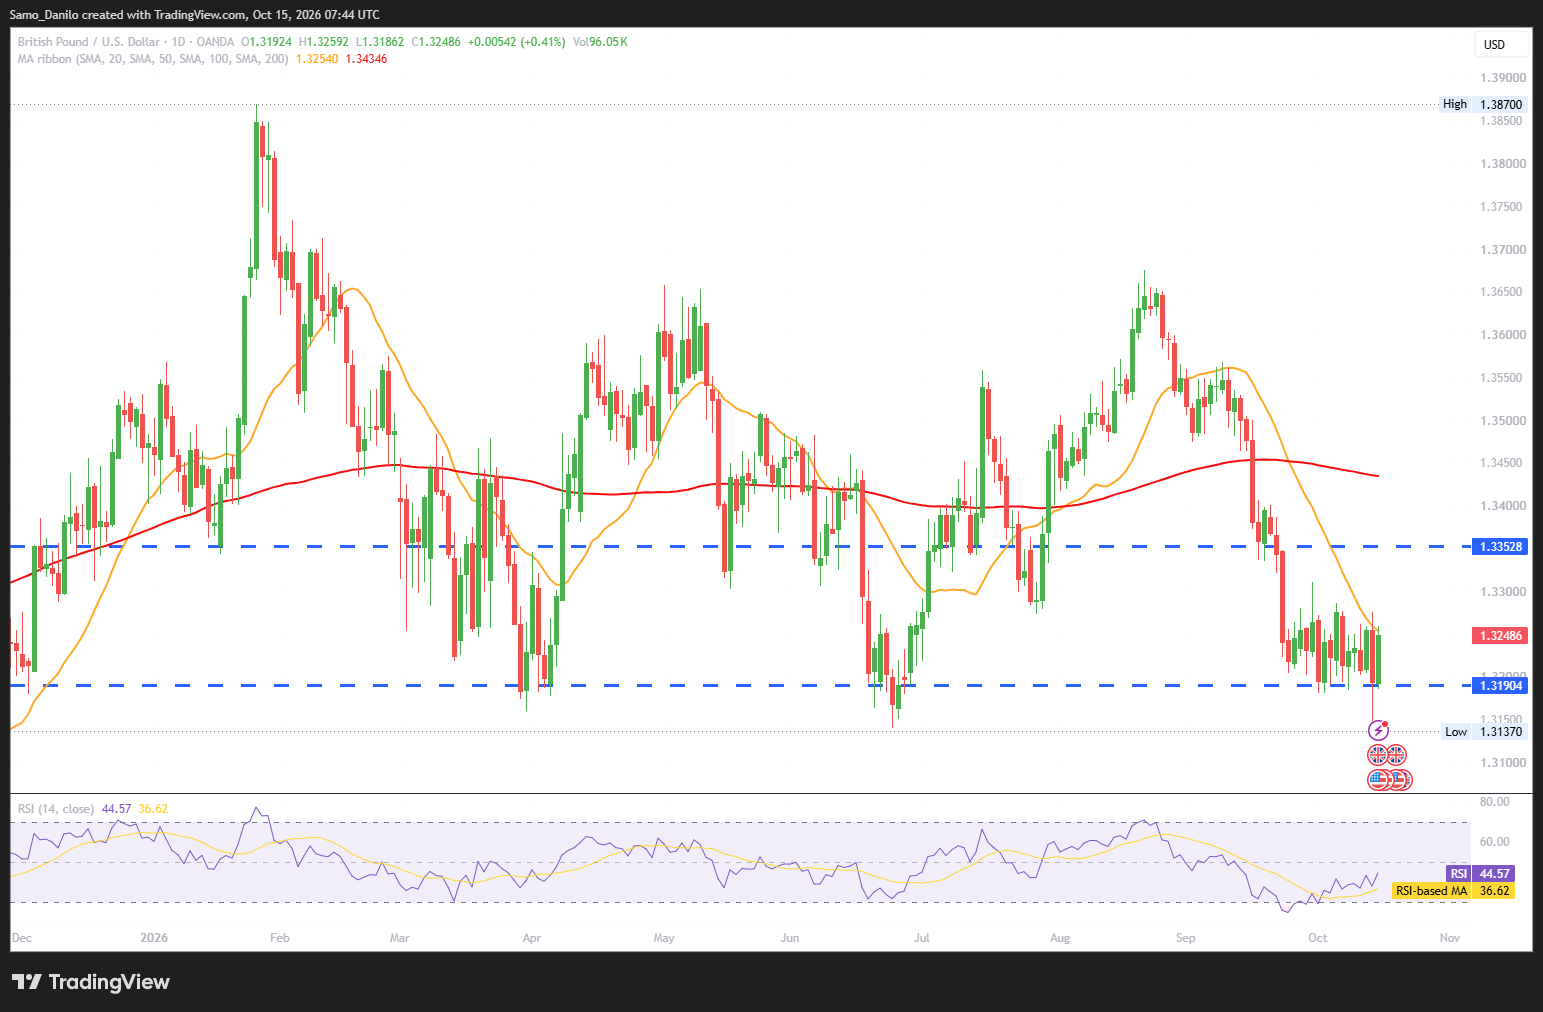
- GBP/USD Price: GBP/USD is holding steady around 1.3250 after rebounding from Wednesday’s low of 1.3137. However, the pair remains within its recent trading range, suggesting that the recovery has yet to establish a clear bullish trend.
- UK economy: UK GDP expanded by 0.1% in August, outperforming market expectations for a 0.1% contraction, although growth slowed considerably from the previous month’s 0.4% expansion.
- BoE’s Pill: The pound fell to fresh year-to-date lows on Wednesday after Bank of England Chief Economist Huw Pill cautioned that the interest rate increase discussed by policymakers in recent weeks should not necessarily be viewed as the beginning of a series of hikes.
- US CPI: US Consumer Price Index figures exceeded expectations in September, prompting markets to reconsider the possibility of another Federal Reserve interest rate hike at the October 28-29 meeting.
- Fed's Bowman: Federal Reserve Vice Chair for Supervision Michelle Bowman subsequently tempered expectations of another near-term rate increase, suggesting that the central bank may need more time to assess the effects of September’s rate hike before tightening policy again.
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Falling | | |
Closing statement: GBP/USD is consolidating around 1.3250 after recovering from 1.3137, with the stronger-than-expected UK GDP reading providing some support to sterling. However, Huw Pill’s cautious remarks continue to weigh on expectations for BoE tightening, while stronger US inflation has revived the prospect of another Fed rate hike. Bowman’s more cautious stance creates uncertainty for the dollar, leaving GBP/USD sensitive to changing interest-rate expectations and the ability of the pair to break out of its recent trading range.
XAUUSD
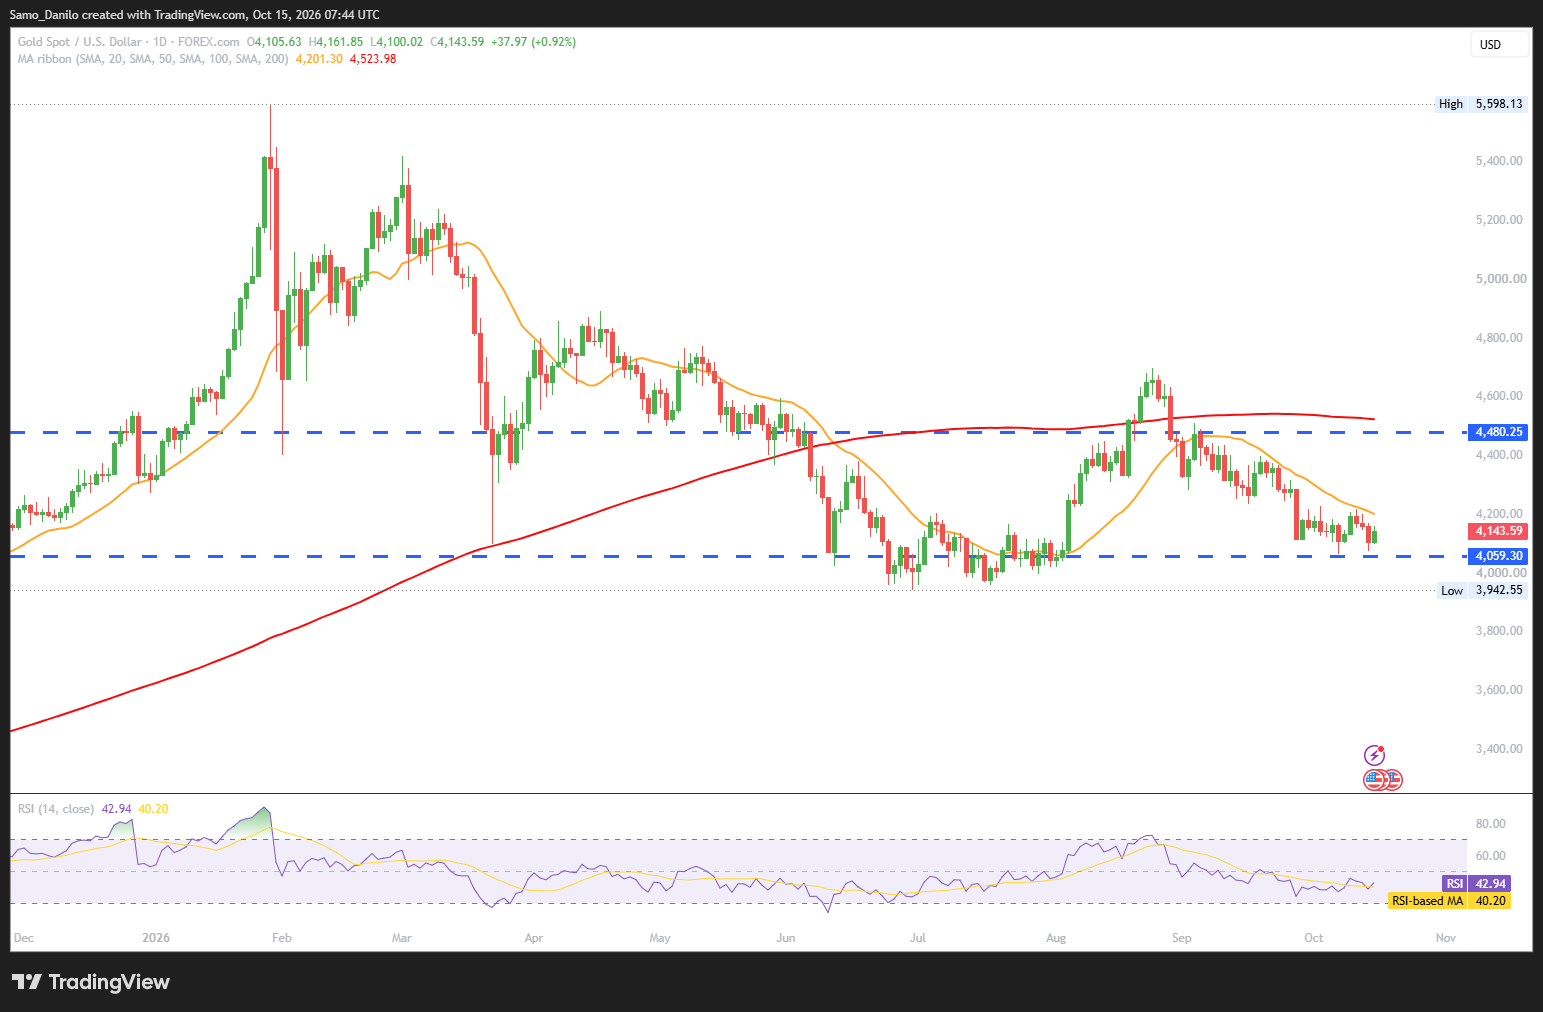
- XAU/USD Price: Gold (XAU/USD) is holding modest intraday gains during Thursday’s early European session, trading around $4,144 amid a broadly weaker US dollar.
- Fed expectations: Despite US CPI rising more than projected, the inflation report failed to significantly strengthen expectations for a more hawkish Federal Reserve. According to the CME FedWatch tool, the probability of a rate hike at the Fed’s upcoming policy meeting increased only marginally, to 27% from 22% before the data release, limiting the report’s support for the US dollar and helping gold recover.
- US-China: The South China Morning Post, citing sources, reported that the US and China are competing to shape the artificial intelligence agenda ahead of talks between President Donald Trump and President Xi Jinping in Shenzhen.
- Fed’s Barkin: Federal Reserve official Thomas Barkin, a non-voting member, said the latest CPI report was higher than he had hoped, while adding that he was not seeing AI-related job losses on a large scale.
- Fed's Daly: San Francisco Fed President Mary Daly, a non-voting member known for her relatively dovish stance, said further rate hikes were more likely than not to be needed, but stressed that they were not urgent.
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold has recovered to around $4,144 as a weaker US dollar and the limited reaction to stronger-than-expected US inflation help the metal snap its three-day losing streak. However, Barkin’s inflation concerns and Daly’s view that further rate hikes may be necessary could limit the recovery if markets begin pricing in tighter monetary policy. In the near term, XAU/USD may find support if the dollar remains weak and rate-hike expectations stay contained, while renewed hawkish repricing could put pressure on prices.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, is drifting lower during Thursday’s European session, extending Wednesday’s modest decline from near the $95.00 psychological level, which marked a high of more than two weeks.
- Shipping concerns: Chinese shipping firms are reportedly facing collapse amid concerns over shipping capacity, while the US is said to be discussing lifting some sanctions on shadow-fleet vessels to reduce global freight rates and improve oil flows in the Middle East.
- Russian raffineries: Russian Deputy Prime Minister Alexander Novak said talks between the Russian and US governments are underway to ensure diesel supplies, adding that a number of Russian refineries have completed maintenance.
- Ukraine plans: According to the Financial Times, Ukrainian President Volodymyr Zelenskyy said Ukraine would resume strikes on Russian refineries.
- North Sea drilling: UK Prime Minister Andy Burnham said approval for additional oil and gas drilling at the Jackdaw and Rosebank North Sea sites has been delayed by government procedures and lengthy bureaucratic discussions. Burnham indicated that he would take a pragmatic approach to drilling amid calls from energy executives to proceed, although the projects had been blocked by Scottish courts on environmental grounds in 2024.
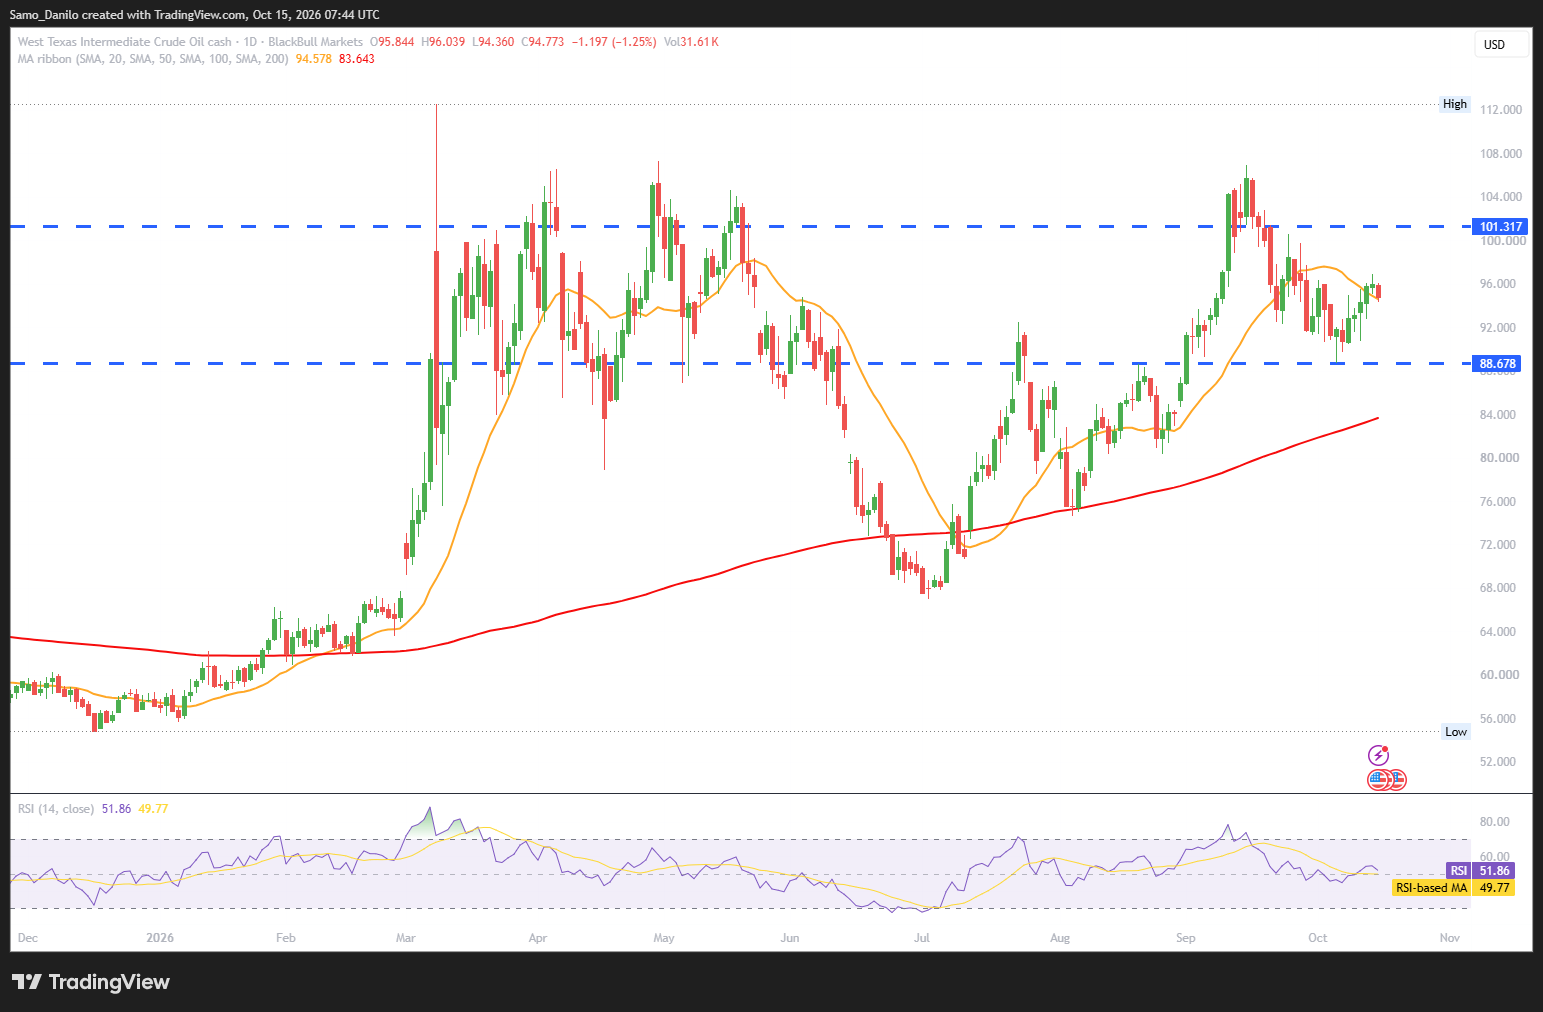
| SMA (20) | Slightly Rising |  |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: WTI is retreating from its recent high near $95.00 as traders assess developments in shipping, Russian fuel production and potential changes to US sanctions. Renewed Ukrainian strikes on Russian refineries and delays to North Sea drilling approvals could support prices by adding to supply uncertainty. However, any easing of shipping constraints or recovery in Russian refinery output could reduce supply pressures, leaving the near-term outlook sensitive to geopolitical developments and changes in actual oil flows.
DAX
- DAX 40 Price: The DAX 40 is trading higher at around 25,300 points on Thursday morning.
- ECB’s Dolenc: ECB policymaker Primož Dolenc, representing Slovenia in an acting capacity, said there are no signs of second-round inflation effects yet and noted that the labour market is no longer as tight.
- German minister: German Finance Minister Lars Klingbeil said it was worrying that the United States appeared to be reopening relations with Russia following the G20 meeting.
- Le Pen statement: French conservative leader Marine Le Pen stated that France is not in a position to continue financing Ukraine.
- Data ahead: Thursday’s US economic calendar includes labour market data, producer price figures and retail sales, all of which could influence financial markets.
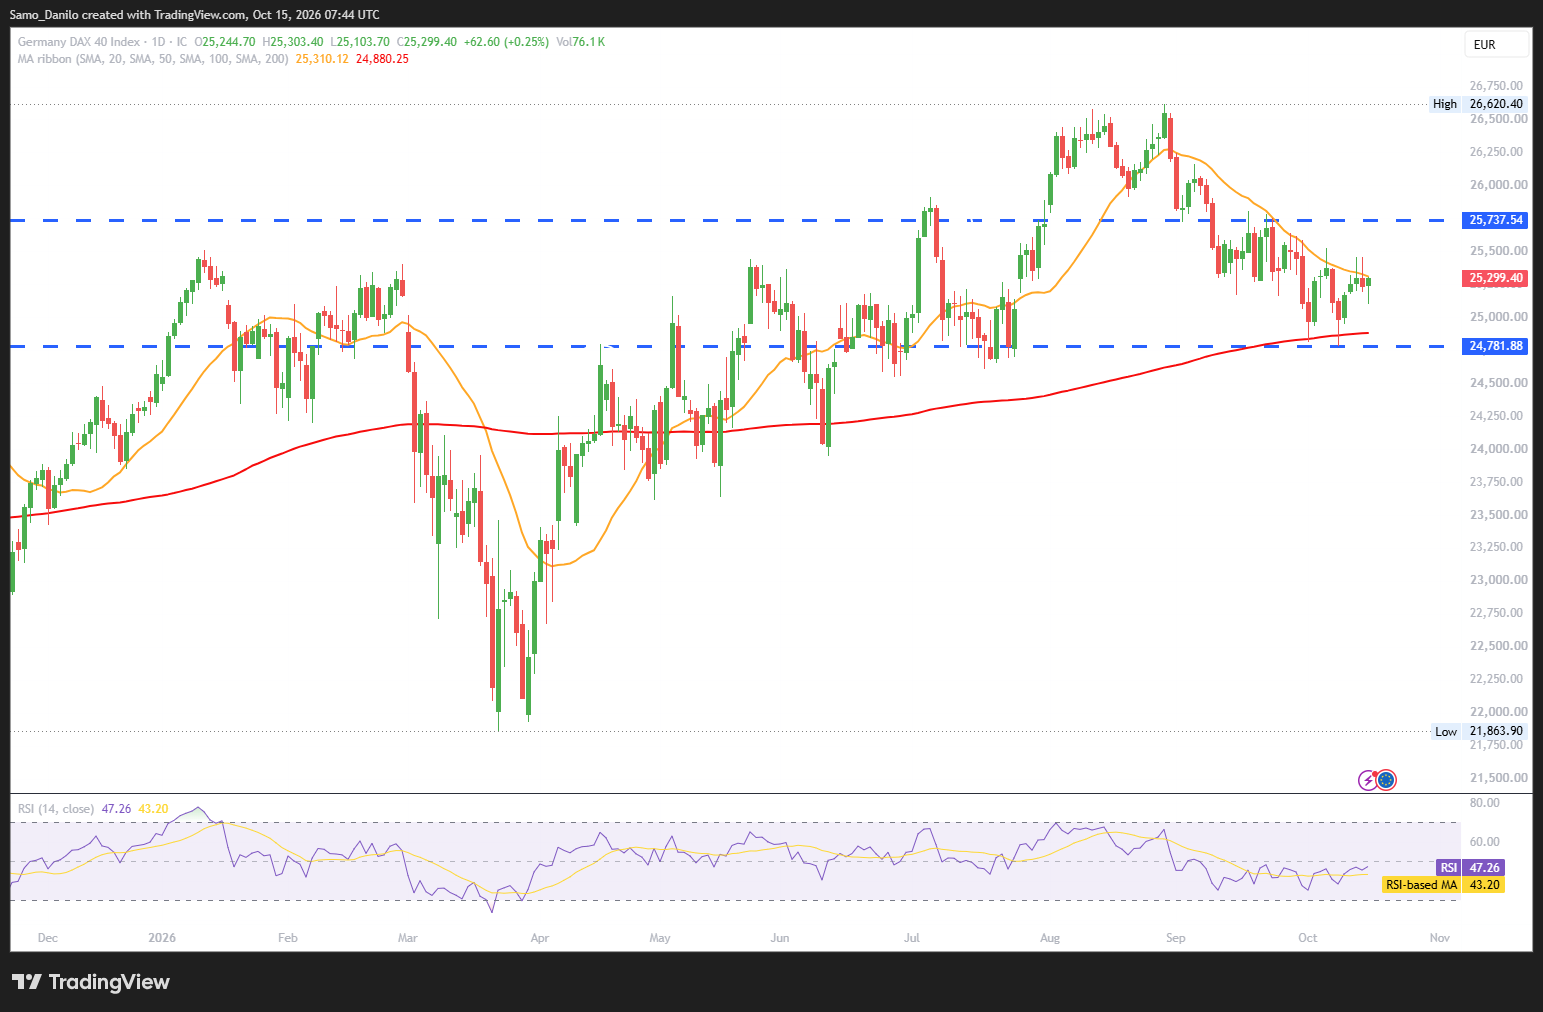
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 is trading higher around 25,300 points, although the outlook remains sensitive to ECB policy signals and geopolitical uncertainty. Today’s US labour market, producer price and retail sales data could provide the next major catalyst, with weaker figures potentially supporting equities through lower rate expectations, while stronger readings could increase pressure on valuations.