Nvidia Market Opportunity 24.09.2026.
- Nvidia Corporation (ticker: NVDA) started as a graphics card company. It is now, functionally, the backbone of the AI economy. That transition didn't happen overnight, but at this point it's hard to argue with the numbers. The Santa Clara chipmaker invented the GPU and has since turned it into the primary compute engine behind artificial intelligence, from training the largest frontier models to running inference at scale across data centers worldwide.
- The Numbers
Second-quarter revenue came in at $96.22 billion, up 106% year over year, comfortably beating the $92.18 billion the Street was expecting. For Q3, the company guided to a range of $105.84 to $110.16 billion, representing year-over-year growth of roughly 86% to 93%. The CFO added that demand is outpacing supply, not the other way around. That's a problem most companies would take.
The longer-term picture is even more striking. Nvidia's data center revenue is projected to grow from around $115 billion in 2025 to roughly $483 billion by 2030. The GPU market overall is estimated to reach $811 billion by 2035, up from $36 billion today. Nvidia holds over 80% of that market. AMD is the only real competitor, and it is American. -
Why the growth isn't slowing
Jensen Huang's argument on the earnings call is worth understanding because it's counterintuitive. When asked whether the rise of open-source AI models might eventually reduce demand for Nvidia hardware, he said the opposite is true - both open and closed models are scaling fast, and both run on Nvidia infrastructure. More models, more compute, more chips. The question of who wins the model race doesn't change who wins the hardware race.
The CFO Colette Kress backed that up with a number that stopped a lot of analysts mid-sentence: Nvidia expects revenue to grow approximately 70% in fiscal 2028. Consensus was sitting at around 45%. She also said customers' own forecasts point to Nvidia's growth doubling the following year. "Incredibly, we are seeing demand acceleration even at our scale" is not language companies use when they're worried about headwinds. -
The roadmap
The chip pipeline is worth taking seriously for a long-term hold thesis. Rubin GPUs arrive in H2 2026, Rubin Ultra in H2 2027, and Feynman in 2028 - each generation roughly doubling performance on the previous one. That's not a company running out of things to sell. That's a company with a credible product pipeline through the end of the decade, which matters when you're thinking about holding through multiple cycles. -
Strategic moves
Two developments stand out beyond the core chip business. First, Nvidia has secured financing partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to mobilize over $500 billion in third-party capital for AI infrastructure buildout. That's not just a product company anymore, that's a company shaping how AI compute gets financed globally.
Second,, according to Bloomberg, Nvidia is in advanced negotiations to acquire Hugging Face, the platform where most of the AI model development community lives, for roughly $12.9 billion, with an additional ~$1 billion retention package for employees. If that closes, Nvidia moves from selling the hardware that runs AI to owning the platform where AI models are built and distributed. That's a meaningful shift in strategic positioning. -
Technical analysis - Daily chart
Price action since January 2026
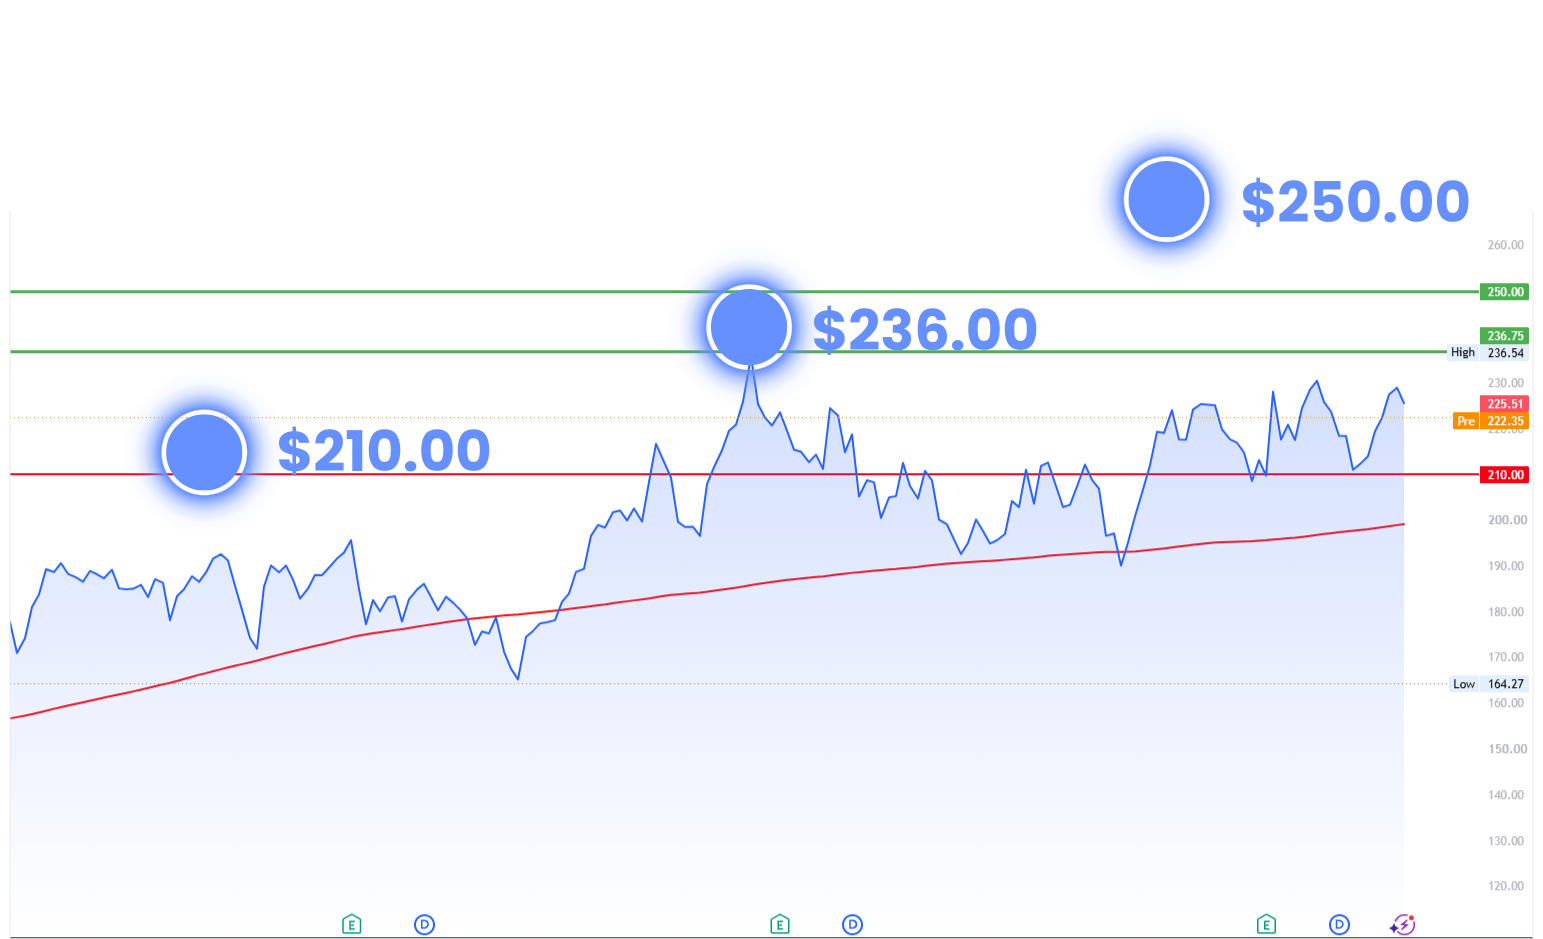
NVDA opened the year trading in the $185–195 range, broadly flat through January and into February. The real story came in late March and April, when the stock sold off sharply to the year's low of $164.27, a significant drawdown of roughly 15% from where it started the year. That April low is the most important reference point on this chart, because what happened next defined the entire second half of 2026.
The recovery was fast and clean. From the $164 lows, NVDA rallied almost without pause through May, reclaiming the 50 SMA and pushing all the way to the $229–230 area, effectively erasing the entire correction and then some in under two months. That kind of V-shaped recovery on high conviction tends to signal genuine demand rather than a short-covering bounce. -
Where things stand now
$236.54 is the year's high and the only meaningful resistance overhead. A clean break and daily close above that level opens up a move into new all-time high territory with little technical overhead to slow it down. On the downside, the 50 SMA at $220.53 is now the first line of support, followed by the $198–200 zone where the 200 SMA is approaching. Holding above $220 on any near-term pullback would keep the bullish structure fully intact.
2026 has been a year of two halves so far - a strong rally to new highs, a sharp correction that tested but didn't break the long-term trend, and a recovery that is now approaching the first real test of whether the bulls have fully regained control. For a long-term hold, the chart is not alarming. - Technical point of view: in April 2019, the coffee futures fell to around $87 per pound, the lowest price since September 2005. While the coffee market has been volatile, the trend has been bullish over the past four years. The bullish trend in the Brazilian real versus the U.S. dollar is also a positive factor for coffee prices. USD/BRL fell from around 5.54 in 2022. to around 4.70 in August 2023. while the current value is around 4.90.
-
The risk
None of this means buying NVDA is risk-free. A stock that has run this hard carries valuation risk. Any miss against elevated expectations tends to hit hard. Geopolitical exposure around chip export restrictions, particularly to China, is real and ongoing. And while AMD is the only serious GPU competitor today, hyperscalers building their own silicon in-house is a longer-term structural question worth watching. -
Bottom line
For a long-term position, the thesis is straightforward: Nvidia is the pick-and-shovel play on AI infrastructure, it has a clear product roadmap through 2028, the financials are beating expectations by wide margins, and management is guiding well above what analysts projected. The company is supply-constrained, not demand-constrained. That's a position most investors would want to be in.
Nvidia Corporation (NVDA) Calculation Example:
- Expected Price Direction: Up
- Position Type: Long
- Investment Budget Example: $1000
- Investment Size: 0.1 lot = 10 shares
| Close Price (Scenario 2) | $245.00 | + $200.00 |
| Close Price (Scenario 1) | $255.00 | + $300.00 |
| Close Price (Scenario 3) | $205.00 | - $200.00 |
This report is for informational purposes only and does not constitute financial advice. CFD trading involves risk and may not be suitable for all investors.